Burst Pipe Water Damage in Florida: The $10,000 Insurance Cap
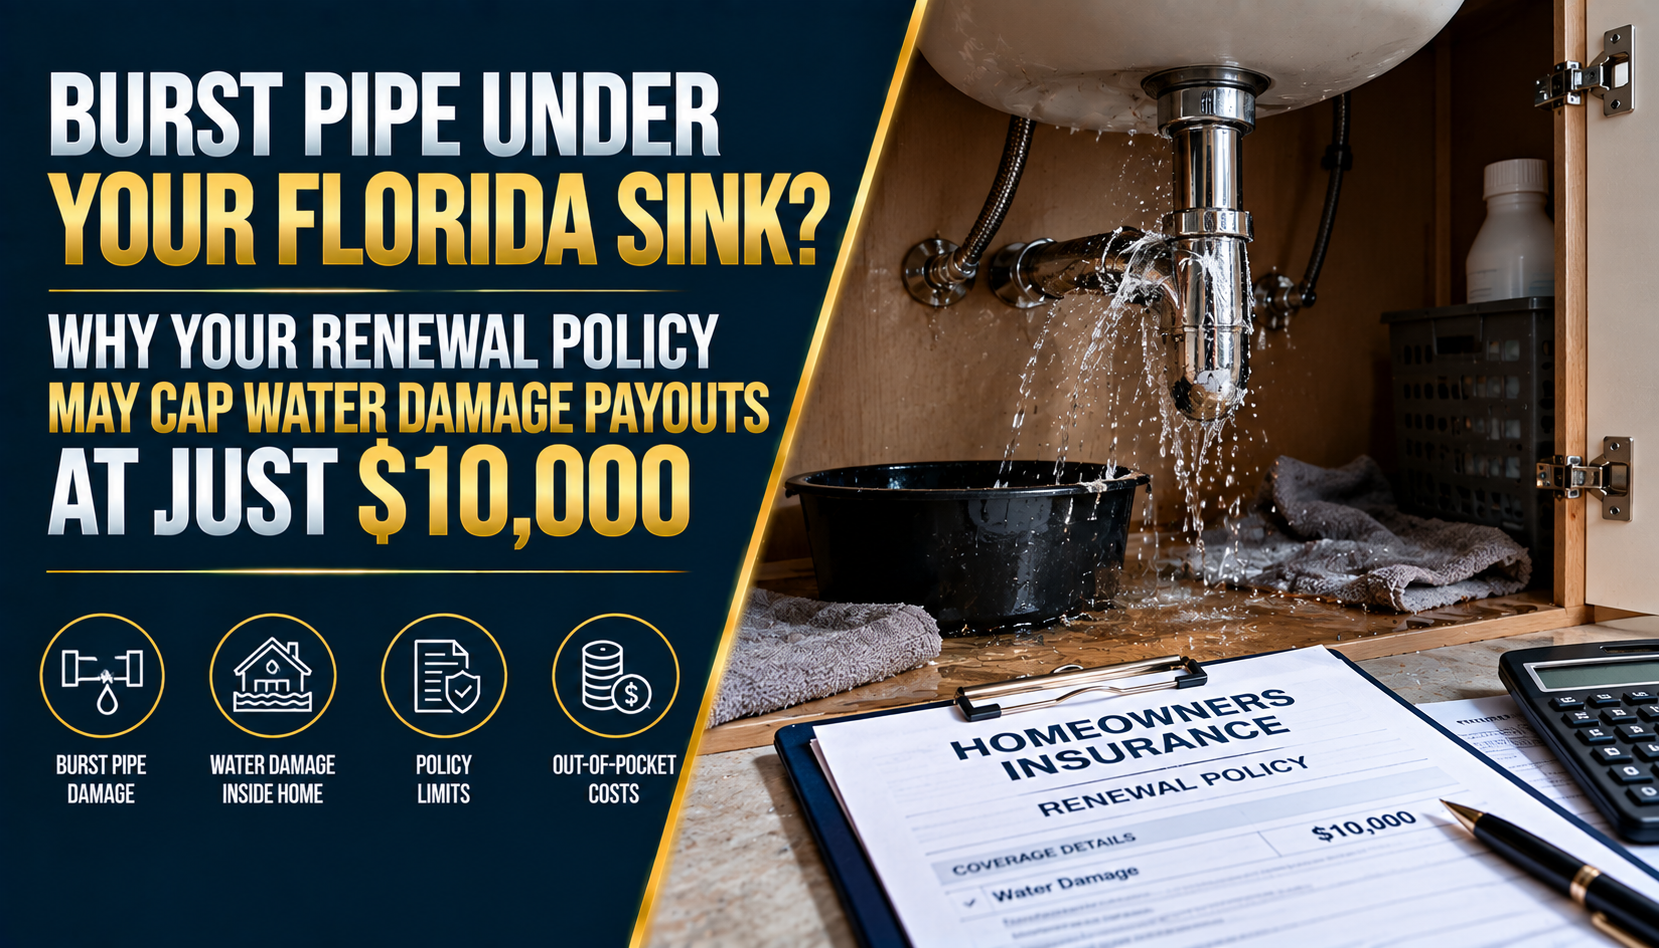
Burst Pipe Under Your Florida Sink? Why Your Renewal Policy May Cap Water Damage Payouts at Just $10,000
The Direct Answer
Here is a quiet policy change hitting Florida homeowners during policy renewals in 2026: many insurance companies are adding endorsement caps that limit non-weather water damage payouts—such as burst pipes, leaking water heaters, or overflowing sinks—to a maximum of $10,000, regardless of your total dwelling coverage.
When you purchase or renew a homeowners insurance policy in Florida, it is easy to focus on your main Dwelling Coverage (Coverage A) limit—such as $400,000 or $500,000.
However, hidden deep within renewal policy documents, insurers are increasingly slipping in Limited Water Damage Endorsements.
If a plumbing pipe bursts under your kitchen sink, an upstairs bathroom supply line snaps, or an appliance leaks, a average restoration job involving drywall removal, mold remediation, cabinetry replacement, and flooring repair can easily cost $30,000 to $60,000+.
If your policy contains a $10,000 sublimit, your insurance carrier will write a check for $10,000 (minus your deductible) and leave you personally responsible for the remaining tens of thousands of dollars in repairs.
Waking up to standing water pouring out from under your kitchen cabinets or bathroom vanity is a homeowner's worst nightmare. Finding out after the cleanup team leaves that your insurance policy will only cover a fraction of the restoration bill makes a bad situation infinitely worse.
1. What Is the $10,000 Limited Water Damage Endorsement?
Water damage claims not related to weather (such as plumbing failures, broken lines, and appliance leaks) are historically among the most frequent and costly claims filed in Florida.
To reduce financial exposure without drastically raising base premium rates on paper, many carriers now attach a Limited Water Damage Coverage Endorsement upon policy renewal:
- The Sublimit: It caps total payments for all water damage loss—including emergency water extraction, structural drying, tear-out, and physical repairs—at a strict fixed limit, usually $10,000.
- Managed Repair Requirements: Some carriers offer to waive or raise the $10,000 cap only if you agree to use their designated network of preferred contractors (a "Managed Repair Program").
- Plumbing Repair Exclusions: Remember that standard property insurance policies cover the resulting damage caused by water, but they almost never pay for the actual repair or replacement of the broken pipe or plumbing fixture itself.
2. Real-World Breakdown: The True Cost of a Kitchen Burst Pipe
Plumbing leaks under sinks or inside walls rarely cause minimal damage. Water migrates quickly under laminate or hardwood flooring, soaks into drywall, destroys custom cabinetry, and creates an ideal environment for toxic mold within 24 to 48 hours.
Here is what a typical non-weather water damage restoration bill looks like in Florida:
- Emergency Water Extraction & Dehumidification: $4,500
- Mold Remediation & Containment: $6,000
- Drywall, Baseboard, & Insulation Removal/Replacement: $5,500
- Custom Kitchen Cabinetry & Countertop Replacement: $18,000
- Flooring Replacement: $8,000
- Total Restoration Cost: $42,000
- Insurance Payout with $10,000 Sublimit: $10,000 (Minus Deductible)
- Your Out-of-Pocket Loss: $32,000+
Without reviewing your renewal paperwork carefully, this $32,000 gap comes directly out of your personal savings.
3. How to Protect Your Home Against Water Damage Limits
You do not have to accept a $10,000 cap on water damage claims. Take these steps to ensure your property remains adequately covered:
- Audit Your Annual Renewal Policy Documents: Look closely at the "Forms and Endorsements" section of your policy schedule for terms like "Limited Water Damage Coverage," "Water Damage Sublimit," or "Option to Buy Back Water Coverage."
- Purchase a Water Damage Buy-Back Endorsement: Most carriers allow you to buy back full water damage coverage up to your main Dwelling Coverage limit (or a higher sublimit like $50,000 or $100,000) for a nominal increase in your annual premium.
- Install Smart Leak Detection & Automatic Shut-Off Valves: Installing smart water shut-off systems (such as Flo by Moen or Phyn) can prevent catastrophic leaks before they spread—and many Florida insurance carriers offer premium discounts for homes with active leak prevention systems.
Why Working with an Independent Agency Matters
Policy endorsements, sublimits, and managed repair clauses can be difficult to spot on routine policy renewal notices. At Walker Insurance Agency, we review every line of your Florida homeowners policy to protect you from unexpected sublimits.
- Endorsement Audits & Buy-Back Options: We identify hidden sublimits on non-weather water damage and present clear options to buy back full coverage limits.
- Customized Property Protection: We evaluate your home’s age, plumbing materials, and appliances to match you with carriers offering comprehensive water damage coverage.
- Dedicated Local Advocacy: Located in Stuart, Florida, our independent team works directly for you—helping you navigate policy terms, prevent coverage gaps, and secure fair claims handling.
Frequently Asked Questions
1. Does the $10,000 water damage cap apply to hurricane or flood damage?
No. The $10,000 Limited Water Damage Endorsement applies specifically to internal, non-weather plumbing leaks and appliance failures. Storm surge and flooding require a separate Flood Insurance policy, while wind-driven rain from a hurricane is covered under your standard windstorm provisions (subject to your hurricane deductible).
2. Why did my insurance company add this $10,000 limit without asking me?
Florida insurance regulations allow carriers to modify policy terms and attach standard endorsements upon policy renewal, provided they send a written "Notice of Change in Policy Terms." Because these notices are often mailed alongside lengthy renewal packets, many policyholders overlook them.
3. Will my policy cover mold damage caused by a burst pipe?
Standard Florida policies usually include a separate Mold Sublimit (typically $10,000). However, if water damage from a sudden burst pipe is capped at $10,000 under a water sublimit, the total combined payout for both water extraction and mold cleanup may still be restricted by your policy's overarching water damage endorsement language.
Protect Your Home and Your Savings Today
Don't wait for a broken pipe under your sink to discover that your policy caps water damage repairs at a fraction of the real cost. Auditing your renewal policy today guarantees complete financial protection against unexpected plumbing emergencies.
Keep your home, your plumbing, and your savings fully secured. Contact Walker Insurance Agency today for a fast, zero-pressure Florida home insurance review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Paneles Solares y Seguro de Casa en Florida (2026): Cobertura y Gastos
¿Cubre el seguro en Florida quitar los paneles solares para reparar el techo tras una tormenta en 2026? Conoce las brechas de cobertura y evita gastos inesperados.
Read More →
Florida Solar Panels & Windstorm Claims: The $10,000 Detach Fee
Installed solar panels on your Florida home? Learn why windstorm roof claims can trigger a $10,000 out-of-pocket panel removal fee and how to cover it.
Read More →
¿Cubre el Seguro el Costo Total de una Tubería Rota en Florida? (2026)
¿Se rompió una tubería en tu casa en Florida? Descubre si tu seguro cubre la reparación completa o si aplica el tope estricto de $10,000 en 2026.
Read More →