Dog Owner Insurance in Florida (2026): Liability & Breed Exclusions
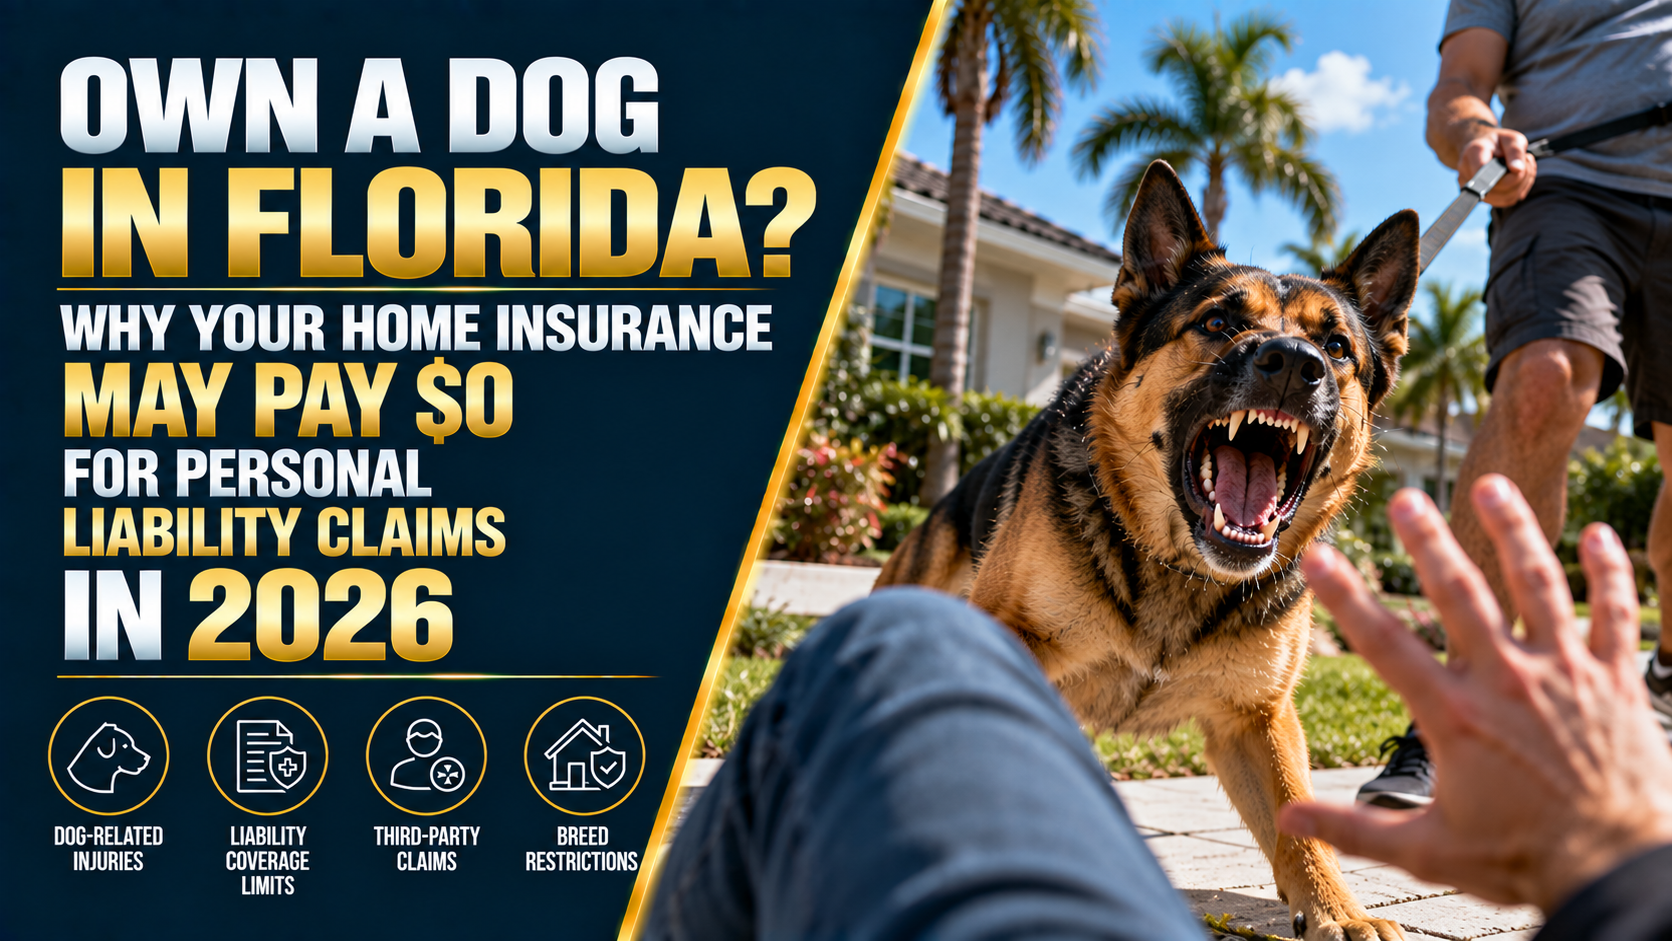
Own a Dog in Florida? Why Your Home Insurance May Pay $0 for Personal Liability Claims in 2026
The Direct Answer
Here is a critical coverage risk facing Florida pet owners: if your dog bites a guest, delivery worker, or neighbor, your standard homeowners insurance policy may deny the personal liability claim completely—paying $0 for legal defense or medical bills—because many Florida insurers explicitly exclude dog bites, limit canine liability to $0, or restrict coverage based on specific dog breeds.
Florida ranks among the highest states in the nation for dog bite liability claims, with medical treatment and legal settlements often exceeding $50,000 to $100,000 per incident. Under Florida law (F.S. § 767.04), dog owners face strict liability for injuries their pet causes to others in a public place or lawfully on private property, regardless of whether the dog has ever shown prior aggression.
Despite this strict legal standard, insurance carriers across Florida have aggressively tightened policy wording to reduce risk. If your policy contains a Dog Bite Exclusion, a Breed Restriction Clause, or requires an unreported pet disclosure, a single unexpected reaction from your dog could force you to pay massive medical expenses and court judgments directly out of pocket.
A loyal family pet reacting defensively to a quick movement or an unfamiliar face is every owner's nightmare. Finding out after an incident that your homeowners insurance has completely washed its hands of the legal and financial responsibility turns a stressful accident into a catastrophic financial loss.
1. Why Standard Home Insurance Denies Dog Liability Claims
While personal liability coverage (Coverage E) on a standard homeowners policy (HO-3) typically covers accidental injuries to guests on your property, insurers use specific policy exclusions to eliminate pet-related liabilities:
- Total Animal / Canine Exclusion Endorsements: Many Florida insurance carriers attach mandatory riders that exclude all liability claims caused by any domestic animal owned or kept on the premises.
- Restricted Breed Lists: Carriers routinely maintain lists of excluded or high-risk breeds. If your dog falls into these categories or is a mixed breed containing excluded genetics, liability claims involving the pet are automatically denied.
- Sublimited Coverage: Some policies do not exclude dog bites entirely, but instead cap animal liability coverage at a minimal sublimit—such as $10,000 or $25,000—which falls drastically short of modern medical bills and legal costs.
- Unreported Pet Exclusions / Application Material Misrepresentation: Failing to disclose an existing dog on your insurance application or renewal questionnaire can give the insurer legal grounds to void coverage or deny the claim outright for misrepresentation.
2. Comparing Your Canine Liability Insurance Options
Understanding how different insurance structures respond to pet injury claims helps secure complete protection:
- Standard Homeowners Insurance (HO-3): Base policy designed for general residential property liability. It does not cover dog bites if a canine exclusion or restricted breed list applies, or it may heavily cap payout limits.
- Animal Liability Endorsement / Rider: An optional add-on attached directly to your home insurance policy. It does cover medical payments, legal defense fees, and settlements caused by your dog, up to the endorsement's specific liability limit.
- Standalone Umbrella or Canine Liability Policy: A separate, dedicated insurance policy specifically designed for pet owners. It does cover high-limit personal liability protection ($100,000 to $1,000,000+) across all breeds, ensuring complete financial protection even if your primary home insurer excludes animals.
3. Essential Steps Every Florida Dog Owner Should Take
To protect your family, your finances, and your pet before an unexpected incident occurs, follow these key insurance steps:
- Review Your Policy's Water & Animal Exclusions: Check your current declarations page and policy form for attached riders labeled "Animal Liability Exclusion" or "Canine Exclusions."
- Disclose All Pets Accurately: Always report all dogs living on your property to your agent during application or policy renewals to prevent claim denials based on non-disclosure.
- Secure Dedicated Animal Liability Coverage: If your primary insurer excludes your dog's breed or imposes an animal restriction, purchase a dedicated Standalone Pet Liability Policy or add a specialized rider to maintain full liability protection.
Why Working with an Independent Agency Matters
Navigating strict liability laws, breed restrictions, and insurance exclusions requires knowledgeable local guidance. At Walker Insurance Agency, we audit Florida policies to ensure pet owners carry reliable, transparent coverage without hidden liability gaps.
- Pet Liability Audits: We examine your home or renters policy to confirm whether your dog is fully covered against third-party liability claims.
- Breed-Friendly Carrier Access: We partner with multiple top-rated Florida insurance carriers that offer comprehensive animal liability coverage without discriminatory breed restrictions.
- Customized Coverage Solutions: We structure high-limit personal umbrella or dedicated canine liability policies to protect your home and assets from costly lawsuits.
Frequently Asked Questions
1. Does Florida’s strict liability law apply even if my dog has never bitten anyone before?
Yes. Under Florida law, dog owners are strictly liable for damages caused by their dog biting someone in a public place or lawfully on private property. The legal "one-bite rule" (which required prior knowledge of viciousness) does not apply to dog bite injuries in Florida.
2. Will my homeowners policy cover a dog bite if the incident happens away from my home?
If your policy includes full personal liability coverage without animal exclusions, it typically covers your dog's actions both on and off your property (such as at a public park or on a walk). However, if your policy includes a total animal exclusion, claims are denied regardless of location.
3. Does registering my dog as a Service Animal or Emotional Support Animal (ESA) override insurance breed exclusions?
No. Insurance policies are private contracts and insurance carriers are generally permitted under Florida law to exclude liability or set underwriting guidelines based on breed risk, regardless of service or emotional support animal designations.
Protect Your Home and Your Dog Today
Don't wait for an accidental nip or fall to discover that your homeowners policy pays $0 for pet liability claims. Auditing your policy today ensures your home, your savings, and your beloved family pet remain fully protected.
Keep your property, your assets, and your family completely secure. Contact Walker Insurance Agency today for a fast, zero-pressure Florida home insurance review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro de Casa en Florida: Cláusula de Desocupación de 60 Días
¿Casa vacía en Florida por más de 60 días tras un huracán? Descubre por qué el seguro puede denegar reclamos por robo o fugas de agua en 2026.
Read More →
Florida Home Insurance: 60-Day Vacancy Clause & Hurricanes
Living away from your Florida home or second property after a hurricane? Learn how the 60-day vacancy clause can lead to denied insurance claims.
Read More →
Plazo de Prueba de Pérdida (Proof of Loss) NFIP en Florida (2026)
¿Cuál es el límite para entregar la Declaración Jurada de Pérdida (Proof of Loss) del seguro de inundación NFIP en Florida tras un huracán en 2026? Descubre los 60 días clave.
Read More →