Florida Business Interruption Insurance: Lost Income Claims (2026)
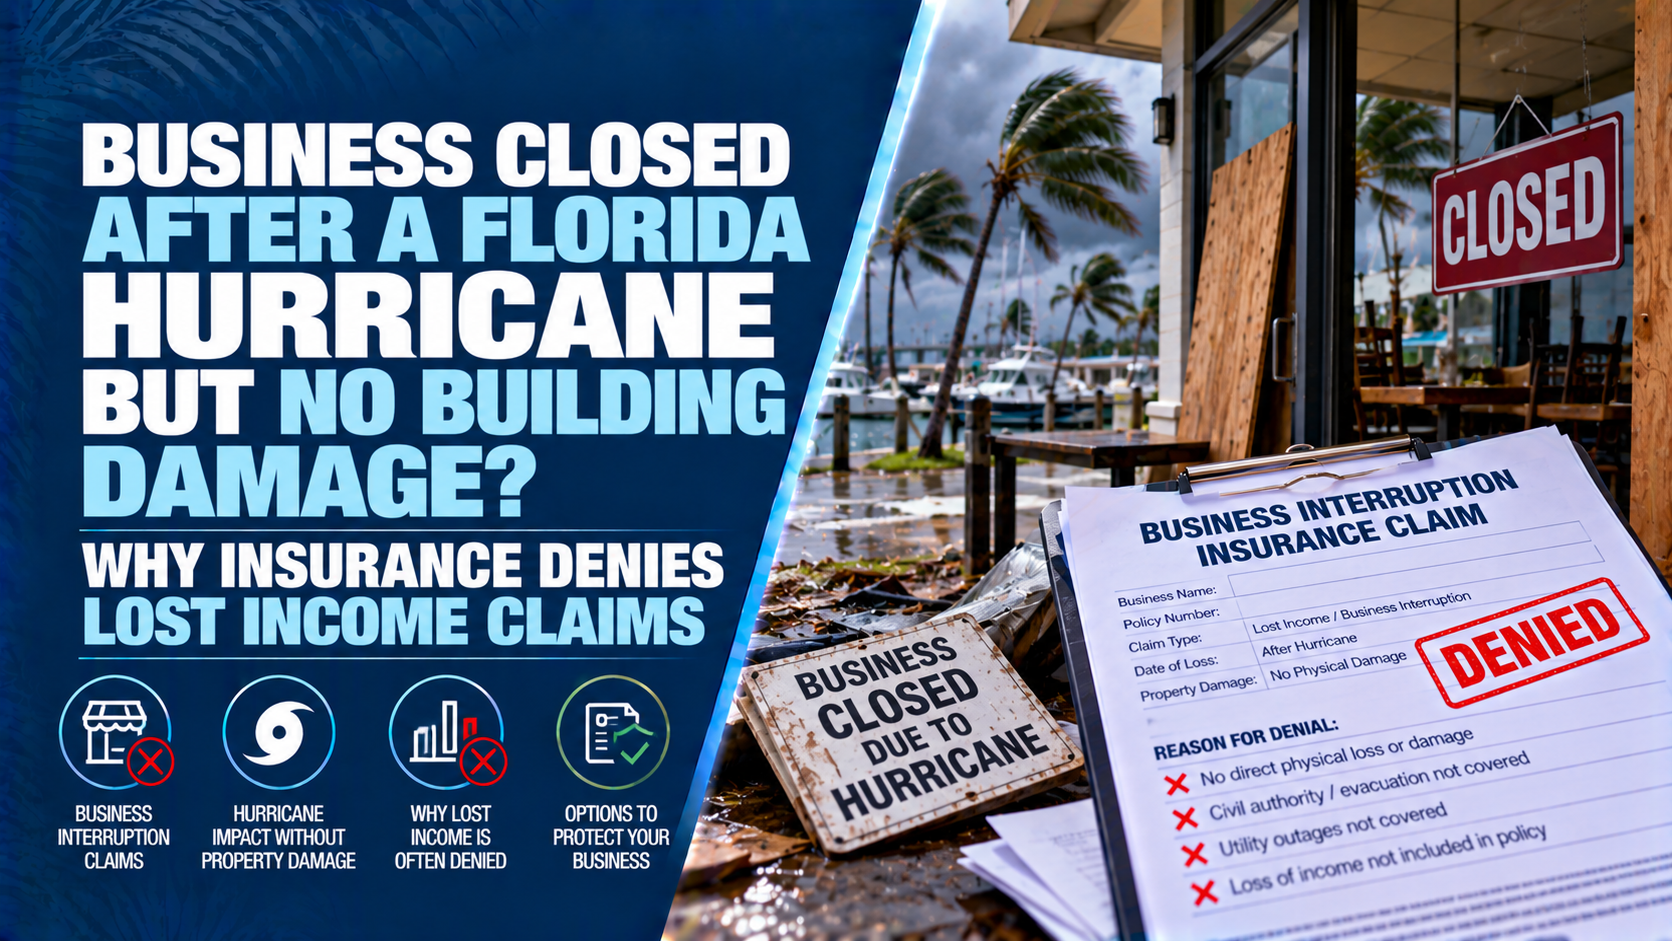
Business Closed After a Florida Hurricane but No Building Damage? Why Insurance Denies Lost Income Claims
The Direct Answer
Here is a major financial shock facing Florida business owners in 2026: if a hurricane causes mandatory area evacuations, widespread power outages, supply chain blockages, or curfew orders that force you to close your doors, your standard Business Interruption Insurance policy will deny your lost revenue claim if your physical building suffered no direct structural wind damage.
Commercial property policies and Businessowners Policies (BOPs) contain a foundational requirement known as the Direct Physical Loss Requirement. Insurance carriers do not compensate for lost revenue, payroll costs, or ongoing rent simply because a severe hurricane paralyzed your local economy or cut off electricity to your shopping plaza.
Under standard commercial policy terms, Business Interruption coverage is only triggered when a covered peril (like hurricane winds or fallen trees) causes direct physical damage to your insured property that directly halts your operations.
Without specialized endorsements like Off-Premises Utility Failure, Civil Authority Coverage, or Supply Chain / Contingent Business Interruption Riders, business owners must absorb 100% of their lost profits, continuing payroll, and fixed operational overhead out of pocket.
Surviving a major Florida hurricane without physical property damage feels like a relief—until you open your books and realize you lost weeks of revenue while fixed expenses like rent and payroll kept piling up. Understanding how commercial carriers evaluate Business Income claims is essential for protecting your cash flow.
1. Why Standard Business Interruption Denies Claims Without Physical Damage
Business Interruption insurance (Business Income Coverage) is designed to act as a financial bridge while a commercial building is physically repaired. When a facility suffers no structural damage, three primary policy exclusions and limitations prevent claim payouts:
- The Direct Physical Damage Trigger: Standard ISO commercial property forms explicitly state that Business Income coverage applies only when business suspension is caused by direct physical loss of or damage to property at the described premises.
- Off-Premises Utility Service Exclusions: If regional power lines, water mains, or telecommunication towers fail miles away from your building, standard property forms exclude the resulting business income losses unless an Off-Premises Utility Services Endorsement is attached to your policy.
- Strict Civil Authority Conditions: While Civil Authority Coverage can pay lost income when government orders block access to your storefront, standard policies require that a nearby physical structure suffered covered damage and that access to your business area was completely prohibited by law.
2. Standard Business Interruption vs. Expanded Commercial Riders
Comparing standard Business Income coverage with specialized commercial riders illustrates how to eliminate operational revenue gaps:
- Standard Business Interruption Policy: Pays lost revenue and continuing expenses only if the insured structure suffers direct physical damage from a covered peril. Denies claims for utility outages, curfew losses, and supply chain disruptions without building damage.
- Off-Premises Utility Service Interruption Rider: Reimburses lost net income and continuing expenses when regional utility failures (power, water, gas, or telecom) force your business to halt operations, even if your building is undamaged.
- Contingent Business Interruption (CBI) Rider: Reimburses lost revenue when key suppliers, manufacturing partners, or anchor tenants suffer storm damage that prevents them from delivering goods or driving customer traffic to your location.
3. Essential Endorsements for Florida Commercial Operations
To safeguard your cash flow and operational continuity against indirect hurricane disruptions in 2026, your commercial policy portfolio should incorporate four critical endorsements:
- Off-Premises Utility Services – Direct Damage & Time Element: Covers both physical damage (such as spoiled refrigerated inventory) and lost business income caused by off-site power grid or utility infrastructure failures.
- Enhanced Civil Authority Coverage: Extends the standard 14-to-30-day civil authority window and eases access restrictions, paying lost income when local emergency management issues mandatory evacuation or curfew orders.
- Contingent Business Interruption (CBI): Protects your business against revenue losses caused by physical damage to critical third-party vendors, ports, or distribution networks.
- Ingress / Egress Coverage: Reimburses lost business revenue when hurricane debris, fallen trees, or flooded roads physically block customers and employees from entering your commercial premises, regardless of whether your building sustained damage.
4. How to Properly Safeguard Your Business Revenue
Protecting your business continuity and profit margins against indirect hurricane shutdowns involves three strategic steps:
- Calculate Your True Daily Operational Overhead: Document continuing expenses—including key personnel payroll, commercial rent, equipment leases, and taxes—to establish an accurate daily Business Income limit.
- Audit Policy Exclusions for Utility and Civil Orders: Review your commercial policy declarations page with your agent to identify whether off-premises power outages or evacuation orders are covered or excluded.
- Attach Custom Business Income Endorsements: Work with an independent commercial agent to attach Utility Services, Ingress/Egress, and Civil Authority riders tailored to your industry.
Why Working with an Independent Agency Matters
Structuring commercial insurance for Florida’s volatile hurricane environment demands specialized risk management expertise. At Walker Insurance Agency, we specialize in customizing business insurance packages that keep local companies solvent before, during, and after major storms.
- Commercial Exposure Audits: We examine your policy forms to uncover hidden physical damage requirements, utility exclusions, and short civil authority windows.
- Access to Specialty Commercial Carriers: We partner with top-rated commercial lines underwriters to secure broad Business Interruption, Contingent Business Interruption, and Utility Failure riders.
- Comprehensive Financial Protection: We align your real property, commercial liability, and business income coverages into a seamless risk management plan.
Frequently Asked Questions
1. Does Business Interruption cover employee payroll during a mandatory hurricane evacuation?
If your policy includes Business Income with Extra Expense & Continuing Payroll, employee salaries can be reimbursed during a covered closure. However, if the closure lacks a direct physical damage trigger or a qualifying civil authority order, standard policies will not pay payroll costs.
2. How long does Civil Authority coverage pay lost income in Florida?
Standard Civil Authority clauses typically provide reimbursement for 14 to 30 days of lost business income, starting after a set waiting period (usually 24 to 72 hours). Higher time limits can be purchased through policy endorsements.
3. Will my policy pay for lost inventory if power is out for a week after a storm?
Spoiled inventory or food loss caused by an off-premises power outage is excluded under standard property forms. To receive compensation for spoiled stock, your policy must include a specific Spoilages / Utility Service Direct Damage Endorsement.
Protect Your Business Revenue and Cash Flow Today
Don't wait for a hurricane to shut down local utilities or roads before learning that your Business Interruption policy requires direct building damage. Securing proper commercial riders protects your income, your staff, and your company's future in 2026.
Keep your commercial operations, your payroll, and your business revenue completely secure. Contact Walker Insurance Agency today for a fast, zero-pressure commercial policy and business income review.
[GET A FREE FLORIDA COMMERCIAL INSURANCE QUOTE TODAY]
Call our commercial insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro Comercial en Florida: Pérdida de Ingresos sin Daños (2026)
¿Negocio cerrado por apagones o evacuación tras un huracán en Florida? Descubre por qué el seguro estándar deniega la pérdida de ingresos y cómo protegerte en 2026.
Read More →
Cobertura ALE en Florida (2026): Gastos tras un Huracán
¿Desplazado por un huracán en Florida? Descubre qué cubre la cobertura ALE (Pérdida de Uso), reglas de recibos y límites de reembolso en 2026.
Read More →
Florida ALE Coverage 2026: Hurricane Displacement & Receipts
Displaced after a Florida hurricane? Learn how Additional Living Expense (ALE) limits, ALE loss-of-use coverage, and receipt rules work in 2026.
Read More →