Florida Home Insurance: Fine Art & Jewelry Theft Limits
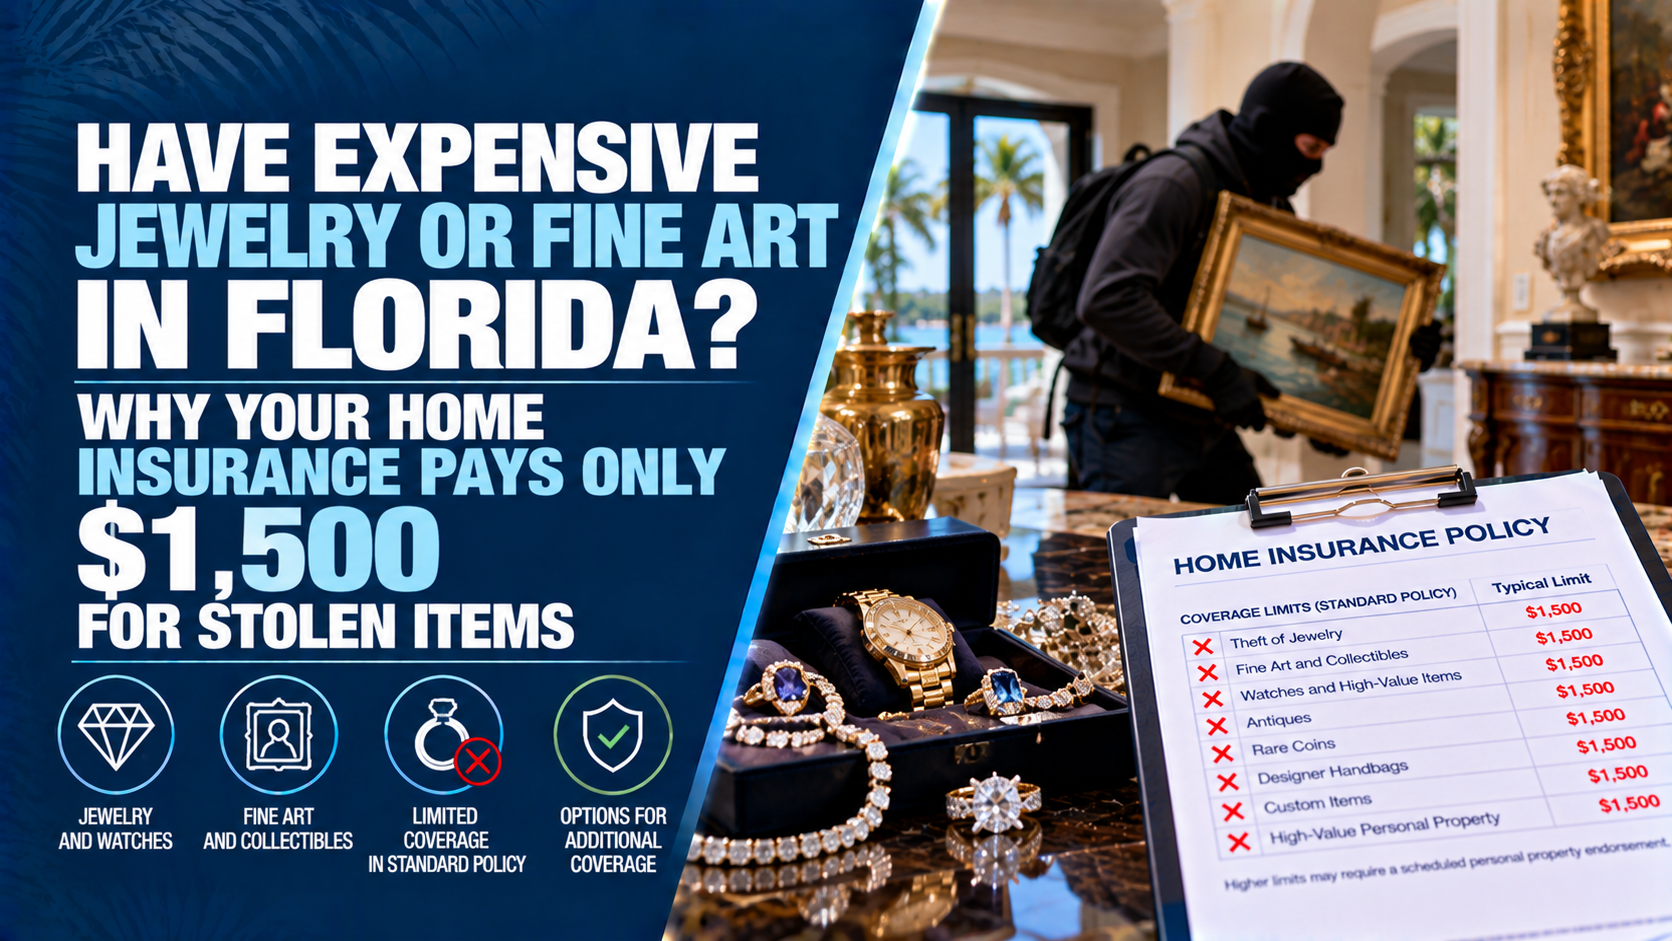
Have Expensive Jewelry or Fine Art in Florida? Why Your Home Insurance Pays Only $1,500 for Stolen Items
The Direct Answer
Here is a major financial shock facing Florida homeowners: if $50,000 worth of fine jewelry, luxury watches, or rare artwork is stolen from your home, a standard Florida homeowners insurance policy (HO-3) will limit its payout for theft to a sub-limit of just $1,500 to $2,500—total.
Most homeowners assume that carrying a $500,000 or $1,000,000 Personal Property (Coverage C) limit automatically protects everything inside their dwelling. However, standard homeowners policies contain explicit Special Limits of Liability on high-value, easily transportable personal items.
Insurance companies set strict internal sub-limits on category losses involving theft. Without adding a dedicated Scheduled Personal Property Endorsement (often called an insurance rider or floater), your carrier will write a check for the policy’s maximum category cap (minus your standard deductible), leaving you to absorb tens or hundreds of thousands of dollars in uncovered losses.
Investing in luxury timepieces, family heirlooms, engagement rings, or fine artwork is a rewarding passion. Realizing after a burglary or home invasion that your primary homeowners policy caps theft reimbursement at a fraction of your items' actual value can be financially devastating.
1. Why Standard Florida Home Insurance Caps Theft Losses
Standard home insurance forms are designed for general household furnishings, electronics, and clothing. When a claim involves luxury valuables, specific policy sub-limits trigger automatically:
- Category Theft Sub-Limits: Standard policies explicitly restrict theft payouts for jewelry, watches, furs, precious metals, and fine art to $1,500 aggregate per loss.
- Actual Cash Value (ACV) vs. Agreed Value: Under basic coverage, items are subject to age depreciation and standard deductible deductions, further reducing your actual check.
- Exclusions for Mysterious Disappearance: Standard policies only pay if you can prove an item was stolen during a break-in. If a ring falls off at the beach or disappears during a trip, a basic policy denies the claim entirely.
- Off-Premises Loss Restrictions: Standard personal property limits drop significantly when items are taken outside your residence, leaving travel jewelry highly exposed.
2. Standard Home Insurance vs. Scheduled Personal Property Riders
Understanding how standard coverage compares to a dedicated floater highlights why scheduling high-value items is essential:
- Standard Homeowners Policy (HO-3): Subject to a strict $1,500theftsub-limit,standardpolicydeductibles($1,000–$2,500+), ACV depreciation, and no coverage for accidental loss or breakage.
- Scheduled Personal Property Rider (Floater): Provides Agreed Value coverage based on professional appraisals, zero-deductible claims, worldwide loss protection, and full coverage for accidental loss, mysterious disappearance, or damage.
3. Essential Coverages Needed for Luxury Assets in Florida
To properly safeguard your luxury collections, fine art, and high-value heirlooms, your policy portfolio should include specialized endorsements:
- Scheduled Jewelry & Watch Floater: Lists each piece individually along with its appraised replacement value, ensuring 100% payout with no deductible in the event of theft, loss, or damage.
- Fine Art & Collectibles Valuation Rider: Covers paintings, sculptures, antiques, and rare collectibles under an Agreed Value framework that includes coverage for accidental breakage during handling or transit.
- Worldwide Loss Coverage: Extends full protection to your jewelry and watches while traveling domestically or internationally, covering airport losses, hotel safe thefts, and accidental loss.
- Inflation Guard for Precious Metals & Stones: Automatically adjusts scheduled values annually to keep pace with rising gold, diamond, and luxury watch market valuations.
4. How to Properly Insure Your High-Value Collections
Protecting your jewelry and fine art against catastrophic loss or theft involves three straightforward steps:
- Obtain Professional Appraisals: Have a certified gemologist or accredited art appraiser inspect and value your items to establish up-to-date replacement costs.
- Catalog Serial Numbers and High-Resolution Photos: Maintain a secure digital record of receipts, certificates of authenticity (such as GIA diamonds or watch papers), and detailed photos.
- Schedule Your Items on Your Policy: Work with your agent to attach a Scheduled Personal Property rider to your policy, securing zero-deductible, full-value coverage.
Why Working with an Independent Agency Matters
Navigating high-value asset limits, appraisal requirements, and specialized floater riders requires local expertise. At Walker Insurance Agency, we specialize in customizing personal property protection for Florida homeowners and collectors.
- Personal Property Audits: We review your policy terms to identify hidden category sub-limits and eliminate multi-thousand-dollar claim gaps.
- Access to Specialty & High-Value Carriers: We partner with premier insurance carriers that offer broad floater riders, worldwide transit coverage, and agreed-value settlements.
- Seamless Appraisal Management: We help organize your documentation and appraisals to ensure every item is properly cataloged and fully protected.
Frequently Asked Questions
1. Does my standard home insurance deductible apply to scheduled jewelry?
No. When you schedule an item using a Scheduled Personal Property rider, the claim is typically settled with zero deductible, paying you the full agreed-upon appraised amount.
2. Is mysterious disappearance covered if I lose an engagement ring outside my home?
Not under a standard homeowners policy. However, a Scheduled Personal Property rider explicitly covers mysterious disappearance, paying out if your ring slips off or is misplaced while away from home.
3. How often should I update the appraisals on my fine art and jewelry?
In Florida, insurance experts recommend updating jewelry and art appraisals every 3 to 5 years—or sooner during periods of rapid market inflation for gold, diamonds, and luxury watch brands.
Protect Your High-Value Collections Today
Don't wait for a burglary or accidental loss to discover that your standard policy caps your fine art or jewelry coverage at $1,500. Scheduling your valuable items ensures your investment and peace of mind remain fully protected.
Keep your heirlooms, luxury assets, and financial security completely secure. Contact Walker Insurance Agency today for a fast, zero-pressure coverage audit and valuation review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro Comercial en Florida: Paneles Solares y Pérdida de Energía (2026)
¿Instalaste paneles solares en tu edificio en Florida? Descubre por qué el seguro comercial estándar deniega la carga en techo, ráfagas y pérdida de energía en 2026.
Read More →
Florida Commercial Solar Insurance: Roof Load & Panel Claims
Installed commercial solar in Florida? Learn why standard property insurance denies roof load, wind uplift, and panel claims, and how to stay protected.
Read More →
Horse Boarding Insurance in Florida: Boarder Injury & Horse Loss
Boarding horses or giving riding lessons in Florida? Learn why standard farm insurance may not cover boarder injuries, horse losses, or equine liability.
Read More →