Florida Hurricane Deductible 2026: The $20,000 Out-of-Pocket Gap
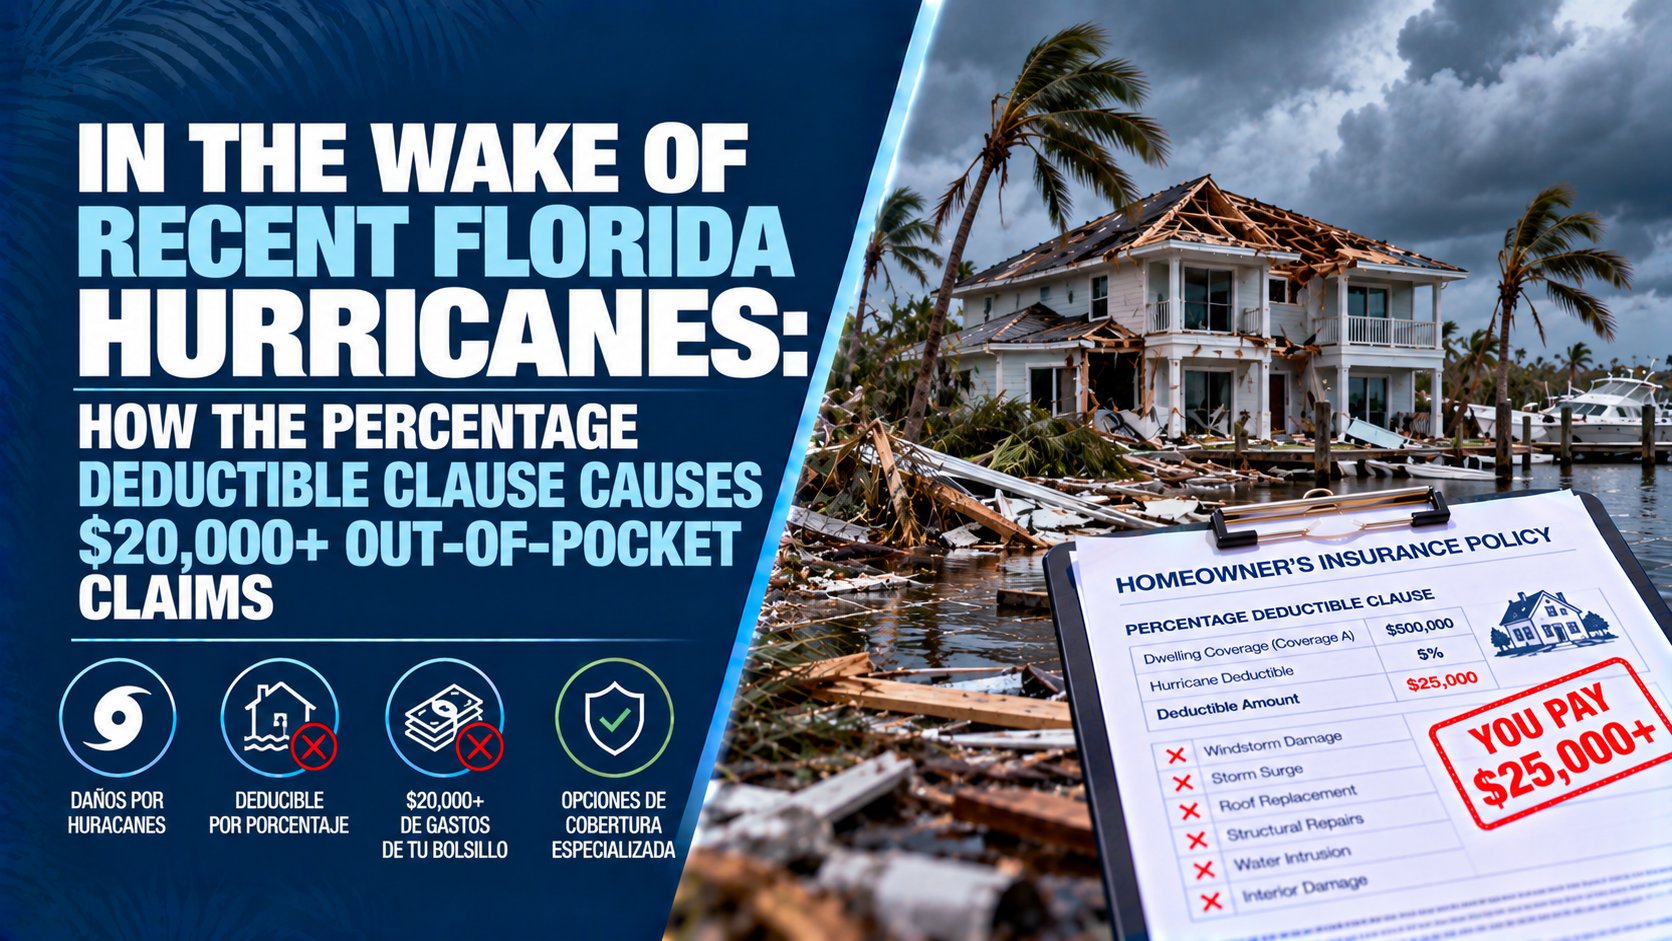
In the Wake of Recent Florida Hurricanes: How the Percentage Deductible Clause Causes $20,000+ Out-of-Pocket Claims
The Direct Answer
Here is a major financial shock facing Florida homeowners following recent storm seasons: a hurricane deductible is not a flat $500 or $1,000 fee. Instead, it is calculated as a percentage (typically 2%, 5%, or 10%) of your home’s Total Insured Dwelling Value (Coverage A)—forcing homeowners with a $500,000 home to pay $25,000 out of pocket before their insurance policy pays a single dollar.
Many homeowners assume that their standard policy deductible (such as the All Other Perils / AOP deductible of $1,000) applies to hurricane damage. However, Florida law allows insurance carriers to apply a separate, percentage-based Hurricane Deductible whenever damage is caused by a named hurricane declared by the National Hurricane Center.
When severe tropical storms or hurricanes strike the Sunshine State, thousands of property owners learn during the claims process that they must write a check for $10,000 to over $30,000 to contractors before insurance claim funds are released. Without proper financial planning or specialized deductible options, this percentage clause creates an immediate liquidity crisis for Florida families.
Surviving a major hurricane is emotionally exhausting. Realizing during clean-up that your insurance policy requires you to cover the first $20,000 or $30,000 of repairs out of your own bank account can feel financially overwhelming.
1. How the Percentage Hurricane Deductible Works
Unlike flat-dollar deductibles used for fire or theft, Florida hurricane deductibles are tied directly to your policy's structural coverage limit.
- Calculated Against Coverage A (Not the Loss): If your home is insured for $500,000 under Coverage A and you have a 5% hurricane deductible, your deductible is $25,000. Even if you only suffer $30,000 in roof and soffit damage, you must pay $25,000, and your insurer only pays $5,000.
- The Hurricane Trigger Window: Under Florida Statutes, the hurricane deductible triggers the moment a hurricane watch or warning is issued anywhere in Florida, continues during the storm, and remains active for 72 hours after the last watch/warning is lifted.
- Calendar-Year Rule (Florida Protections): Florida law mandates that the hurricane deductible applies as an annual calendar-year deductible. If your home is damaged by a second named hurricane in the same calendar year with the same carrier, you only pay the remaining balance left over from your first storm deductible.
2. Standard AOP Deductible vs. Percentage Hurricane Deductible
Understanding how standard property deductibles compare to hurricane percentage deductibles reveals the massive out-of-pocket gap:
- All Other Perils (AOP) Deductible: Applies to non-hurricane losses like kitchen pipe bursts, accidental fires, or vandalism. It is usually a fixed flat rate (e.g., $1,000 or $2,500).
- 2% Hurricane Deductible: On a $600,000 insured home, a 2% hurricane deductible equals an out-of-pocket cost of $12,000.
- 5% Hurricane Deductible: On a $500,000 insured home, a 5% hurricane deductible equals an out-of-pocket cost of $25,000.
- 10% Hurricane Deductible: Common on high-value or coastal homes insured for $1,000,000+. A 10% deductible forces a $100,000 out-of-pocket expense before policy payouts begin.
3. Essential Steps to Prepare for High Hurricane Deductibles
To prevent a percentage deductible from crippling your household finances when the next storm threatens Florida, take these key steps:
- Check Your Declarations Page: Review the dollar amount listed next to your hurricane percentage on your policy summary page to know your exact out-of-pocket exposure.
- Evaluate a Lower Deductible Option: Florida law requires insurers to offer $500, 2%, 5%, or 10% hurricane deductible options for standard residential homes. Lowering your percentage from 5% to 2% increases your annual premium slightly but drastically reduces your out-of-pocket loss during a claim.
- Build a Dedicated Emergency Storm Reserve: Keep a liquid emergency account equivalent to your hurricane deductible dollar figure so you can pay contractors quickly after a storm.
- Maintain Comprehensive Roof & Wind Mitigation Records: Upgrading your roof or adding hurricane shutters unlocks premium credits that can offset the cost of choosing a lower hurricane deductible percentage.
Why Working with an Independent Agency Matters
Navigating hurricane deductible rules, coastal wind-pool guidelines, and state regulations requires local expertise. At Walker Insurance Agency, we help Florida homeowners structure property insurance that prevents destructive financial surprises.
- Deductible Out-of-Pocket Audits: We calculate your exact dollar exposure across different coverage tiers to ensure your storm deductible aligns with your household savings.
- Carrier Re-Shopping for Better Terms: We shop across 20+ Florida-approved carriers to find policies offering manageable 2% or flat-dollar hurricane deductibles at competitive rates.
- Post-Storm Claim Support: We guide you step-by-step through the claims process, helping you track deductible credits across active storm seasons.
Frequently Asked Questions
1. Can I use my flood insurance policy to pay my homeowners hurricane deductible?
No. Flood insurance (issued through the NFIP or private flood carriers) and home insurance are entirely separate policies. Flood insurance has its own separate deductible and only covers rising water/storm surge, while home insurance covers windstorm damage.
2. What happens if my hurricane damage cost is less than my percentage deductible?
If repairs cost less than your calculated hurricane deductible (for instance, $8,000 in damage against a $15,000 deductible), the insurance company will not pay out for the claim. However, you should still report the loss to your carrier so that the $8,000 is credited toward meeting your annual calendar-year hurricane deductible.
3. Does Florida law allow a $500 fixed hurricane deductible?
Yes. Florida insurance regulations require carriers to offer a $500 flat hurricane deductible option, provided your home meets carrier underwriting guidelines and you pay the corresponding premium adjustment.
Secure Your Home and Protect Your Savings Today
Don't wait for a tropical system to threaten the Florida coast before discovering that your policy requires a $20,000+ out-of-pocket payment. Reviewing your hurricane deductible options today gives you complete financial clarity and peace of mind.
Keep your home, your family, and your savings fully protected. Contact Walker Insurance Agency today for a fast, zero-pressure Florida homeowners insurance review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Deducible por Huracán en Florida (2026): ¿Cuánto Pagas de tu Bolsillo?
¿Cómo funciona el deducible por huracán en Florida en 2026? Descubre por qué es un porcentaje y cómo puede costar más de $20,000 de tu bolsillo.
Read More →
Seguro de Casa en Florida: Límite de Joyas, Relojes y Arte (2026)
¿Tienes joyas, relojes de lujo o arte en Florida? Descubre por qué el seguro estándar limita el robo a $1,500 en 2026 y cómo cubrir el valor total.
Read More →
Florida Home Insurance: Fine Art & Jewelry Theft Limits
Have expensive jewelry or fine art in Florida? Discover why standard home insurance caps theft payouts at \$1,500 and how scheduled riders protect you.
Read More →