Florida Roof Matching Law 2026: Mismatched Tiles & Insurance Claims
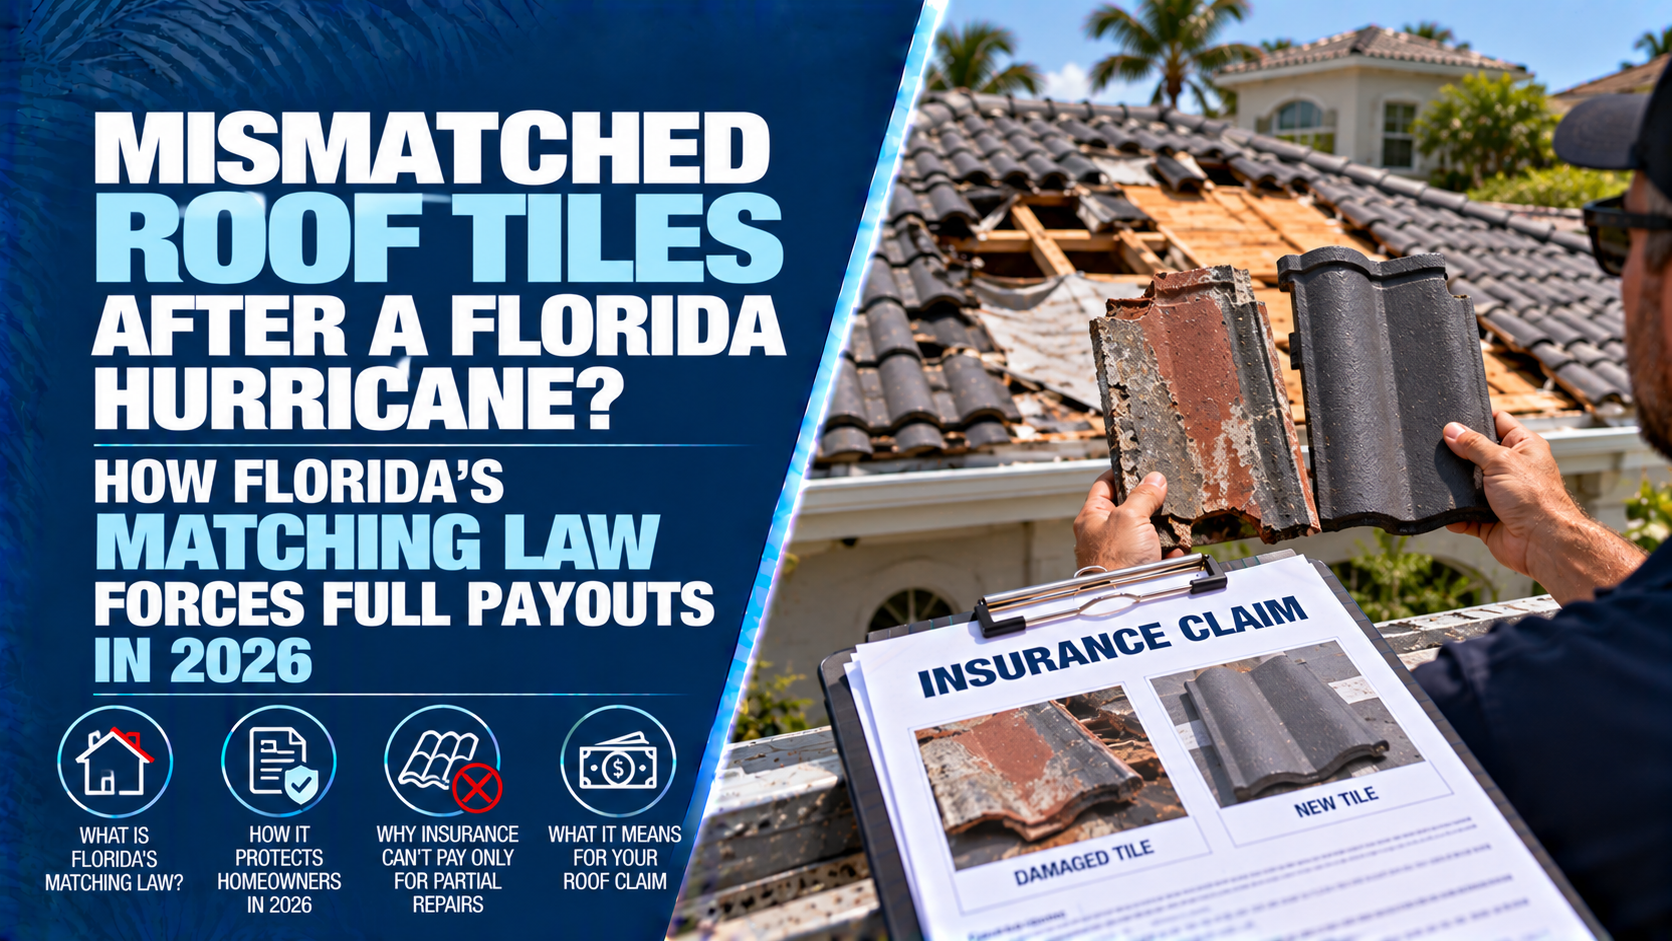
Mismatched Roof Tiles After a Florida Hurricane? How Florida's Matching Law Forces Full Payouts in 2026
The Direct Answer
Here is a major insurance protection for Florida property owners recovering from storm damage: if a hurricane damages a section of your roof and identical, matching tiles or shingles are no longer available in the market, Florida’s "Matching Law" requires your insurance company to replace the entire roof surface to maintain a uniform, consistent appearance.
Following severe tropical storms and hurricanes, insurance adjusters often attempt to settle claims by offering "spot repairs"—paying only to fix the localized patch of missing or cracked roof tiles.
However, under Florida Statute § 627.7011(3), insurance carriers cannot leave your home with a patchy, multi-colored roof that destroys curb appeal and lowers property value. If replacement materials do not match the existing roof in quality, color, size, and texture, the insurer is legally obligated to pay for a full roof replacement.
Understanding how to leverage Florida's matching statute prevents insurance carriers from underpaying your roof claim or forcing mismatched repairs onto your home.
Repairing storm damage is stressful enough without fighting your insurance company over mismatched, patchy roof tiles. Knowing your rights under state matching regulations ensures your home is restored to its pre-storm aesthetic and structural value.
1. How Florida's Matching Law Protects Property Owners
Florida insurance regulations recognize that a home’s structural integrity and aesthetic value depend heavily on architectural consistency.
- The Uniform Appearance Requirement (Florida Statute § 627.7011): The statute mandates that when a property insurance policy covers replacement costs for itemized repairs, making repairs or replacing damaged items must result in a reasonably uniform appearance within adjoining areas.
- The Discontinued Material Trigger: Roof tiles and shingles are frequently discontinued by manufacturers or alter color due to sun exposure and weathering over time. If an exact match cannot be sourced from distributors, patching is legally insufficient, triggering a full roof slope or full roof replacement.
- Coverage Across Property Features: While matching disputes most commonly involve roof tiles and shingles, Florida's matching law also applies to damaged siding, continuous flooring, matching kitchen cabinetry, and stucco finishes.
2. Spot Repair Settlement vs. Full Matching Law Replacement
Comparing a standard carrier "patch offer" against a full claim settlement under Florida's matching law highlights the difference in your financial outcome:
- Standard Carrier Spot Repair Offer: The insurance company pays only for a $3,000 patch repair over a 10x10 area of damaged tile. The replacement tiles are a visibly different shade or profile, severely degrading your home’s market value and creating potential leak points between old and new underlayment.
- Full Matching Law Settlement: Because exact matching tiles are unavailable or discontinued, the carrier must approve a full roof replacement claim (e.g., $35,000 to $60,000+), funding a brand-new roof system installed by a licensed Florida contractor.
3. Essential Steps to Prove a Matching Claim in 2026
To successfully enforce Florida's matching law and secure a full roof replacement payout, follow these four critical steps:
- Obtain an Official Supplier "NLA" (No Longer Available) Letter: Have your licensed roofing contractor attempt to source matching tiles from local supply yards. If unavailable, secure a written statement from the distributor confirming the tile is discontinued.
- Document Aesthetic Discrepancies: Take high-resolution photos comparing existing, weathered tiles against potential replacement samples. Show obvious differences in color, finish, ridge height, and interlocking structure.
- Inspect the Total Roof Underlayment: Roof tiles often cannot be removed and replaced without damaging surrounding, brittle tiles or compromising the underlying waterproof membrane. Have a contractor document if spot repairs will cause secondary damage.
- Submit a Detailed Scope of Loss to Your Adjuster: Present contractor bids explicitly citing Florida Statute § 627.7011 to prove that a partial repair violates state uniformity standards.
Why Working with an Independent Agency Matters
Navigating complex statutory rules, matching disputes, and roof replacement coverage requires localized Florida insurance expertise. At Walker Insurance Agency, we help policyholders structure comprehensive coverage that protects against costly claim disputes.
- Pre-Storm Roof & Policy Audits: We review your policy forms (HO-3, HO-6, or commercial property) to ensure you have full Replacement Cost Value (RCV) coverage rather than restrictive Actual Cash Value (ACV) roof schedules.
- Contractor & Claim Support: We guide policyholders through the documentation process, ensuring statutory matching rules and Ordinance or Law endorsements are properly applied.
- Comprehensive Property Coverage: We partner with top Florida carriers offering broad roof coverage, manageable hurricane deductibles, and strong building code upgrade limits.
Frequently Asked Questions
1. Does Florida’s matching law apply if my policy has an "Actual Cash Value" (ACV) roof endorsement?
If your policy contains a roof payment schedule or ACV endorsement that pays depreciated value for older roofs, matching protections may be restricted based on specific policy language. Having a full Replacement Cost Value (RCV) policy is essential for enforcing full matching rights.
2. Can the insurance company force me to accept used or salvaged roof tiles to match my roof?
Insurers must provide materials of "like kind and quality." While salvaged tiles are sometimes proposed by carriers, they must match in color, texture, and structural integrity without compromising building codes or manufacturer warranties.
3. What role does "Ordinance or Law" coverage play in a full roof replacement?
When Florida’s matching law forces a full roof replacement, current Florida Building Codes require the entire roof assembly—including underlayment, drip edges, and deck attachment—to meet updated wind-resistance standards. Ordinance or Law coverage pays for these mandatory code-upgraded building materials.
Protect Your Roof, Home Value, and Financial Future Today
Don't let your insurance company compromise your home's value with mismatched, patchy roof repairs after a hurricane. Enforcing your rights under Florida's matching law ensures your home receives a full, high-quality roof replacement.
Keep your home, your family, and your property value fully protected. Contact Walker Insurance Agency today for a fast, zero-pressure policy and roof coverage review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Ley de Coincidencia de Techos en Florida (2026): Tejas No Coincidentes
¿Daños en el techo tras un huracán en Florida? Descubre cómo la Ley de Coincidencia obliga a la aseguradora a cambiar todo el techo si las tejas no coinciden.
Read More →
Seguro de Casa en Florida: Cláusula de Desocupación de 60 Días
¿Casa vacía en Florida por más de 60 días tras un huracán? Descubre por qué el seguro puede denegar reclamos por robo o fugas de agua en 2026.
Read More →
Florida Home Insurance: 60-Day Vacancy Clause & Hurricanes
Living away from your Florida home or second property after a hurricane? Learn how the 60-day vacancy clause can lead to denied insurance claims.
Read More →