Florida Wind Mitigation Report Expired? 2026 Rules & Rates
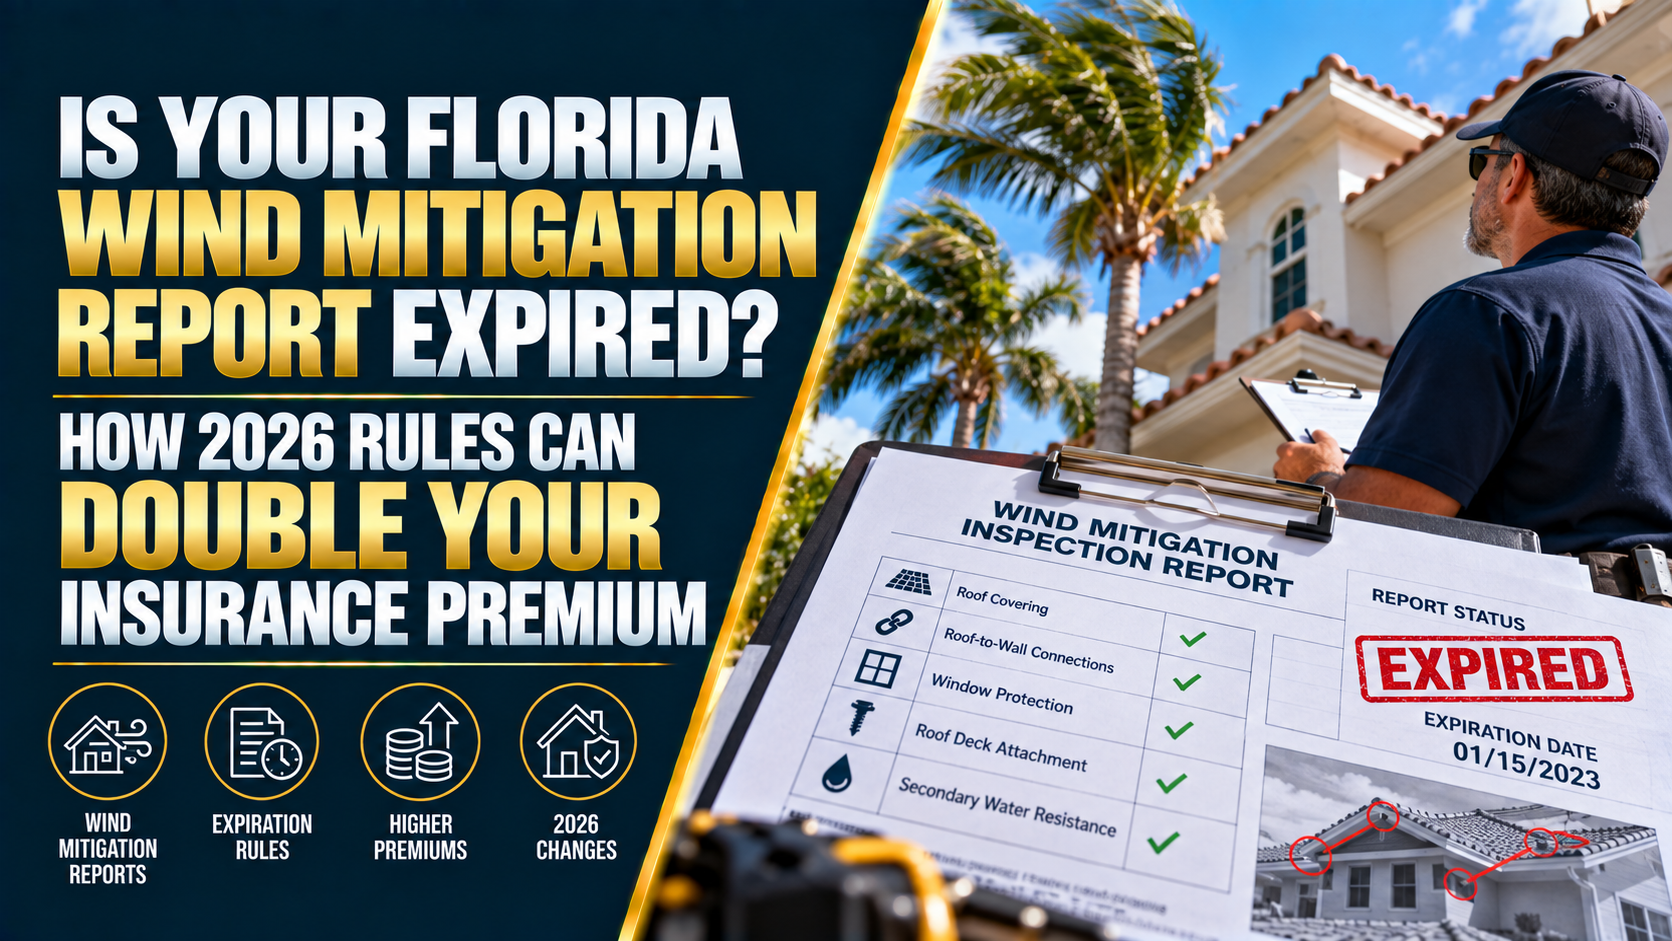
Is Your Florida Wind Mitigation Report Expired? How 2026 Rules Can Double Your Insurance Premium
The Direct Answer
Here is a major rate shock facing Florida homeowners: if your Wind Mitigation Inspection report has passed its 5-year expiration mark, your home insurance company will automatically strip away your hurricane credits, causing your annual insurance premium to spike by 50% to over 100%—effectively doubling your bill.
In Florida, wind mitigation credits provide the largest single discount on a homeowners insurance policy. These credits reward homes built or retrofitted with hurricane-resistant features, such as impact-resistant windows, reinforced roof-to-wall connections, and hip roof shapes.
Under Florida insurance guidelines, wind mitigation reports are valid for exactly 5 years. Once that 5-year window closes, carriers treat your policy as uninspected for wind resistance if a new report is not submitted.
To make matters more urgent, the Florida Office of Insurance Regulation (OIR) updated the official wind mitigation form (Form OIR-B1-1802). The revised rules require inspectors to capture strict new data points—including specific wind speed regions, roof slope measurements, synthetic material categorizations, and IBHS FORTIFIED Home designations—making up-to-date reporting essential to keep your savings intact.
Opening your annual policy renewal notice to see your premium jump from $3,500 to $7,000 without an obvious reason is shocking. In most cases, the culprit isn't a general rate hike, but a lapsed wind mitigation report that quietly erased thousands of dollars in earned discounts.
1. Why an Expired Wind Mitigation Report Doubles Your Premium
In Florida, your total homeowners insurance premium is heavily weighted toward the windstorm portion of your policy. When a report expires, insurers automatically reset your policy to default risk ratings:
- Loss of Roof-to-Wall Connection Credits: Without proof of hurricane clips, single wraps, or double wraps securing your roof truss to the wall frame, carriers charge the maximum base rate.
- Loss of Opening Protection Credits: If your window shutters or impact glass documentation expires, you lose discounts that can shave up to 35% to 45% off your wind coverage.
- Loss of Secondary Water Resistance (SWR) Discounts: Failing to verify a self-adhering sealed roof deck membrane strips away a key credit designed to prevent water intrusion if shingles blow off.
- Default Code Classification: Without a valid, active inspection report, older homes are rated as unfortified structures under pre-2001 building codes, triggering maximum premium surcharges.
2. Key Changes in the 2026 Florida Wind Mitigation Form (OIR-B1-1802)
Understanding the updated inspection criteria ensures your new report captures every available discount under current Florida rating rules:
- IBHS FORTIFIED Home Designation: The updated form officially tracks Insurance Institute for Business & Home Safety (IBHS) certifications (Roof, Silver, Gold), unlocking deeper carrier discounts.
- Design Wind-Speed Regions: Inspectors must classify properties into designated wind hazard zones (HVHZ vs. Region 1, 2, or 3 based on design wind speeds).
- Roof Pitch & Slope Recording: Inspectors must measure and document whether your primary roof pitch is steeper than 6:12 or lower pitch, influencing how wind uplift risk is calculated.
- Expanded Roof Covering Categories: Explicitly categorizes modern synthetic/composite tiles and membranes alongside traditional asphalt shingles, metal, and concrete tiles.
3. How to Renew Your Report and Reclaim Your Insurance Discounts
If your report has expired or is nearing its 5-year limit, take these proactive steps immediately to avoid premium increases:
- Check Your Current Inspection Date: Look at the date on your last OIR-B1-1802 inspection report or contact your independent insurance agent to verify your expiration deadline.
- Schedule a Re-Inspection Prior to Renewal: Hire a licensed Florida home inspector, building contractor, or professional engineer to perform a fresh wind mitigation inspection.
- Document Recent Home Improvements: Provide the inspector with proof of any recent upgrades, such as a full roof replacement, new hurricane straps, or new impact-rated windows/doors.
- Submit the Report Immediately to Your Agent: Once the inspector provides the updated form with photos, submit it to your agent so carrier system discounts can be reinstated before your renewal billing date.
Why Working with an Independent Agency Matters
A $150 to $250 wind mitigation inspection can yield $1,500 to $4,000+ in annual premium savings. At Walker Insurance Agency, we audit client policies to ensure no earned credits expire unnoticed.
- Proactive Expiration Tracking: We track wind mitigation inspection dates and alert you months before your report expires to prevent rate spikes.
- Form & Upgrade Verification: We review your new inspection report to ensure the inspector correctly marked all eligible features (like SWR and opening protection).
- Carrier Re-Shopping: Once your fresh report is logged, we re-shop your home across 20+ top-rated Florida carriers to secure the lowest possible rate available in the market.
Frequently Asked Questions
1. How long is a Florida wind mitigation inspection report valid?
A wind mitigation inspection report is valid for 5 years from the date it was completed, provided no major structural alterations or roof modifications are made during that timeframe.
2. Do I need a new wind mitigation inspection if I replace my roof in Florida?
Yes. Getting a new roof replacement qualifies you for the updated Florida Building Code (FBC) roof covering credit and Secondary Water Resistance (SWR) discount. Ordering a fresh report immediately after a re-roof maximizes your annual insurance savings.
3. Will my old wind mitigation inspection form still be accepted if it is less than 5 years old?
Yes. Valid reports completed on older versions of the form within their 5-year window remain accepted by Florida insurers until they reach their natural expiration date.
Protect Your Budget and Reclaim Your Discounts Today
Don't let an expired inspection report double your home insurance costs. Renewing your wind mitigation report is the fastest, most effective way to cut your Florida insurance bill.
Keep your home protected and your premiums as low as possible. Contact Walker Insurance Agency today for a fast, zero-pressure Florida home insurance review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro de Casa en Florida: Cláusula de Desocupación de 60 Días
¿Casa vacía en Florida por más de 60 días tras un huracán? Descubre por qué el seguro puede denegar reclamos por robo o fugas de agua en 2026.
Read More →
Florida Home Insurance: 60-Day Vacancy Clause & Hurricanes
Living away from your Florida home or second property after a hurricane? Learn how the 60-day vacancy clause can lead to denied insurance claims.
Read More →
Plazo de Prueba de Pérdida (Proof of Loss) NFIP en Florida (2026)
¿Cuál es el límite para entregar la Declaración Jurada de Pérdida (Proof of Loss) del seguro de inundación NFIP en Florida tras un huracán en 2026? Descubre los 60 días clave.
Read More →