Free Roof Scam Florida 2026: Why Signing Voids Your Insurance
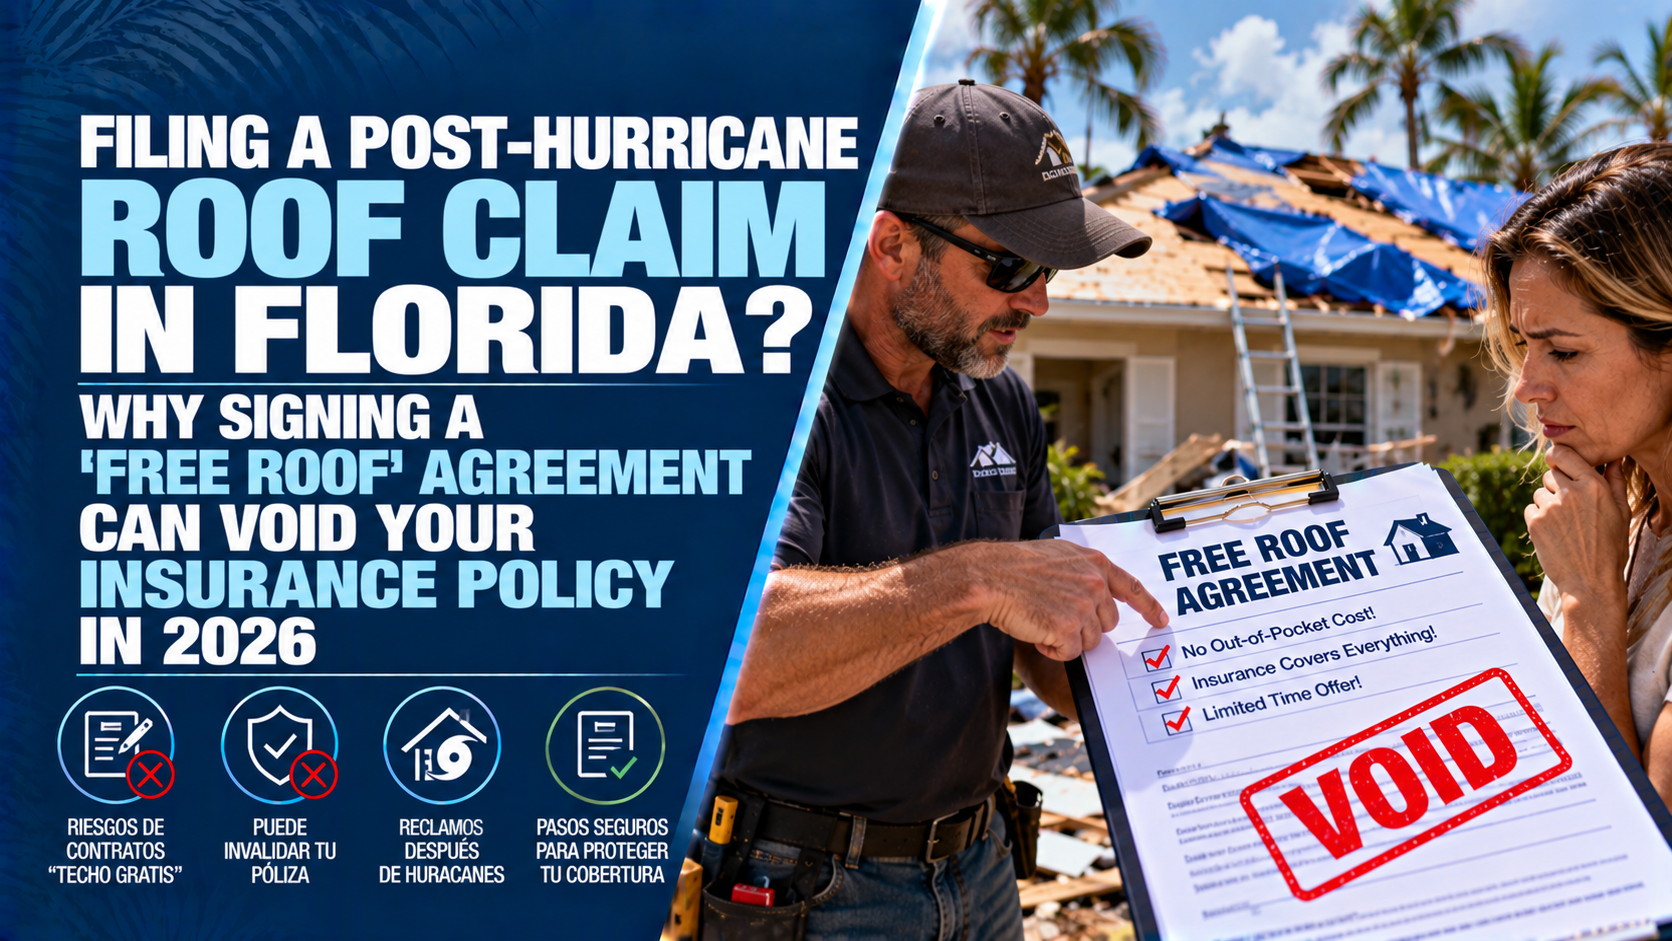
Filing a Post-Hurricane Roof Claim in Florida? Why Signing a 'Free Roof' Agreement Can Void Your Insurance Policy in 2026
The Direct Answer
Here is a critical warning for Florida homeowners navigating post-hurricane repairs: signing a "free roof" agreement, a door-to-door contractor’s contingency contract, or an illegal Assignment of Benefits (AOB) form can void your home insurance coverage, expose you to property liens, and even embroil you in a third-degree felony insurance fraud scheme.
Following severe tropical storms and hurricanes across Florida, door-to-door "storm chasers" aggressively canvas damaged neighborhoods. They promise to inspect your roof, manage your insurance claim, and deliver a brand-new roof at "zero cost to you" by waiving or absorbing your hurricane deductible.
Under Florida law, it is a third-degree felony for a contractor to pay, waive, absorb, or rebate any portion of an insurance deductible. Furthermore, assigning insurance rights to a third party or allowing a contractor to file claims on your behalf violates strict state statutes.
Cornerstone Insurance, Inc.+ 1
If your insurance carrier discovers that a contractor submitted an inflated claim, falsified damage, or agreed to waive your legal deductible, your policy can be canceled or voided for fraud, leaving you personally liable for tens of thousands of dollars in repairs and legal defense costs.
Surviving a hurricane and dealing with roof leaks is highly stressful. However, rushing into a driveway agreement with an aggressive solicitor offering a "free roof" can transform a minor storm claim into a devastating financial and legal nightmare.
1. Why "Free Roof" Promises Void Your Insurance Policy
Standard Florida homeowners insurance policies (HO-3 and HO-6) are legal contracts between you and your insurer. Signing a "free roof" pitch triggers three major contractual and statutory violations:
- Participation in Insurance Fraud (Third-Degree Felony): Florida Statute § 817.234 explicitly makes it illegal for any contractor or homeowner to knowingly waive, rebate, or offset a property insurance deductible. Submitting a claim that conceals a waived deductible constitutes felony fraud, which voids coverage under your policy's fraud and misrepresentation clauses.
FoxHaven Roofing - Banned Assignment of Benefits (AOB) Agreements: Florida law strictly prohibits policyholders from assigning post-loss insurance benefits to contractors on property insurance policies. Handing over your claim rights to a roofer makes the contract void and unenforceable by law.
Kin Insurance - Unauthorized Practice of Public Adjusting: Under Florida Statute § 489.147, contractors are legally barred from interpreting insurance policy language, negotiating claims with adjusters, or filing claims on a homeowner's behalf unless they hold a valid Public Adjuster license.
Cornerstone Insurance, Inc.
2. Standard Claim Process vs. The "Free Roof" Scam Pitch
Understanding the contrast between legitimate claim protocols and door-to-door sales tactics highlights the immense risk of signing driveway contracts:
- Legitimate Post-Storm Claim Process: You inspect the property safely, report damage directly to your insurance company, meet with an official adjuster, receive a detailed scope of loss, pay your legal hurricane deductible directly to a licensed local roofer, and maintain full control over claim payouts.
Cornerstone Insurance, Inc. - The "Free Roof" Scam Pitch: A door-to-door solicitor offers a "free inspection," claims your entire neighborhood qualifies for a new roof, promises to "eat the deductible", and demands you sign an immediate "contingency agreement" or AOB before your insurer ever evaluates the home.
Cornerstone Insurance, Inc.
3. The Dangerous Consequences of Signing a "Free Roof" Contract
When a homeowner signs a high-pressure contract with an unethical contractor, three severe outcomes frequently occur:
- Denial and Policy Cancellation: If your insurer determines that the roofer artificially manufactured roof damage, inflated repair estimates, or illegally waived your deductible, the insurer will deny the claim and cancel your policy for material misrepresentation.
- Contractor Contractor Liens & Foreclosure Risks: If the insurance company denies the contractor’s inflated bill, the roofer can file a mechanic’s lien against your home for the full balance—forcing homeowners into legal battles or potential foreclosure.
Edison Insurance - Substandard or Unfinished Work: Storm-chasing crews often perform cheap, non-compliant repairs or disappear with initial claim deposit checks before completing the roof replacement.
4. How to Safely Handle a Post-Hurricane Roof Claim
Protecting your roof, your insurance policy, and your home requires following these four steps:
- Contact Your Insurance Company First: File your storm claim directly with your insurer or independent agent before committing to any contractor.
Cornerstone Insurance, Inc. - Verify Contractor Licensing: Check that any roofer you hire possesses an active, verified license with the Florida Department of Business and Professional Regulation (DBPR) at
myfloridalicense.com.
Edison Insurance - Never Sign Over Your Claim Rights: Refuse to sign any document containing Assignment of Benefits (AOB) language or open-ended contingency clauses.
FoxHaven Roofing - Pay Your Deductible Directly: Always pay your required hurricane deductible directly to the contractor by check or card, and retain written receipts proving full payment.
JA Edwards of America
Why Working with an Independent Agency Matters
Navigating hurricane claims, statutory insurance changes, and roof replacement guidelines requires local Florida expertise. At Walker Insurance Agency, we guide homeowners through storm recovery safely and transparently.
- Direct Claim Support: We help you file storm claims directly with A-rated carriers, ensuring you retain total control over your policy benefits.
Cornerstone Insurance, Inc. - Contractor Red Flag Reviews: We help policyholders identify illegal AOB clauses, deductible waiver schemes, and scam tactics before any paperwork is signed.
Cornerstone Insurance, Inc. - Comprehensive Wind Mitigation Support: We ensure your new roof is documented correctly with a Wind Mitigation Inspection to unlock maximum annual premium discounts.
Frequently Asked Questions
1. Is it ever legal for a Florida contractor to pay or cover my insurance deductible?
No. Under Florida law, it is a third-degree felony for a contractor to pay, absorb, waive, or offer a credit/rebate for an insurance deductible. Legitimate roofer advertisements are required by state law to state that the policyholder is responsible for the deductible.
FoxHaven Roofing+ 1
2. Can I cancel a roofing contract signed during a declared state of emergency?
Yes. If you sign a roofing contract during a declared state of emergency in Florida, state law gives you the right to cancel the contract without penalty within 10 days of signing (or by sending written notice via certified mail).
FoxHaven Roofing
3. What should I do if a door-to-door roofer claims my insurance company sent them?
Insurance companies do not send door-to-door roofers to pitch door-to-door services. Always ask for credentials, refuse to sign any forms on the spot, and call your insurance company or independent agent directly to confirm adjuster schedules.
Cornerstone Insurance, Inc.
Protect Your Roof and Insurance Policy Today
Don't let a door-to-door scammer jeopardize your home insurance policy and financial stability after a hurricane. Following proper claims procedures ensures your roof is restored legally, safely, and completely.
FoxHaven Roofing
Keep your home, your family, and your insurance coverage fully protected. Contact Walker Insurance Agency today for a fast, zero-pressure policy and claim review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro Comercial en Florida: Pérdida de Ingresos sin Daños (2026)
¿Negocio cerrado por apagones o evacuación tras un huracán en Florida? Descubre por qué el seguro estándar deniega la pérdida de ingresos y cómo protegerte en 2026.
Read More →
Florida Business Interruption Insurance: Lost Income Claims (2026)
Business forced to close after a Florida hurricane despite no building damage? Learn why insurance denies lost income claims and how to secure protection.
Read More →
Cobertura ALE en Florida (2026): Gastos tras un Huracán
¿Desplazado por un huracán en Florida? Descubre qué cubre la cobertura ALE (Pérdida de Uso), reglas de recibos y límites de reembolso en 2026.
Read More →