Hiring a Florida Public Adjuster 2026: 10% Fee Cap & Rules
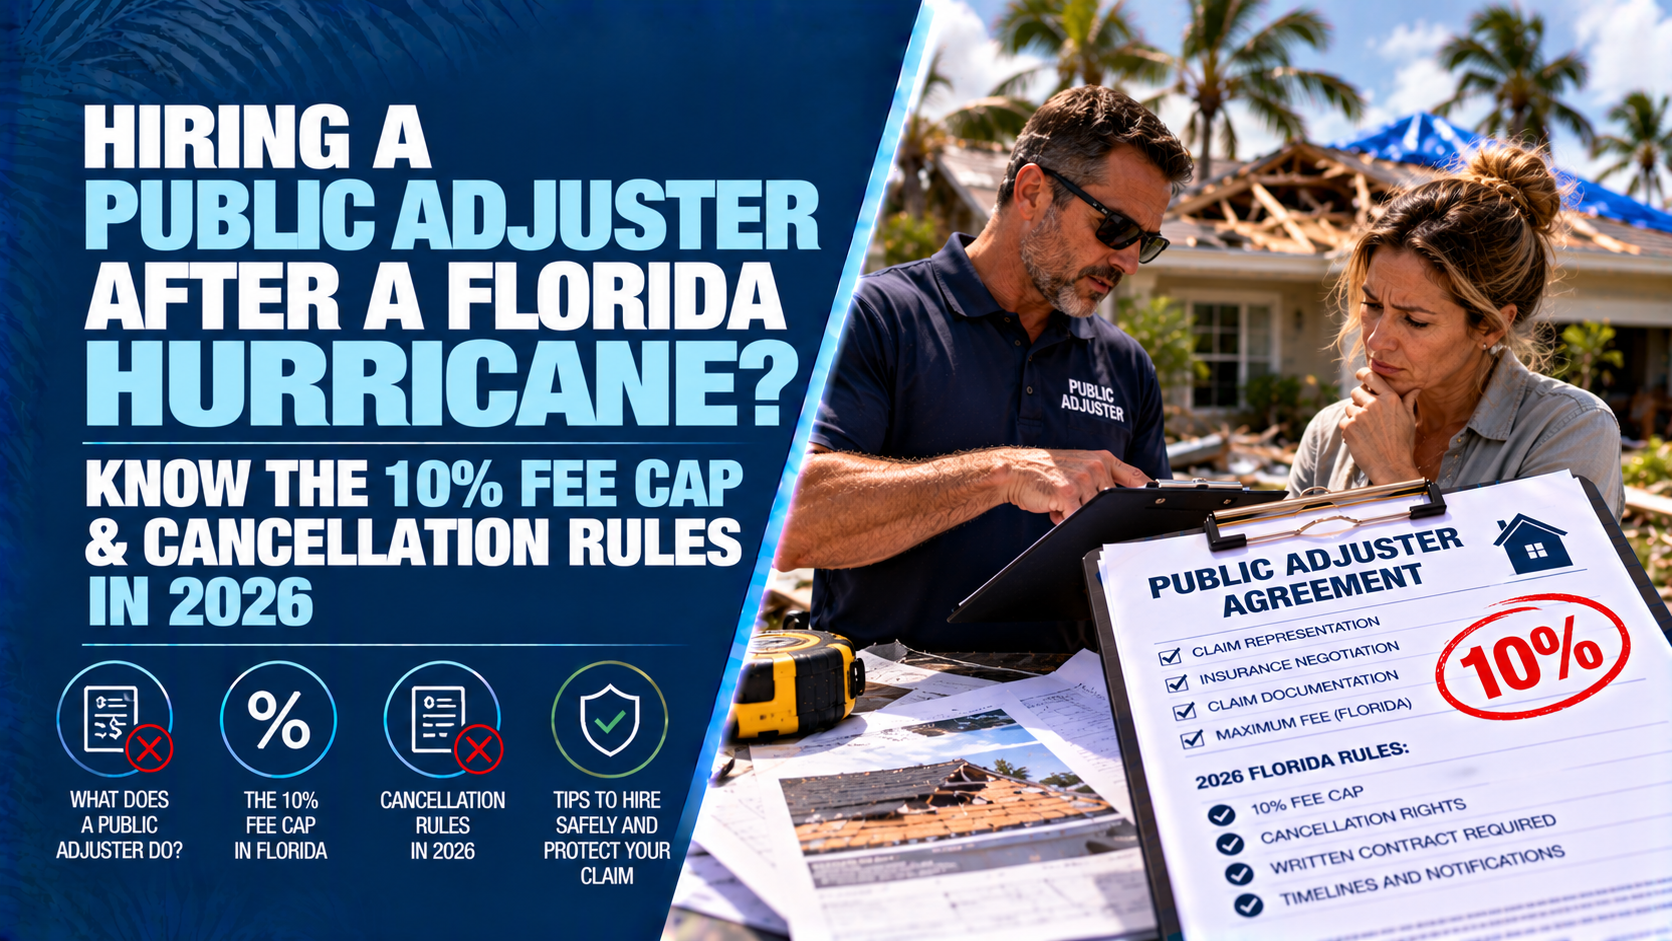
Hiring a Public Adjuster After a Florida Hurricane? Know the 10% Fee Cap & Cancellation Rules in 2026
The Direct Answer
Here is a crucial financial and legal rule for Florida homeowners navigating post-hurricane insurance claims: if you hire a public adjuster to represent your property claim following a governor-declared state of emergency, Florida law strictly caps their total fee at 10% of the insurance claim payment. Furthermore, state statutes grant policyholders a clear cancellation window with zero financial penalty.
After a major hurricane hits Florida, public adjusters often solicit homeowners offering to handle claim documentation, estimate structural losses, and negotiate with insurance companies. While a licensed public adjuster can be a valuable advocate for complex or underpaid claims, hiring one means giving up a percentage of your total claim payout.
A&H Public Adjusters Corp
Under Florida Statute § 626.854, public adjusters face rigid legal restrictions regarding fee caps, solicitation hours, and contract cancellation rights designed to protect vulnerable homeowners during disaster recovery.
Knowing these statutory boundaries ensures you retain the vast majority of your claim funds to repair your roof, rebuild your home, and restore your life after a storm.
Managing a hurricane claim is demanding. Deciding whether to hire professional representation requires a complete understanding of Florida’s fee limits, mandatory contract disclosures, and legal rights.
1. Statutory Fee Caps for Public Adjusters in Florida
Florida law establishes strict maximum fee percentages that a public adjuster can charge based on the timing and status of the claim:
- Declared State of Emergency Cap (10% Maximum): For claims arising from an event that triggers a declared state of emergency by the Governor (such as a hurricane), a public adjuster cannot charge more than 10% of the total claim payout during the first year following the loss.
Munizzi Law Firm - Standard / Non-Emergency Cap (20% Maximum): For non-emergency losses or claims filed after the initial emergency declaration period expires, fee caps revert to a maximum of 20% of the claim settlement.
Base Claims - Reopened or Supplemental Claims Cap: Public adjusters are restricted to taking their percentage only on the additional payout amounts they successfully recover above what the insurer originally paid. They cannot collect fees on funds your insurer already issued before the adjuster was retained.
2. Mandatory Contract Cancellation Rights in 2026
Florida insurance statutes recognize that policyholders may feel pressured into signing representation agreements immediately following a storm. Consequently, state law protects homeowners with clear cancellation rules:
- Emergency Declaration Cancellation Window: If a contract is signed during a declared state of emergency, the policyholder has the legal right to cancel the public adjuster contract without any fee, penalty, or obligation within 10 days of executing the contract or 30 days after the date of loss, whichever is longer.
The Florida Department of Financial Services - Written Notice Requirement: To cancel a public adjuster contract legally, the policyholder must deliver written notice of cancellation (via certified mail or verified electronic delivery) directly to the public adjuster within the statutory timeframe.
- Immediate Release of Claim: Once a cancellation notice is sent within the legal window, the public adjuster must immediately release the claim and cannot seek compensation or file a lien against future claim checks.
3. Strict Rules Governing Public Adjuster Conduct
Florida enforces consumer protection measures regulating how and when public adjusters can interact with homeowners:
- Restricted Solicitation Hours: Public adjusters are legally barred from contacting homeowners in person, by telephone, or via door-to-door solicitation on Sundays or outside the hours of 8:00 AM to 8:00 PM Monday through Saturday.
Statutes & Constitution :View Statutes : Online Sunshine - Prohibition on Financial Advances: Public adjusters cannot offer loans, financial advances, or monetary incentives (or gifts exceeding $25 in value) to sign a client.
Statutes & Constitution :View Statutes : Online Sunshine - No Legal Advice: Public adjusters are unlicensed to practice law. They cannot provide legal counsel, give advice on lawsuit filings, or handle bodily injury claims.
Statutes & Constitution :View Statutes : Online Sunshine+ 1
4. How to Properly Manage a Claim Before Hiring Representation
Protecting your claim settlement and maintaining control over your restoration involves three strategic steps:
- File Your Direct Claim with Your Carrier First: Always report hurricane damage directly to your insurance company or independent agency first. Allow your carrier’s assigned adjuster to inspect the property and issue an initial loss settlement statement.
- Review the Loss Estimate Carefully: Evaluate the insurer's initial payout against written contractor estimates to determine if there is an actual financial shortfall or coverage dispute.
- Verify License and Contract Disclosures: If you decide to hire a public adjuster to resolve a claim discrepancy, confirm their license status on the Florida Department of Financial Services website and verify that their contract explicitly lists the mandatory 10% fee cap and cancellation clauses.
Why Working with an Independent Agency Matters
Navigating storm claims, understanding statutory policyholder rights, and evaluating loss estimates requires localized guidance. At Walker Insurance Agency, we assist homeowners in managing hurricane recovery securely and transparently.
- Direct Claim Advocacy: We assist policyholders in reporting losses directly to A-rated carriers, helping track claim progress and avoiding unnecessary third-party fees.
- Supplemental Claim Support: If your initial claim payout falls short of actual repair costs, we help coordinate with your carrier to request supplemental inspections and adjustments.
- Comprehensive Coverage Guidance: We structure your homeowners and windstorm policies to ensure clear valuation terms, robust Ordinance or Law limits, and manageable deductibles before storm season arrives.
Frequently Asked Questions
1. Can a public adjuster collect a fee on my initial hurricane deductible amount?
No. Public adjuster percentage fees are calculated solely on the net settlement payments issued by the insurance carrier, exclusive of attorney fees or deductible withholdings.
Online Sunshine
2. Is a public adjuster the same as an insurance company adjuster?
No. A company adjuster or independent adjuster works directly on behalf of the insurance company to evaluate damage under the terms of your policy. A public adjuster is an independent professional hired directly by you, the policyholder, to represent your financial interest in exchange for a percentage fee.
A&H Public Adjusters Corp
3. What happens if I settle my claim directly with my insurer after signing a public adjuster contract?
If you settle a claim after signing an active public adjuster contract (and outside the statutory cancellation window), the adjuster is legally entitled to their agreed contingency percentage from the settlement funds issued by the carrier.
Protect Your Claim Settlement and Recovery Today
Don't let third-party contingency fees unnecessarily erode your hurricane insurance settlement. Understanding Florida’s public adjuster fee caps and contract cancellation rules ensures you maintain financial control throughout the recovery process.
Keep your home, your family, and your claim funds fully protected. Contact Walker Insurance Agency today for a fast, zero-pressure policy and hurricane claim consultation.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Tarifa Máxima de Tasador Público en Florida (2026): Límite del 10%
¿Vas a contratar a un tasador público tras un huracán en Florida? Conoce el límite legal del 10% en honorarios, reglas de cancelación y derechos en 2026.
Read More →
Seguro Comercial en Florida: Pérdida de Ingresos sin Daños (2026)
¿Negocio cerrado por apagones o evacuación tras un huracán en Florida? Descubre por qué el seguro estándar deniega la pérdida de ingresos y cómo protegerte en 2026.
Read More →
Florida Business Interruption Insurance: Lost Income Claims (2026)
Business forced to close after a Florida hurricane despite no building damage? Learn why insurance denies lost income claims and how to secure protection.
Read More →