Florida Sewer Line Collapse: Who Pays for Repairs in 2026?
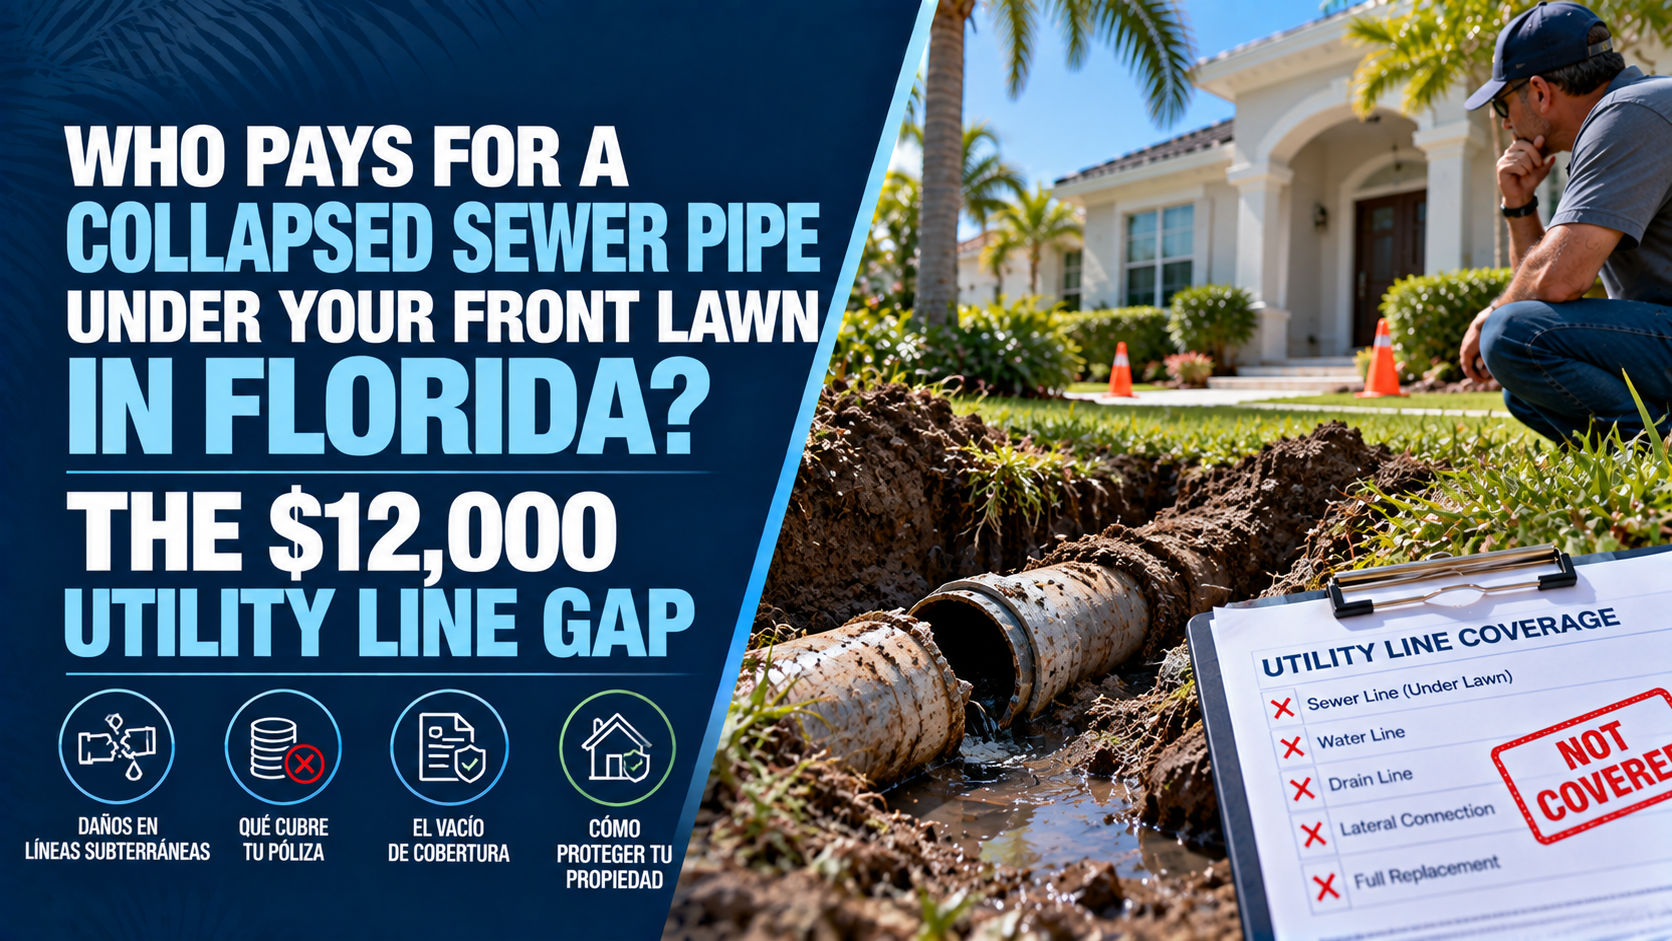
Who Pays for a Collapsed Sewer Pipe Under Your Front Lawn in Florida? The $12,000 Utility Line Gap
The Direct Answer
Here is a harsh reality facing Florida property owners: if the main sewer pipe buried under your front lawn collapses due to age, ground shifting, or tree root intrusion, you—the homeowner—are 100% financially responsible for the repairs. Your city or county municipality only maintains the main sewer line in the street, and a standard Florida homeowners insurance policy (HO-3) will completely deny the claim.
Most homeowners assume that because utility lines run underground outside their physical home, the city or local water authority manages them. In reality, property lines dictate utility ownership. You own and are legally responsible for the private lateral sewer line—the pipe extending from your home’s foundation all the way to the municipal main connection under the street.
When an aging cast-iron or clay sewer pipe collapses, excavating your lawn, tearing up driveways, replacing the line, and restoring your landscaping easily costs $5,000 to over $12,000. Without a specialized Service Line Coverage endorsement added to your insurance policy, that entire bill comes out of your pocket.
Discovering a soggy, foul-smelling patch on your front lawn alongside backing-up drains is stressful enough. Realizing that neither the city nor your primary home insurance carrier will pay a single dollar to dig up and replace the pipe creates an immediate financial crisis.
1. Why Standard Florida Home Insurance Denies Sewer Line Replacement
A standard homeowners insurance contract is designed to protect against sudden and accidental internal losses (like fire or windstorm damage). Underground utility pipes fail due to excluded perils:
- Wear, Tear, and Gradual Age Deterioration: Cast-iron pipes (common in Florida homes built before 1975) corrode from the inside out, while older Orangeburg or clay pipes collapse under soil pressure over time. Standard policies strictly exclude gradual wear.
- Tree Root Intrusion: Florida’s fast-growing trees and palms aggressively seek moisture, sending roots into pipe joints and causing total structural blockages or collapses. Root damage is categorized as a preventable maintenance issue.
- Soil Shifting and Wear: Florida's sandy soil, high water tables, and heavy rainfall cause ground movement that sags, shifts, or snaps buried utility pipes.
Important Note on Water Backup vs. Pipe Replacement: An optional Water Backup Endorsement pays to clean up raw sewage inside your home. However, it does not pay a dime to excavate or replace the collapsed pipe under your lawn.
2. Standard Policy vs. Service Line Coverage Endorsement
Understanding how standard coverage compares to an optional endorsement highlights why this small add-on is vital for Florida homeowners:
- Standard Home Insurance Policy (HO-3): Covers sudden events like a vehicle crushing an exposed line or an explosion. Does not cover pipe collapse from age, wear, rust, corrosion, tree roots, or normal excavation costs.
- Service Line Coverage Endorsement (Rider): An optional add-on that typically costs just $30 to $50 per year. It does cover underground pipe collapse, wear and tear, root invasion, excavation labor, heavy equipment backfilling, driveway repair, and lawn restoration up to $10,000 or $20,000 per occurrence.
3. What Does Service Line Coverage Protect?
When you add a Service Line endorsement to your Florida home insurance policy, it extends protection across all underground utility lines you own on your property:
- Sewer and Waste Lines: Lateral sewer pipes running to the municipal main or septic tank connection.
- Main Fresh Water Lines: Supply pipes bringing clean water from the city meter to your home.
- Underground Electrical & Power Cables: Main power lines buried beneath your lawn.
- Natural Gas & Telecom Lines: Buried gas supply pipes, fiber optic cables, and phone lines.
4. How to Close the $12,000 Utility Line Gap
Protecting your home and savings from unexpected excavation costs requires three simple steps:
- Verify Pipe Material and Age: If your Florida home was built before 1980, your sewer lines are likely cast iron or clay—making them prime candidates for deterioration or root damage.
- Audit Your Current Insurance Endorsements: Review your declarations page to confirm whether you carry Service Line Coverage or if your policy only has basic internal Water Backup protection.
- Add the Service Line Rider Immediately: Contact your agent to add the endorsement. For a few dollars a month, you protect yourself against a multi-thousand-dollar surprise.
Why Working with an Independent Agency Matters
Navigating policy riders, utility line responsibilities, and coastal property exclusions requires local expertise. At Walker Insurance Agency, we make sure Florida homeowners aren't left holding the bill for hidden underground risks.
- Comprehensive Policy Audits: We review your policy to identify missing endorsements like Service Line and Water Backup coverage before pipes fail.
- Proactive Risk Reviews: We evaluate your home's age and plumbing infrastructure to recommend coverage limits that match actual excavation costs in your area.
- Carrier Re-Shopping: We partner with top Florida insurance carriers to bundle service line riders at the lowest available annual rates.
Frequently Asked Questions
1. Does the city or county pay for a sewer line repair if it happens near the sidewalk or curb?
No. The city is only responsible for the main sewer line running under public streets. The homeowner is financially responsible for the lateral line from the home all the way to the main junction, even if it runs beneath your driveway, lawn, or sidewalk.
2. Is a sewer camera inspection covered by insurance?
Standard policies do not pay for routine plumbing maintenance or diagnostic camera scopes. However, if you have a Service Line Coverage endorsement and a covered failure occurs, the cost of diagnostic scope work and excavation is included in the claim payout.
3. How much does it cost to add Service Line Coverage to a Florida home insurance policy?
Adding a Service Line endorsement usually costs between $30 and $60 per year ($2.50 to $5 per month) and typically provides $10,000 to $12,000 in coverage with a manageable $500 deductible.
Protect Your Property and Your Savings Today
Don't wait for drains to back up or your front lawn to sink before discovering your policy doesn't cover underground utility lines. Adding Service Line coverage is one of the most affordable ways to eliminate a massive financial risk in 2026.
Keep your home, your property, and your wallet completely secure. Contact Walker Insurance Agency today for a fast, zero-pressure policy review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro Comercial en Florida: Colapso de Muelles y Seawalls (2026)
¿Tienes una marina o negocio costero en Florida? Descubre por qué el seguro comercial estándar excluye muelles, seawalls y barcos de clientes en 2026.
Read More →
Florida Marina & Coastal Insurance: Seawall and Dock Collapse
Own a marina or coastal business in Florida? Learn why standard commercial property insurance excludes seawall and dock collapse and how to protect your assets.
Read More →
¿Cubre el Seguro la Tubería Rota bajo el Jardín en Florida? (2026)
¿Se rompió la tubería principal de agua o drenaje bajo tu jardín en Florida? Descubre quién paga en 2026, los vacíos del seguro estándar y cómo cubrirlo.
Read More →