Florida Windshield Claims: Check Before Authorizing Repairs
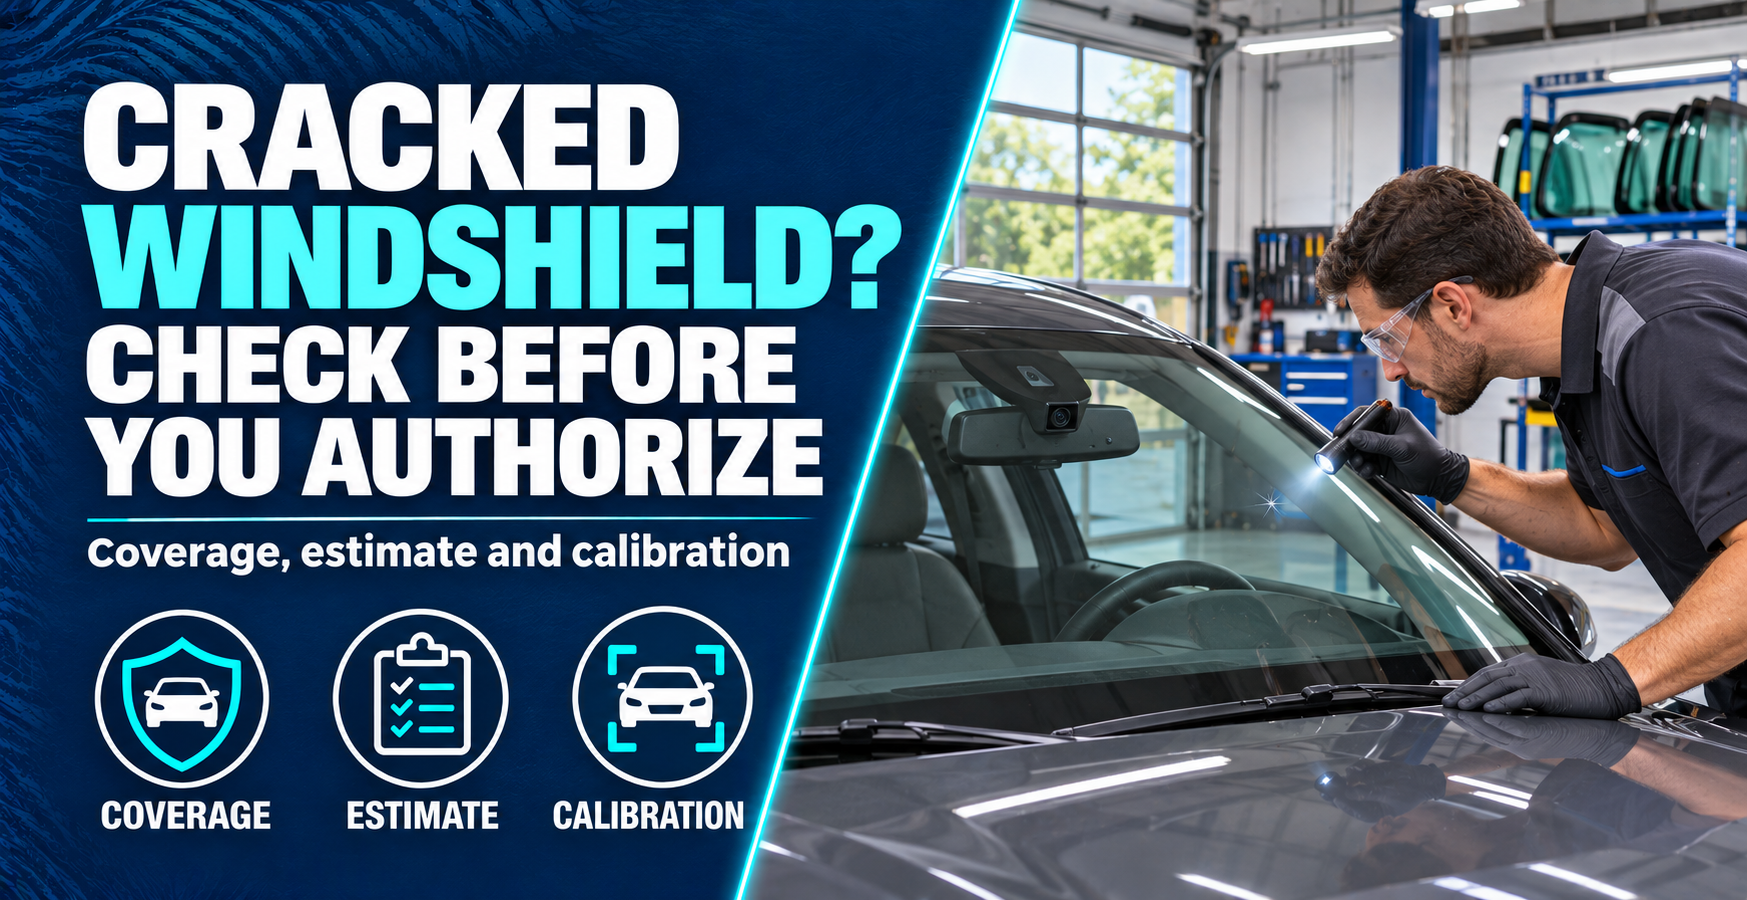
Cracked Windshield in Florida? What to Check Before Authorizing Repairs
The Direct Answer
Before approving windshield work, confirm the coverage on the damaged vehicle, open the claim through a verified insurer channel, and compare the shop’s written estimate with the insurer’s stated payment terms. Ask separately whether calibration is required and how it will be documented. A deductible waiver should not be treated as permission to sign any estimate or a promise that every billed item will be paid.
For qualifying policies delivered or issued in Florida by an authorized insurer, section 627.7288 removes the deductible for windshield damage when the policy provides comprehensive or combined additional coverage. This windshield-specific rule does not add comprehensive coverage to a policy that lacks it.1
A Small Crack Can Raise Several Different Questions
Imagine noticing a crack while leaving a Stuart parking lot. A shop offers an appointment, your policy shows a comprehensive deductible, and the vehicle has driver-assistance equipment near the mirror. You need three answers: what your insurer covers, what work the shop proposes, and what you are authorizing. The following hypothetical examples show how to separate those questions without assuming a claim outcome.
1. Confirm the Vehicle, Coverage and Claim Instructions
Start with the vehicle identification number and the policy in effect when the damage occurred. Record when and where you noticed it, take clear photos, and describe the facts accurately. If visibility or vehicle safety is in doubt, ask a qualified repair professional about safe handling before driving to an appointment.
Have the declarations page available, then ask the insurer to identify the applicable coverage and explain its claim process. Request a claim number, contact details and any inspection or estimate instructions. Save that information with your photos rather than relying on a verbal promise from someone soliciting repairs.
Scenario: Elena sees a comprehensive deductible on her declarations page and assumes she must pay it for windshield damage. Instead of canceling the appointment, she asks the insurer how the Florida windshield provision applies to her covered vehicle. This is a request for a specific coverage explanation, not a reason to assume every type of damaged glass receives identical treatment.
Useful questions include: Is this windshield damage being handled under my comprehensive coverage? What documents do you need before the work begins? What payment amount or method are you proposing? If an expense is disputed, whom should I contact before agreeing to pay it? Keep the answers in the claim file.
2. Separate Shop Choice from Agreement on the Bill
Florida section 627.7291 prohibits requiring a particular company or location for qualifying personal-lines windshield claims, including repair and calibration services. The same section permits an explanation of comprehensive benefits and applicable liability limits. Choosing a shop and confirming what the insurer will pay are separate steps.2
Request an itemized estimate showing the glass, labor, calibration if applicable, other proposed services and any amount the shop expects you to pay. Ask which items are approved, which remain under review, and how additional work will be authorized. Do not assume a shop’s statement that it handles insurance resolves every billing question.
Scenario: Marcus prefers a nearby shop, but its estimate includes an extra service absent from the insurer’s response. He sends both documents to the claims contact and asks the shop to explain that line before signing. He can then make a decision based on the proposed work and unresolved cost, rather than discovering the disagreement at pickup.
Also read the customer agreement. Look for language about personal payment responsibility and approval of added work. Ask for a copy before authorizing repairs, and keep the version you actually signed. An appointment confirmation, repair authorization and claim-payment decision should each be understandable on their own.
3. Ask About Calibration and Keep the Completion Records
Do not decide whether calibration is necessary from an advertisement or a general article. Ask the repairer to assess your specific vehicle and explain the required procedure. Florida’s insurance consumer advocate identifies written or electronic notice of required windshield calibration or recalibration as a repair-shop obligation.3
Before the appointment, ask whether the quoted work includes the required procedure, who will perform it, and what completion documentation you will receive. Ask the insurer how the proposed calibration expense will be reviewed. If a separate appointment is needed, clarify the schedule and the repairer’s instructions for using the vehicle in the meantime.
Scenario: Priya receives an estimate for windshield replacement but cannot find calibration mentioned. She requests clarification before accepting the work, rather than assuming it is unnecessary or automatically included. At pickup, she compares the final invoice with the authorized estimate and requests any applicable calibration record and operating instructions.
Be careful with documents transferring claim benefits. Section 627.7289 prohibits post-loss assignments for motor-vehicle glass work, including ADAS calibration, under policies issued or renewed in Florida by authorized insurers on or after July 1, 2023. Ask for clarification if a document appears to transfer those rights.4
Why an Independent Agency Is Useful for This Review
An independent agency can help frame the coverage questions before you make a repair decision. Walker Insurance Agency’s auto insurance page describes working with multiple Florida carriers and explaining coverage choices. That service is useful when reviewing your existing protection or considering options for a future policy; it does not mean the agency can guarantee a repair invoice or override an insurer’s claim determination.5
What to Ask Walker Insurance Agency
Bring your declarations page, vehicle details, claim number if available and the proposed estimate. Ask which questions belong with the insurer’s claims team, which policy provisions need clarification, and whether your current coverage still fits the vehicle. Use Walker’s Auto Insurance page to start a coverage review, and its Contact page for agency assistance.
Frequently Asked Questions
Does the windshield rule mean any shop invoice is automatically covered?
No. A deductible addresses one part of claim payment. Ask for the insurer’s position on the proposed scope, amount and applicable policy terms before accepting responsibility for an unresolved charge. Keep the estimate, claim correspondence and your authorization together so you can identify exactly what remains in dispute.
Should I assume calibration is included in the glass estimate?
Ask the shop to identify it explicitly if required for your vehicle. Confirm the provider, estimate, insurer review and completion record. A brief statement that the windshield will be replaced does not tell you whether all necessary work is listed or how any separate appointment will be handled.
Can Walker promise that a windshield claim will not affect my premium?
This article makes no such promise. Ask your insurer about underwriting and renewal questions for your circumstances. Walker can discuss coverage options, but a repairer’s advertisement or a general explanation should not be treated as a guaranteed future premium or a binding claim decision.
Get Clear Answers Before You Authorize the Work
A practical review leaves you with a documented claim contact, an understandable estimate and a clear plan for any required calibration. Contact Walker Insurance Agency at +1 407-977-7100 or visit 789 SW Federal Highway, Suite 201, Stuart, FL 34994. Request an auto insurance quote or coverage review through Walker’s Get a Quote page. For an existing loss, keep the insurer’s claims team involved in the repair and payment discussion.
Footnotes
-
Florida Legislature, “Comprehensive coverage; deductible not to apply to motor vehicle glass,” Florida Statutes § 627.7288 (2026). Accessed November 18, 2026. ↩
-
Florida Legislature, “Motor vehicle windshield claims and practices; steering prohibited; exceptions,” Florida Statutes § 627.7291(1), (2), (5) (2026). Accessed November 18, 2026. ↩
-
Florida Department of Financial Services, Office of the Insurance Consumer Advocate, “Property Insurance Changes,” Senate Bill 1002, Motor Vehicle Glass. Accessed November 18, 2026. ↩
-
Florida Legislature, “Assignment of post-loss motor vehicle glass benefits prohibited,” Florida Statutes § 627.7289 (2026). Accessed November 18, 2026. ↩
-
Walker Insurance Agency, “Auto Insurance,” “How We Can Help.” Accessed November 18, 2026. ↩
Related Articles
Seguro para tus cosas en almacén durante una mudanza en Florida
¿Guardarás tus cosas en un almacén durante una mudanza en Florida? Revisa límites, riesgos cubiertos, deducibles y fechas antes de mover las cajas.
Read More →
Storage Unit Insurance During a Florida Move: What to Check
Putting belongings in storage during a Florida move? Check off-premises limits, covered causes, deductibles and policy dates before moving your boxes.
Read More →
Parabrisas en Florida: revisa antes de autorizar la reparación
¿Parabrisas agrietado en Florida? Revisa cobertura, presupuesto, calibración y documentos del reclamo antes de autorizar el trabajo del taller.
Read More →