Historic Home Insurance Florida: Hand-Crafted Repairs & Materials
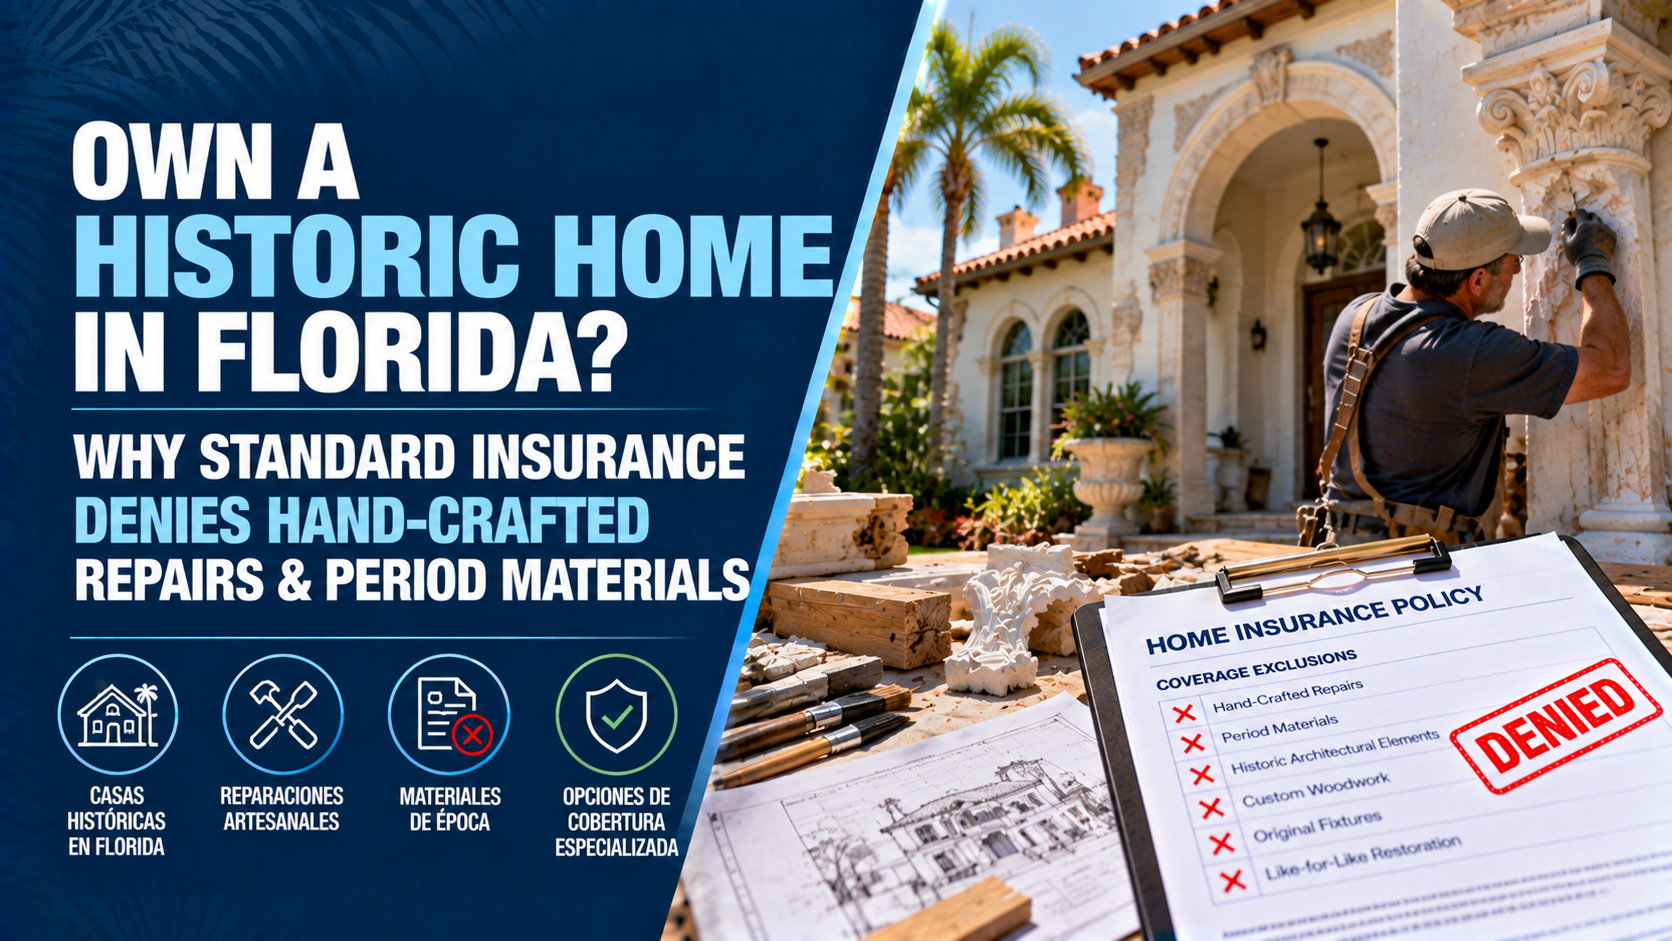
Own a Historic Home in Florida? Why Standard Insurance Denies Hand-Crafted Repairs & Period Materials
The Direct Answer
Here is a major coverage trap for owners of historic and vintage properties in Florida: if a fire, severe storm, or pipe burst damages your historic home, a standard homeowners insurance policy (HO-3) will only pay to repair it using modern, low-cost building materials. It will completely deny payouts for hand-crafted carpentry, historic masonry, custom plasterwork, or period-accurate materials.
Florida is home to rich architectural history—from Spanish Colonial revival and Mediterranean estates in St. Augustine and Palm Beach to historic Key West conch houses and mid-century modern gems in Sarasota. However, traditional home insurance contracts settle property claims on a Functional Replacement Cost basis.
Under standard policy terms, if your 100-year-old heart pine floors, hand-carved mahogany trim, or custom stained-glass windows are destroyed, the insurer is only obligated to replace them with modern off-the-shelf alternatives like drywall, composite laminate, and basic vinyl windows.
Without specialized Historic Home Coverage or an Ordinance or Law Upgrade Endorsement, restoring your home to its original historical integrity after a loss will leave you facing tens or hundreds of thousands of dollars in out-of-pocket restoration expenses.
Restoring and maintaining a historic property is a labor of love. However, assuming that a high property coverage limit on a basic home insurance policy will preserve your home’s architectural heritage during a major restoration claim can lead to devastating financial and aesthetic losses.
1. Why Standard Florida Insurance Denies Period-Accurate Restoration
Standard home insurance policies are built for modern production homes constructed with standardized lumber, drywall, and asphalt shingles. When a claim involves historic craftsmanship, three policy mechanisms prevent true architectural restoration:
- Standard Replacement Cost Definitions: Standard policies define replacement cost as using "materials of like kind and quality" commonly available today. They do not cover the specialty labor rates required for master craftsmen, historic masons, or artisan plasterers.
- Actual Cash Value (ACV) Depreciations: Older architectural elements (such as antique tile roofs or original lath-and-plaster walls) may be heavily depreciated under standard coverage, paying out pennies on the dollar based on age rather than historical replacement value.
- Building Code Exclusion (Ordinance or Law Gap): Historic homes often do not conform to modern Florida Building Code standards for wind load, electrical wiring, or plumbing. Standard policies exclude the cost of bringing undamaged parts of a historic home up to current building codes when repairs are triggered.
2. Standard Home Insurance vs. Historic & Restoration Coverage
Understanding the difference between standard property insurance and specialized historic coverage highlights why tailored protection is essential for vintage homes:
- Standard Home Insurance Policy (HO-3): Replaces historic features with modern, off-the-shelf building supplies (e.g., replacing damaged horsehair plaster with basic sheetrock, or heart pine with vinyl flooring). Excludes specialty labor and code compliance upgrades.
- Guaranteed / Extended Replacement Cost Policy: Pays to restore the dwelling even if the cost exceeds policy limits due to rising labor or specialized material costs following a disaster.
- Restoration & Period Material Endorsement: Specifically agrees to replace damaged architectural details with original, period-accurate materials and specialized craftsmanship (e.g., custom millwork, hand-pressed bricks, copper gutters, and restored plaster).
3. Critical Coverages Needed for Florida Historic Properties
To fully preserve both your real estate investment and its historic character, your policy portfolio should include four specialized protections:
- Ordinance or Law Coverage (25% to 50%+): Covers the substantial costs required by local building departments and historic preservation boards to bring your home’s electrical, plumbing, structural framing, and roof up to modern Florida building codes during a rebuild.
- Specialized Craftsman & Architectural Restoration Riders: Pays the premium labor rates charged by historical restoration contractors, master carpenters, and preservation specialists.
- Agreed Value / High-Value Asset Endorsement: Eliminates depreciation arguments by establishing a pre-agreed valuation for unique architectural elements, antique fixtures, and historic roof tiles.
- Historic Preservation Board Compliance Protection: Protects against cost overruns caused by strict architectural guidelines enforced by local historic district commissions (e.g., requiring specific wood-window profiles or historic tile sourcing).
4. How to Properly Safeguard Your Historic Florida Home
Protecting your historic property against severe financial gaps involves three clear steps:
- Order a Specialized Historic Appraisal: Work with a licensed appraiser experienced in historic architecture to document custom millwork, period materials, and actual replacement construction costs.
- Review Local Historic District Rules: Understand the guidelines set by your municipal historic preservation board (such as requirements for exterior facade repair or window restoration).
- Audit Policy Endorsements for Code and Material Coverage: Check your declarations page to ensure you have maximum Ordinance or Law coverage and dedicated historic restoration endorsements attached to your policy.
Why Working with an Independent Agency Matters
Navigating historic preservation requirements, specialty craftsman costs, and Florida Office of Insurance Regulation (OIR) guidelines demands localized expertise. At Walker Insurance Agency, we understand how to properly value and protect Florida's architectural treasures.
- Historic Property Exposure Reviews: We inspect your policy for restrictive settlement clauses, functional replacement limits, and hidden building code exclusions.
- Access to Specialty & High-Value Carriers: We partner with top Florida carriers and high-value home insurance specialists who offer dedicated historic preservation and guaranteed replacement cost endorsements.
- Tailored Code & Restoration Solutions: We customize your Ordinance or Law limits and material riders to match the exact requirements of your local historic district commission.
Frequently Asked Questions
1. Will historic preservation boards force me to rebuild using period materials if my home is destroyed?
Yes, in many designated Florida historic districts, local preservation guidelines dictate that exterior repairs or rebuilds must match the original historical style, material, and profile. If your insurance policy only pays for modern materials, you will have to pay the price difference out of pocket.
2. Is historic home insurance significantly more expensive than standard insurance in Florida?
Not necessarily. While higher coverage limits for Ordinance or Law and specialty craftsman riders slightly adjust the premium, the cost increase is minimal compared to the tens of thousands of dollars in uncovered expenses during a major restoration claim.
3. Does standard home insurance cover knob-and-tube or outdated cloth wiring in historic homes?
Many standard insurance carriers will refuse to write a policy or will exclude fire claims if a historic home has un-updated knob-and-tube electrical wiring, cast-iron plumbing, or outdated fuse boxes. Upgrading utility systems or placing your coverage with specialty carriers is often required.
Preserve Your Historic Home and Assets Today
Don't wait for a storm or sudden loss to discover that your policy treats your historic landmark like a modern tract home. Securing proper historic home and restoration coverage ensures your property's character and value remain fully protected for generations to come.
Keep your home, your architectural legacy, and your finances completely secure. Contact Walker Insurance Agency today for a fast, zero-pressure historic home insurance review.
[GET A FREE FLORIDA HISTORIC HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro para Casas Históricas en Florida: Materiales y Mano de Obra (2026)
¿Tienes una casa antigua o histórica en Florida? Descubre por qué el seguro básico deniega la restauración artesanal y cómo proteger tu patrimonio en 2026.
Read More →
Seguro Comercial en Florida: Colapso de Muelles y Seawalls (2026)
¿Tienes una marina o negocio costero en Florida? Descubre por qué el seguro comercial estándar excluye muelles, seawalls y barcos de clientes en 2026.
Read More →
Florida Marina & Coastal Insurance: Seawall and Dock Collapse
Own a marina or coastal business in Florida? Learn why standard commercial property insurance excludes seawall and dock collapse and how to protect your assets.
Read More →