Hurricane Damage to Pool Enclosure in Florida? Coverage Limits 2026
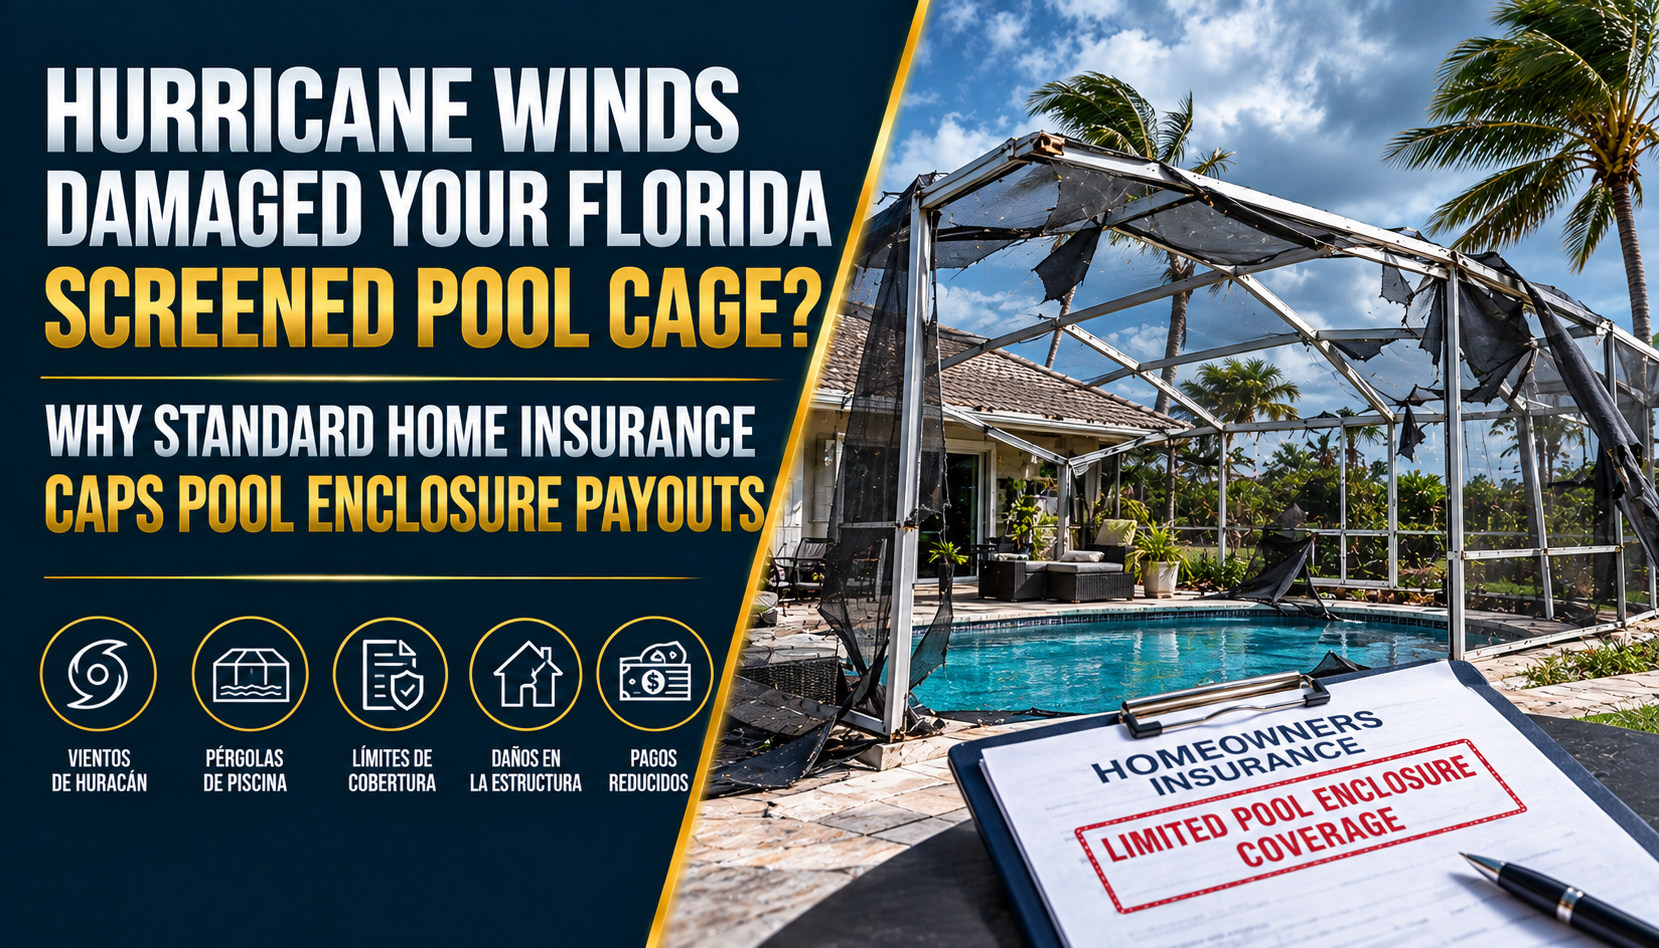
Hurricane Winds Damaged Your Florida Screened Pool Cage? Why Standard Home Insurance Caps Pool Enclosure Payouts
The Direct Answer
Here is a costly surprise facing Florida homeowners every hurricane season in 2026: if severe windstorms or hurricanes destroy your screened pool cage or patio enclosure, your standard homeowners insurance policy will either cap your payout at a low sub-limit or exclude the structure entirely.
Most Florida homeowners assume that because their pool cage or screened lanai is physically attached to the house, it is automatically insured for its full replacement value under Dwelling (Coverage A) or Other Structures (Coverage B).
In reality, major insurance carriers in Florida view aluminum screened pool enclosures as high-risk, wind-vulnerable structures.
As a result, standard property policies typically impose a strict sub-limit cap (often between $10,000 and $25,000) or exclude screened enclosures from hurricane windstorm coverage altogether.
Because replacing a modern, custom-built aluminum pool cage in Florida can easily cost $30,000 to $60,000+, relying solely on a standard policy leaves you facing massive out-of-pocket reconstruction expenses.
Relaxing under a screened pool enclosure is one of the best parts of living in Florida. However, after a Category 3 or Category 4 hurricane passes, seeing twisted aluminum beams scattered across your patio—only to learn your insurance payout covers less than half the cost to rebuild—turns storm recovery into a severe financial hardship.
1. Why Insurers Cap or Exclude Screened Pool Enclosures in Florida
To understand why insurance companies restrict pool cage coverage, it helps to look at structural risk during tropical storms and hurricanes:
- Extreme Wind Vulnerability: Screen mesh acts like a sail in high winds. When hurricane-force gusts hit a screened enclosure, intense wind pressure creates tremendous uplift forces that easily bend, snap, or detach aluminum support posts.
- High Frequency of Claims: During major hurricanes, pool cages are often among the first structures to suffer total destruction across Florida coastal and inland neighborhoods alike.
- Exclusion vs. Sub-Limits:
- Policy Exclusions: Many standard homeowners contracts explicitly state that unreinforced aluminum framing, screen mesh, and patio enclosures are completely excluded from hurricane windstorm losses.
- Sub-Limit Caps: Other policies include coverage but cap the maximum payout at a flat amount—such as $10,000 or $20,000—regardless of whether your replacement cost is $50,000.
2. The Cost Breakdown: Rebuilding a Pool Cage in 2026
Building costs for aluminum framing, heavy-duty screening, engineering fees, and hurricane-anchoring hardware in Florida have risen significantly over recent years.
Here is a realistic look at reconstruction costs vs. standard insurance payouts:
- Average Replacement Cost: Rebuilding a standard 2-car or multi-story aluminum screened pool enclosure in Florida currently ranges from $25,000 to over $60,000, depending on square footage, concrete footings, and local engineering codes.
- Standard Policy Sub-Limit: $10,000.
- Your Out-of-Pocket Gap: $15,000 to $50,000+.
Furthermore, hurricane deductibles (typically 2%, 5%, or 10% of your total Dwelling Coverage) apply to your overall storm claim. If your deductible eats up a significant portion of your claim payout, your remaining funds for non-dwelling structures like pool cages become even smaller.
3. How to Properly Insure Your Screened Pool Cage in Florida
Protecting your outdoor living area against storm destruction requires actively customizing your homeowners insurance contract before hurricane season begins:
- Add a Screen Enclosure Buy-Back Endorsement: Most Florida insurance companies offer an optional rider or endorsement that restores windstorm coverage for screened enclosures. You can select specific coverage limits, such as $25,000, $50,000, or $75,000, to match the true replacement value of your pool cage.
- Upgrade Screen Material & Wind Mitigations: High-wind screening, heavy-duty aluminum super-gutes, diagonal bracing, and reinforced concrete anchor bolts can help your enclosure withstand higher wind speeds and lower your insurance premiums.
- Audit Your Other Structures (Coverage B) Limits: Ensure your unattached or semi-attached structures have adequate limits, and confirm with your agent whether your pool cage falls under Coverage A, Coverage B, or a standalone buy-back endorsement.
Why Working with an Independent Agency Matters
Navigating policy sub-limits, buy-back endorsements, and windstorm exclusions requires clear, specialized guidance. At Walker Insurance Agency, we help Florida homeowners review their property policies to ensure every part of their home—including pools, lanais, and enclosures—is fully protected.
- Custom Buy-Back Endorsements: We evaluate the size, construction style, and replacement cost of your pool cage to secure the exact endorsement limit you need.
- Comprehensive Windstorm Audits: We examine your primary dwelling limits, hurricane deductibles, wind mitigation discounts, and flood insurance options to prevent hidden coverage gaps.
- Local Florida Expertise: Located in Stuart, Florida, our independent team advocates for you—not a single insurance provider—delivering clear, honest service to protect your outdoor lifestyle.
Frequently Asked Questions
1. Does standard homeowners insurance cover the screen mesh alone if torn by wind?
Most standard policies treat screen mesh as a wearable, high-maintenance material and exclude torn mesh from routine windstorm claims unless you carry a specific Screen Enclosure Endorsement that explicitly includes screen fabric replacement.
2. If my neighbor's falling tree destroys my pool cage during a hurricane, whose insurance pays?
In Florida, storm damage caused by falling trees or debris during a hurricane is typically submitted through your own homeowners insurance policy, regardless of where the tree originated. Your policy's pool enclosure limits or buy-back endorsements will determine your total payout.
3. What is the difference between a glass-enclosed lanai and a screened pool cage?
Enclosures with solid roofs, glass windows, and rigid structural walls built to full residential building codes are often covered as part of the primary dwelling (Coverage A). Open aluminum framing with screen mesh mesh panels, however, is subject to pool cage sub-limits and windstorm exclusions.
Protect Your Outdoor Living Space and Finances Today
Don't wait for a hurricane to reveal that your pool cage payout is capped far below the cost to rebuild. Reviewing your screened enclosure coverage today guarantees complete peace of mind when tropical storms approach.
Keep your home, patio, and savings fully protected. Contact Walker Insurance Agency today for a fast, zero-pressure Florida home insurance review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
¿Cubre el Seguro los Daños por Huracán en mi Jaula de Piscina o Terraza en Florida? (2026)
¿Un huracán destruyó la jaula de tu piscina, terraza o cobertizo en Florida? Descubre los límites de cobertura y cómo proteger tus estructuras exteriores en 2026.
Read More →
¿Cubre el Seguro HO-6 los Loss Assessments en Florida? (2026)
¿Tu condominio en Florida aprobó una tasación especial tras un huracán o fuga? Descubre cómo te protege la cobertura Loss Assessment de tu póliza HO-6 en 2026.
Read More →
Own a Condo in Florida? Loss Assessment Coverage Explained (2026)
Own a condo in Florida? Learn how a Master Policy deductible loss assessment can cost you $20,000 out of pocket and how to protect yourself in 2026.
Read More →