The 50% Rule in Florida: Storm Damage & Building Codes 2026
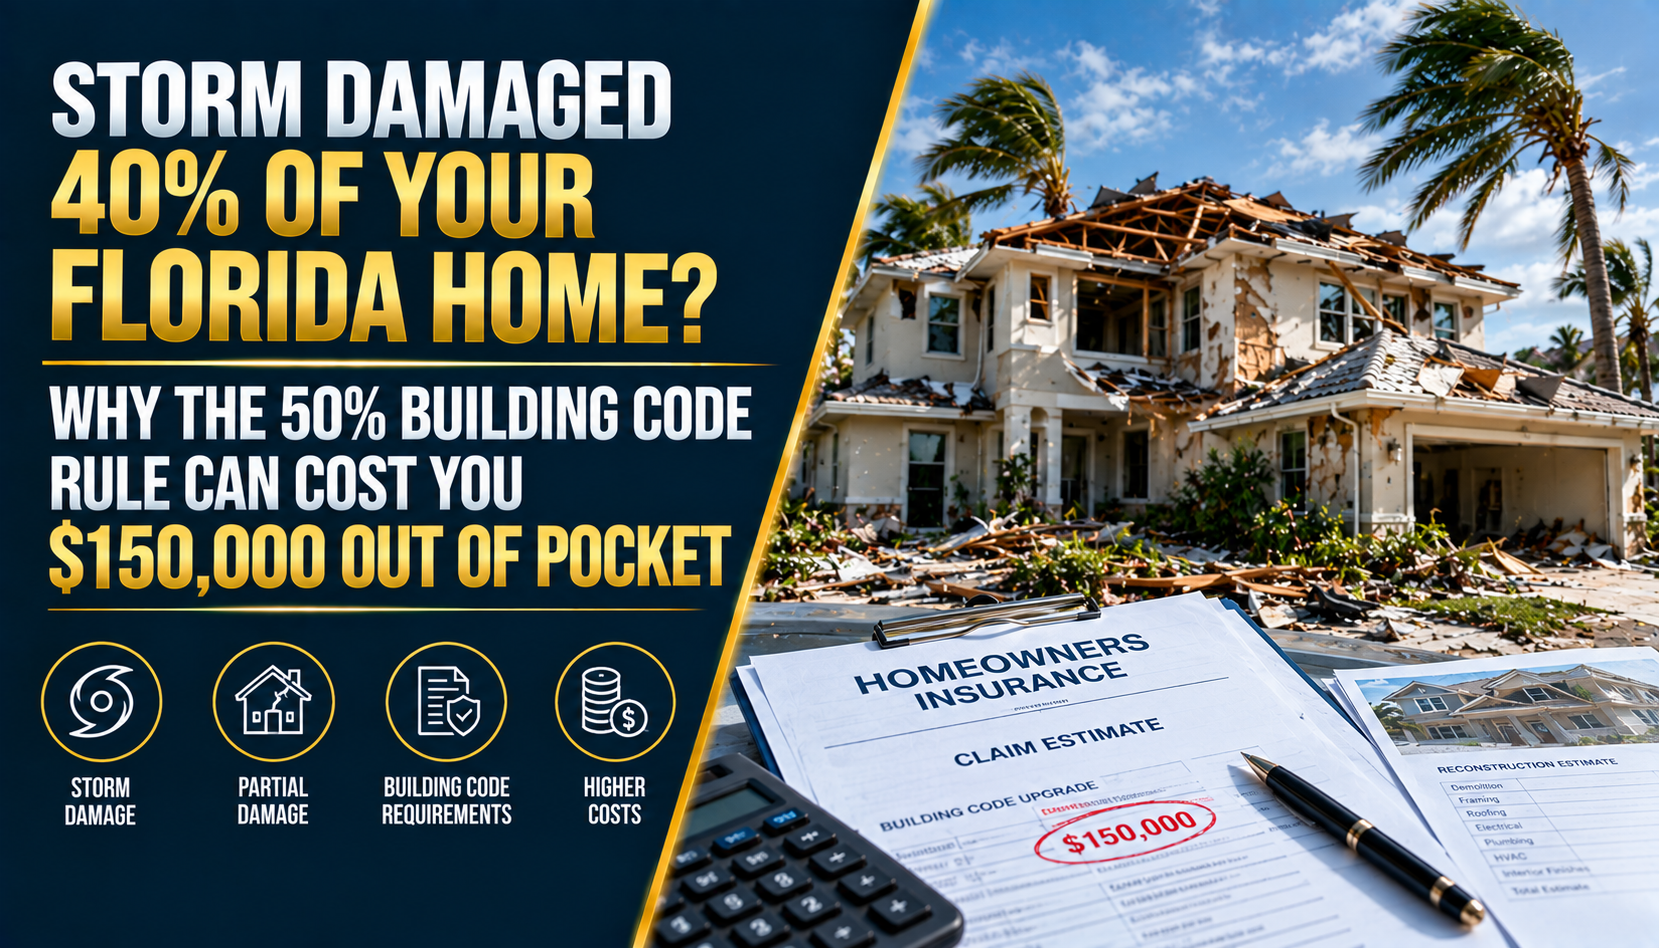
Storm Damaged 40% of Your Florida Home? Why the 50% Building Code Rule Can Cost You $150,000 Out of Pocket
The Direct Answer
Here is a massive financial trap hidden in Florida municipal building codes that catches storm-damaged homeowners off guard every hurricane season: if the cost to repair your home after a storm reaches or exceeds 50% of the building’s market value, local building codes force you to bring the entire structure up to current Florida Building Code standards—which can easily trigger $100,000 to $200,000+ in mandatory upgrades.
Most Florida property owners assume their homeowners insurance policy will cover all expenses required to rebuild their damaged home.
However, standard property insurance policies only pay to restore your dwelling back to its original pre-loss condition.
Unless you have a specific endorsement known as Law and Ordinance Coverage (Building Code Upgrades), your insurance company will refuse to pay for the expensive structural, electrical, elevation, or roof tie-down modifications required by local building inspectors—leaving you personally responsible for six-figure out-of-pocket costs.
Surviving a major hurricane in Florida is traumatic enough. But watching an insurance adjuster approve a $180,000 repair claim, only to have the local city building department reject your permits until you install a $150,000 foundation elevation or full roof truss upgrade, turns recovery into an absolute financial crisis.
1. What Is the 50% Rule (Substantial Damage Rule)?
In Florida, local municipalities enforce the Federal Emergency Management Agency (FEMA) Substantial Damage Rule (commonly known as the 50% Rule), alongside strict state building regulations:
- The Threshold: If the total cost to repair storm damage equals or exceeds 50% of the structural market value of the home (excluding land value), the building is officially classified as "substantially damaged."
- The Mandate: Once labeled substantially damaged, the homeowner cannot simply patch up the broken areas. The entire home must be brought into full compliance with current Florida Building Codes and local floodplain management ordinances.
- Common Forced Upgrades:
- Elevating the Structure: Raising the foundation or pilings above Base Flood Elevation (BFE).
- Roof & Truss Tie-Downs: Installing modern hurricane straps, heavy-duty roof decking, and impact-rated trusses.
- Impact Windows & Doors: Replacing non-compliant openings throughout the entire house.
- Electrical & Plumbing Rewiring: Complete system updates to modern safety standards.
2. Why Standard Insurance Policies Leave a $150,000 Gap
A standard Florida homeowners policy (Coverage A - Dwelling) is designed to replace or repair damaged physical materials with items of like kind and quality. It explicitly excludes the cost of mandated building code upgrades unless an endorsement is attached.
Consider this realistic scenario for an older Florida home:
- Pre-Storm Market Value of Building Structure: $300,000 (excluding land).
- 50% Substantial Damage Threshold: $150,000.
- Storm Damage Repair Cost: $160,000 (Triggering the 50% Rule).
- Cost of Mandatory Code Upgrades (Elevation & Structural Straps): $140,000.
- Standard Dwelling Coverage Payout: $160,000 (Minus your hurricane deductible).
- Your Out-of-Pocket Expense for Code Upgrades: $140,000 (Without Law & Ordinance Coverage).
Without proper coverage, the building inspector will withhold your certificate of occupancy or construction permits until those code upgrades are completed, leaving your home unlivable and uninsurable.
3. The Solution: Law and Ordinance Coverage (Ordinance or Law)
Florida law (Estatuto § 627.7011) requires insurance companies to offer Law and Ordinance Coverage on all residential property policies.
This endorsement provides an extra bucket of money—calculated as a percentage of your total Dwelling Coverage (Coverage A)—specifically set aside to pay for mandatory building code enforcement costs:
- 25% Option (Standard): Adds an extra 25% of your Dwelling Coverage amount specifically for code upgrades.
- 50% Option (Recommended for Older Homes): Adds an extra 50% of your Dwelling Coverage amount to handle major elevation or structural mandates.
If your home was built before modern Florida Building Code updates (especially homes built prior to 2002 or 1994 in South Florida), having a 50% Law and Ordinance endorsement is essential to avoiding severe out-of-pocket losses.
Why Working with an Independent Agency Matters
Navigating municipal building codes, substantial damage assessments, and policy endorsements requires expert guidance. At Walker Insurance Agency, we audit Florida property policies to ensure homeowners aren't exposed to devastating code-compliance gaps.
- Law & Ordinance Policy Audits: We evaluate your home’s construction year, elevation level, and estimated structural replacement value to recommend the right Law and Ordinance percentage.
- Comprehensive Windstorm Coverage: We structure your primary dwelling limits, hurricane deductibles, and secondary structure endorsements to match real-world rebuilding costs.
- Dedicated Local Advocacy: Located in Stuart, Florida, our independent team advocates directly for you—delivering clear, honest service to protect your property and your savings.
Frequently Asked Questions
1. Does my county or city determine the structural market value for the 50% Rule?
Yes. Local building departments typically use the structural value assessed by the county property appraiser (excluding land value) or require a certified appraisal from a licensed property appraiser to establish the official building value.
2. Is Law and Ordinance coverage automatically included in my Florida policy?
Florida law requires insurers to include 25% Law and Ordinance coverage by default unless the homeowner explicitly signs a written rejection form selecting 0%. However, 25% is often insufficient for older homes facing total elevation or structural compliance mandates.
3. Can I use my standard Dwelling (Coverage A) limit to pay for code upgrades?
Generally, no. Your standard Dwelling coverage will pay for the actual physical repairs up to its limit. Code enforcement upgrades require separate funds provided under the Law and Ordinance endorsement.
Protect Your Home from Hidden Rebuilding Costs Today
Don't wait for a major hurricane to discover that local building codes will force a six-figure upgrade out of your own pocket. Reviewing your Law and Ordinance limits today guarantees complete protection when restoring your home.
Keep your dwelling, your financial stability, and your peace of mind fully secured. Contact Walker Insurance Agency today for a fast, zero-pressure Florida home insurance review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Cobertura de Ley y Ordenanza en Florida (Ordinance or Law) 2026
¿Cubre el seguro de casa en Florida las actualizaciones obligatorias del código de construcción? Descubre cómo la Regla del 50% te afecta en 2026.
Read More →
¿Cuánto Tiempo Tengo para Reclamar Daños por Tormenta en Florida? (2026)
¿Tuviste daños por agua o tormenta en Florida? Conoce la regla estricta de 1 año para reportar tu reclamo al seguro en 2026 y evita que sea denegado.
Read More →
Forced to Evacuate in Florida? Additional Living Expenses 2026
Forced to evacuate during a Florida storm? Learn why insurance won't pay your hotel bills without mandatory evacuation orders & ALE coverage triggers.
Read More →