Filed a Property Claim in Florida? AOB Bans & Managed Repair 2026
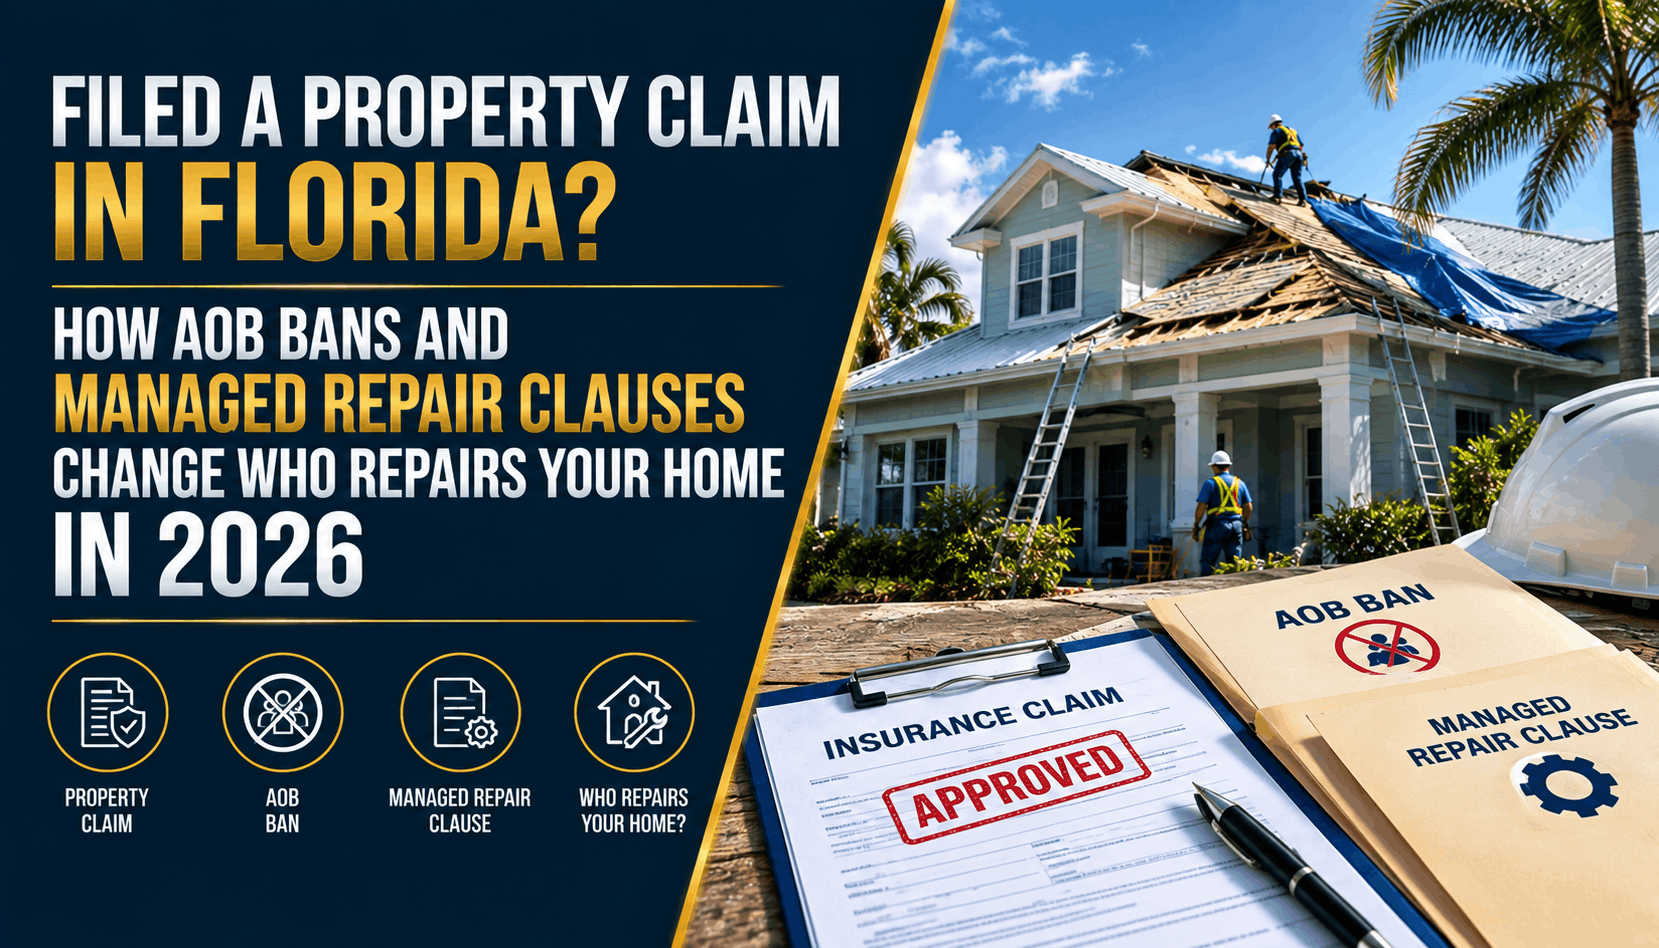
Filed a Property Claim in Florida? How AOB Bans and Managed Repair Clauses Change Who Repairs Your Home in 2026
The Direct Answer
Here is a critical shift in how Florida property insurance claims operate in 2026: if your home suffers storm, water, or roof damage, you can no longer sign over your insurance rights to a third-party contractor, and your insurer may have the contractual right to select who performs the repairs.
Recent major legislative reforms in Florida officially eliminated Assignment of Benefits (AOB) contracts. Contractors can no longer directly take over your insurance claim or sue your insurance company on your behalf.
At the same time, insurance carriers are heavily incorporating Managed Repair Network clauses into policy contracts.
Under these clauses, if you opt into or fail to reject a managed repair program, your insurance company controls the contractor selection, scope of work, and repair timeline—effectively determining who rebuilds your home after a loss.
Filing a property damage claim after a Florida hurricane, roof leak, or severe weather event used to mean hiring your own preferred contractor, signing an agreement, and letting them negotiate directly with your insurer. In 2026, new insurance laws and strict policy contract clauses mean homeowners must take a much more active, hands-on role in managing their own claim and repairs.
1. The End of Assignment of Benefits (AOB) in Florida
For years, contractors in Florida frequently asked homeowners to sign an Assignment of Benefits (AOB) contract before starting emergency mitigation or repairs (such as water extraction or tarping a damaged roof).
- What an AOB Did: An AOB legally transferred all post-loss insurance rights, claim payments, and legal standing from the homeowner to the repair vendor or contractor.
- Why AOB Was Banned: Florida lawmakers passed sweeping reforms (including Senate Bill 2-A) prohibiting AOB agreements for property insurance policies to curb excessive litigation and inflated repair invoices.
- What It Means for You Today: Contractors can no longer bill your insurance company directly or file a lawsuit against your insurer in your name. You remain solely responsible for managing your claim, communicating with your insurance adjuster, and receiving benefit payouts directly.
2. Understanding "Managed Repair" Clauses in 2026 Insurance Policies
While AOB bans prevent contractors from taking over claims, insurance carriers have increasingly implemented Managed Repair Network Endorsements to control repair costs.
- How Managed Repair Works: Rather than cutting you a check for covered damages so you can hire a private contractor, the insurance company uses its own preferred network of licensed repair contractors to perform the work.
- The Option vs. Requirement: Some policies offer a discount on your annual premium if you agree to a mandatory Managed Repair endorsement. Other policies include a "Right to Repair" clause that gives the insurer the option to assume control of repairs instead of paying a cash settlement.
- Benefits and Drawbacks:
- Pros: Network repairs are typically backed by a warranty (often 3 to 5 years) provided by the insurer, and you avoid the stress of finding contractors after a widespread storm.
- Cons: You lose the freedom to choose your own local contractor, and disputes regarding material quality or repair timelines must be handled through the insurer's internal network management.
3. Step-by-Step: How to Handle a Property Claim Under 2026 Rules
If your home suffers water, wind, or structural damage, following the correct procedural steps ensures your claim proceeds smoothly without violating contract terms:
- Notify Your Insurer First: Report the damage to your insurance company immediately. Florida law requires prompt notice of loss (typically within 1 year for hurricane claims).
- Perform Emergency Mitigation: You have a legal duty to prevent further damage (e.g., placing a tarp over a leaking roof or shutting off the main water valve). Keep receipts for all emergency expenses.
- Do NOT Sign "Assignment" Contracts: Never sign any agreement with a contractor that contains phrases like "I transfer all rights, benefits, and proceeds of my insurance policy." Sign contracts that specify direct work authorization and estimate pricing only.
- Review Your Policy's Managed Repair Language: Check your policy declarations page or consult your agent before hiring an independent contractor to confirm whether your carrier exercises a Right to Repair option.
Why Working with an Independent Agency Matters
Navigating post-loss claim requirements, managed repair clauses, and Florida policy terms can be confusing during a high-stress emergency. At Walker Insurance Agency, we help Florida homeowners structure their policies correctly before disaster strikes and guide them through the claim process.
- Policy Endorsement Clarity: We review your home insurance contract to explain whether you have Managed Repair clauses, mandatory deductibles, or contractor selection flexibility.
- Local Claim Guidance: Located in Stuart, Florida, our team provides step-by-step assistance when you need to report a claim, helping you avoid common filing errors that delay payout.
- Independent Advocacy: Because we work for you—not a single insurance company—we advocate for your best interests to keep your property fully protected.
Frequently Asked Questions
1. Can I still hire my own contractor to repair my home in Florida?
Yes, provided your policy does not contain a mandatory Managed Repair clause or your insurer waives its Right to Repair option. You hire the licensed contractor, receive claim payments from your insurer, and pay your contractor directly.
2. What happens if a contractor asks me to sign an AOB contract in 2026?
Under Florida law, property insurance AOB contracts executed after recent legislative reform dates are invalid and unenforceable. Refuse to sign any assignment agreement and request a standard work authorization contract instead.
3. What if I am unhappy with the repairs done by an insurer's Managed Repair contractor?
Most Managed Repair endorsements include a workmanship warranty provided by the insurance company. If repairs are unsatisfactory or delayed, you can submit a formal dispute directly to your insurer under the terms of the network warranty agreement.
Protect Your Home and Your Policy Rights Today
Don't wait until storm damage occurs to find out who will rebuild your home and how your claim will be handled. Reviewing your policy terms and repair endorsements today gives you complete clarity when filing a claim.
Keep your property, family, and insurance rights protected. Contact Walker Insurance Agency today for a fast, zero-pressure Florida home insurance policy review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance rules and protect your property.
Related Articles
Seguro de Casa en Florida: Cobertura de Jaula de Alberca (2026)
¿Se destruyó tu jaula de alberca (pool cage) o mosquitero tras un huracán en Florida? Descubre por qué el seguro básico no lo cubre y cómo solucionarlo en 2026.
Read More →
Florida Hurricane Pool Cage Damage: Screen Enclosure Claims
Collapsed pool cage or damaged patio screen after a Florida hurricane? Learn why standard home insurance denies screen enclosure claims and how to buy coverage.
Read More →
Ley de Coincidencia de Techos en Florida (2026): Tejas No Coincidentes
¿Daños en el techo tras un huracán en Florida? Descubre cómo la Ley de Coincidencia obliga a la aseguradora a cambiar todo el techo si las tejas no coinciden.
Read More →