Florida Hurricane Pool Cage Damage: Screen Enclosure Claims
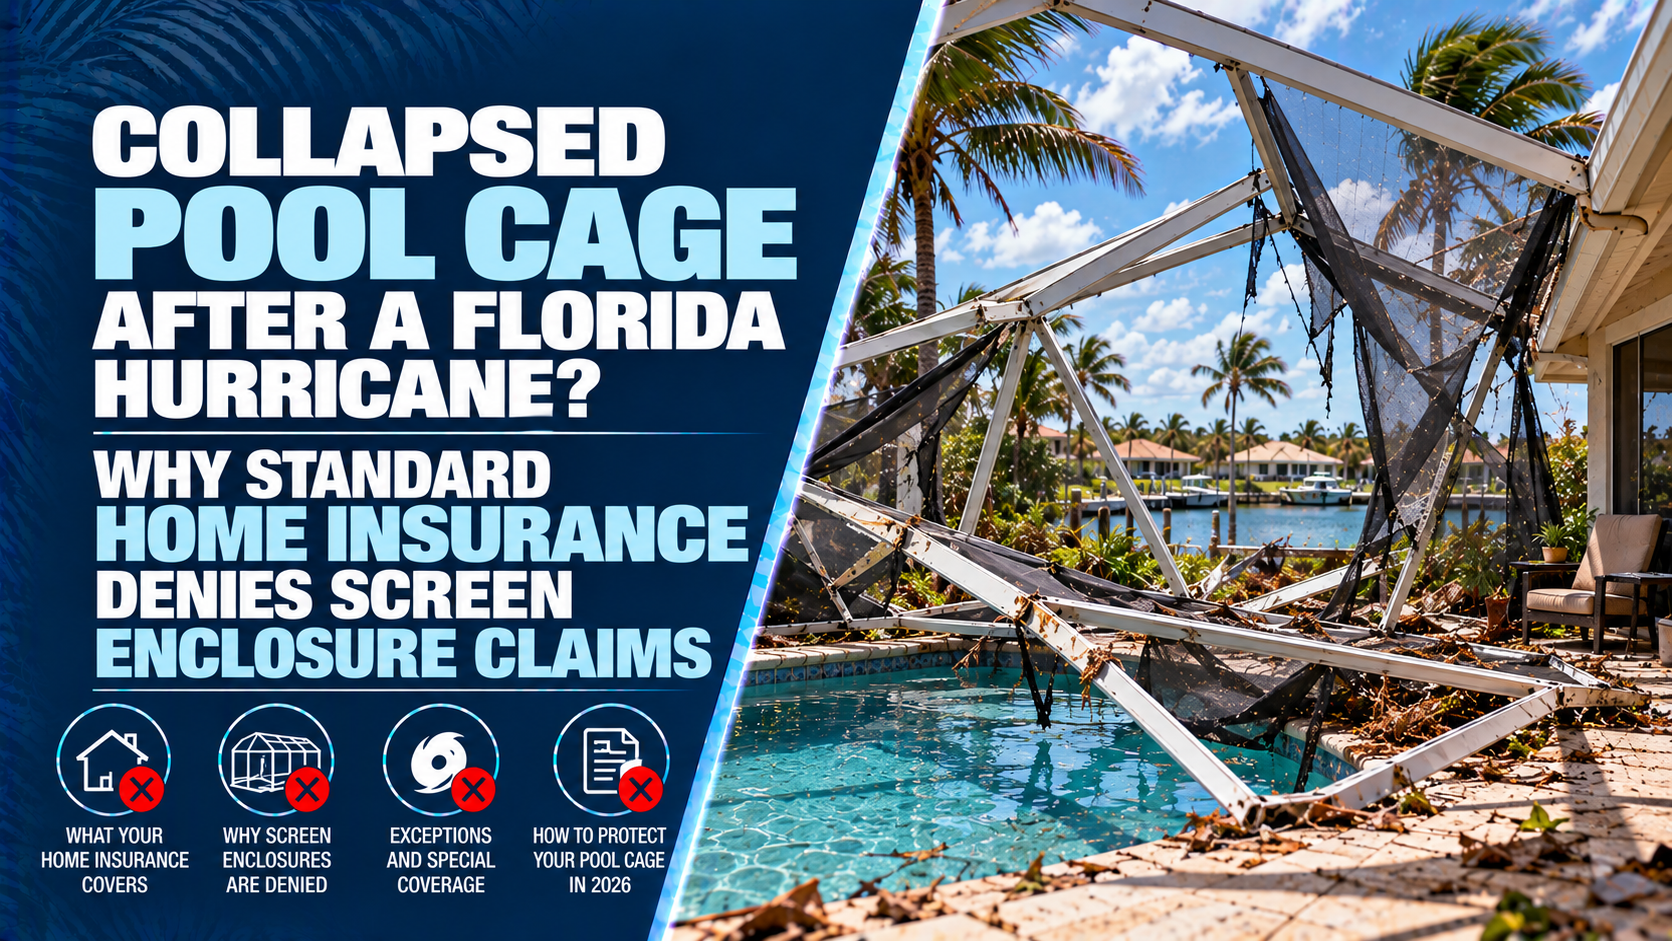
Collapsed Pool Cage After a Florida Hurricane? Why Standard Home Insurance Denies Screen Enclosure Claims
The Direct Answer
Here is a major coverage surprise facing Florida homeowners after a severe tropical storm or hurricane: standard Florida homeowners insurance policies (HO-3 and HO-6) explicitly exclude screen enclosures, aluminum pool cages, patio framing, and carports from hurricane windstorm coverage.
When high-velocity hurricane winds collapse an aluminum pool frame, rip screen mesh to shreds, or tear away patio framing, homeowners are often shocked to learn that their primary property policy will pay $0 toward repairing or rebuilding the structure unless a specific, optional policy endorsement was purchased prior to the storm.
Because screen enclosures and pool cages are highly vulnerable to hurricane wind damage, insurance carriers removed them from standard Coverage A (Dwelling) and Coverage B (Other Structures) protections years ago.
Understanding how screen enclosures are classified—and how to add a Hurricane Screen Enclosure Endorsement to your policy—is essential to avoiding tens of thousands of dollars in out-of-pocket repair costs following a major storm.
A collapsed pool cage not only ruins your outdoor living space, but sharp, twisted aluminum framing falling into your pool can tear vinyl liners, destroy pool pumps, and create severe liability hazards. Knowing how your insurance handles screened structures ensures your backyard investment remains fully protected.
1. Why Standard Policies Exclude Pool Cages and Screen Enclosures
Standard homeowners policies written by Florida carriers follow insurance forms that exclude aluminum-framed screened structures from primary windstorm coverage due to their high risk profile:
- The Windstorm Exclusion Provision: Standard policy language specifically excludes loss or damage caused by windstorm or hail to screen enclosures, aluminum framed carports, awnings, and pool cages unless additional premium is paid.
- Classification Outside Standard "Other Structures": While unattached sheds or detached garages are typically covered up to 10% of Coverage A under Coverage B (Other Structures), aluminum screen enclosures attached to the main dwelling are explicitly carved out and excluded from wind coverage.
- High Replacement & Cleanup Costs: Rebuilding a custom aluminum pool cage in Florida routinely costs between $15,000 and $45,000+, with debris removal alone costing thousands. Without an explicit endorsement, the entire financial burden falls on the homeowner.
2. Standard Policy vs. Screen Enclosure Endorsement Coverage
Comparing a standard home insurance policy against a policy with a screen enclosure endorsement illustrates the severe financial gap after a hurricane:
- Standard Homeowners Policy (No Endorsement): Pays $0 for wind damage to pool cages, screen mesh, aluminum framing, or patio enclosures. May pay only for damage caused to the primary dwelling structure if the collapsing pool frame punctures the main roof or impact glass.
- Policy with Hurricane Screen Enclosure Endorsement: Provides dedicated schedule limits (typically $10,000 to $50,000+) specifically designated to repair or rebuild aluminum framing, replace screen mesh, and fund debris removal following a covered hurricane.
3. Essential Coverage Details & Protection Options for 2026
To properly protect an outdoor screen structure or pool cage against Florida’s volatile hurricane seasons, implement these strategic policy options:
- Purchase a Specific Hurricane Screen Enclosure Buy-Back Endorsement: Work with your independent insurance agent to select a specific limit ($10k, $25k, or $50k) tailored to the true replacement value of your aluminum structure.
- Review Deductible Structures: Screen enclosure endorsements often feature their own specific hurricane deductible (e.g., a flat $500–$1,500 deductible or a percentage tied to the enclosure limit).
- Ensure Debris Removal Is Included: Confirm that your endorsement covers the costly process of extracting twisted aluminum frames and broken glass out of your swimming pool and off your patio deck.
- Upgrade Frame Engineering and Anchoring: Modern Florida Building Codes require upgraded aluminum gauge thickness, stainless steel fasteners, and reinforced footings. Ensure your policy includes Ordinance or Law coverage to pay for code-mandated structural upgrades during rebuilding.
4. Steps to Take After a Pool Cage Collapses in a Hurricane
If your pool cage or patio screen enclosure collapses during a storm, follow these four immediate steps to manage your claim safely:
- Prevent Secondary Pool & Property Damage: Safely remove loose screen mesh and debris from pool skimmers and filters to prevent pump burnouts or chemical contamination.
- Photograph Frame Anchors and Damage: Take high-resolution photos and video of the collapsed aluminum framing, torn screens, bent support posts, and concrete footings before clearing debris.
- Secure Independent Contractor Bids: Obtain detailed line-item replacement estimates from licensed Florida specialty aluminum and screen contractors.
- Verify Your Policy Endorsements Before Filing: Check your policy declarations page to confirm your specific Screen Enclosure Endorsement limit before submitting your loss report to your adjuster.
Why Working with an Independent Agency Matters
Customizing hurricane coverage for unique Florida home features like pool cages, sunrooms, and lanais requires dedicated local expertise. At Walker Insurance Agency, we help Florida homeowners build comprehensive property portfolios that eliminate hidden policy exclusions.
- Coverage Exclusion Audits: We review your policy declarations page to uncover hidden screen enclosure exclusions before storm season begins.
- Custom Buy-Back Endorsements: We partner with Florida’s top-rated property carriers to secure adequate Screen Enclosure and Carport buy-back limits at competitive rates.
- Comprehensive Outdoor Protection: We align your home, windstorm, flood, and screened structure coverages into a seamless risk management plan.
Frequently Asked Questions
1. Does standard home insurance pay to drain and clean my pool if a screen enclosure collapses into it?
If you have a Hurricane Screen Enclosure Endorsement, necessary pool cleanup and debris removal caused by the collapsing structure are typically covered up to policy limits. Without the endorsement, carriers generally deny pool cleanup claims stemming from excluded screen frame failures.
2. Can I buy insurance that covers only the aluminum frame and not the screen mesh?
Some specialty carriers offer option tiers that cover only the structural aluminum framing while excluding simple screen mesh tears. However, comprehensive screen enclosure endorsements covering both frame and mesh provide the best financial protection.
3. How much does a Screen Enclosure Endorsement cost in Florida?
Endorsement costs vary based on the selected coverage limit, county wind risk, and structure size. Typically, adding a $10,000 to $25,000 Screen Enclosure Endorsement adds approximately $150 to $450 annually to your homeowners policy.
Protect Your Pool Cage and Outdoor Living Space Today
Don't wait for a hurricane to collapse your pool cage before discovering that standard home insurance excludes screen enclosures. Adding the right endorsement ensures your backyard oasis is fully restored after a storm.
Keep your home, your pool cage, and your outdoor living space completely protected. Contact Walker Insurance Agency today for a fast, zero-pressure policy and screen enclosure review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navi
Related Articles
Seguro de Casa en Florida: Cobertura de Jaula de Alberca (2026)
¿Se destruyó tu jaula de alberca (pool cage) o mosquitero tras un huracán en Florida? Descubre por qué el seguro básico no lo cubre y cómo solucionarlo en 2026.
Read More →
Ley de Coincidencia de Techos en Florida (2026): Tejas No Coincidentes
¿Daños en el techo tras un huracán en Florida? Descubre cómo la Ley de Coincidencia obliga a la aseguradora a cambiar todo el techo si las tejas no coinciden.
Read More →
Florida Roof Matching Law 2026: Mismatched Tiles & Insurance Claims
Had roof damage after a Florida hurricane? Learn how Florida's matching law forces insurance companies to replace your entire roof if matching tiles aren't available.
Read More →