Florida Historic Home Insurance: Coverage for Period Repairs
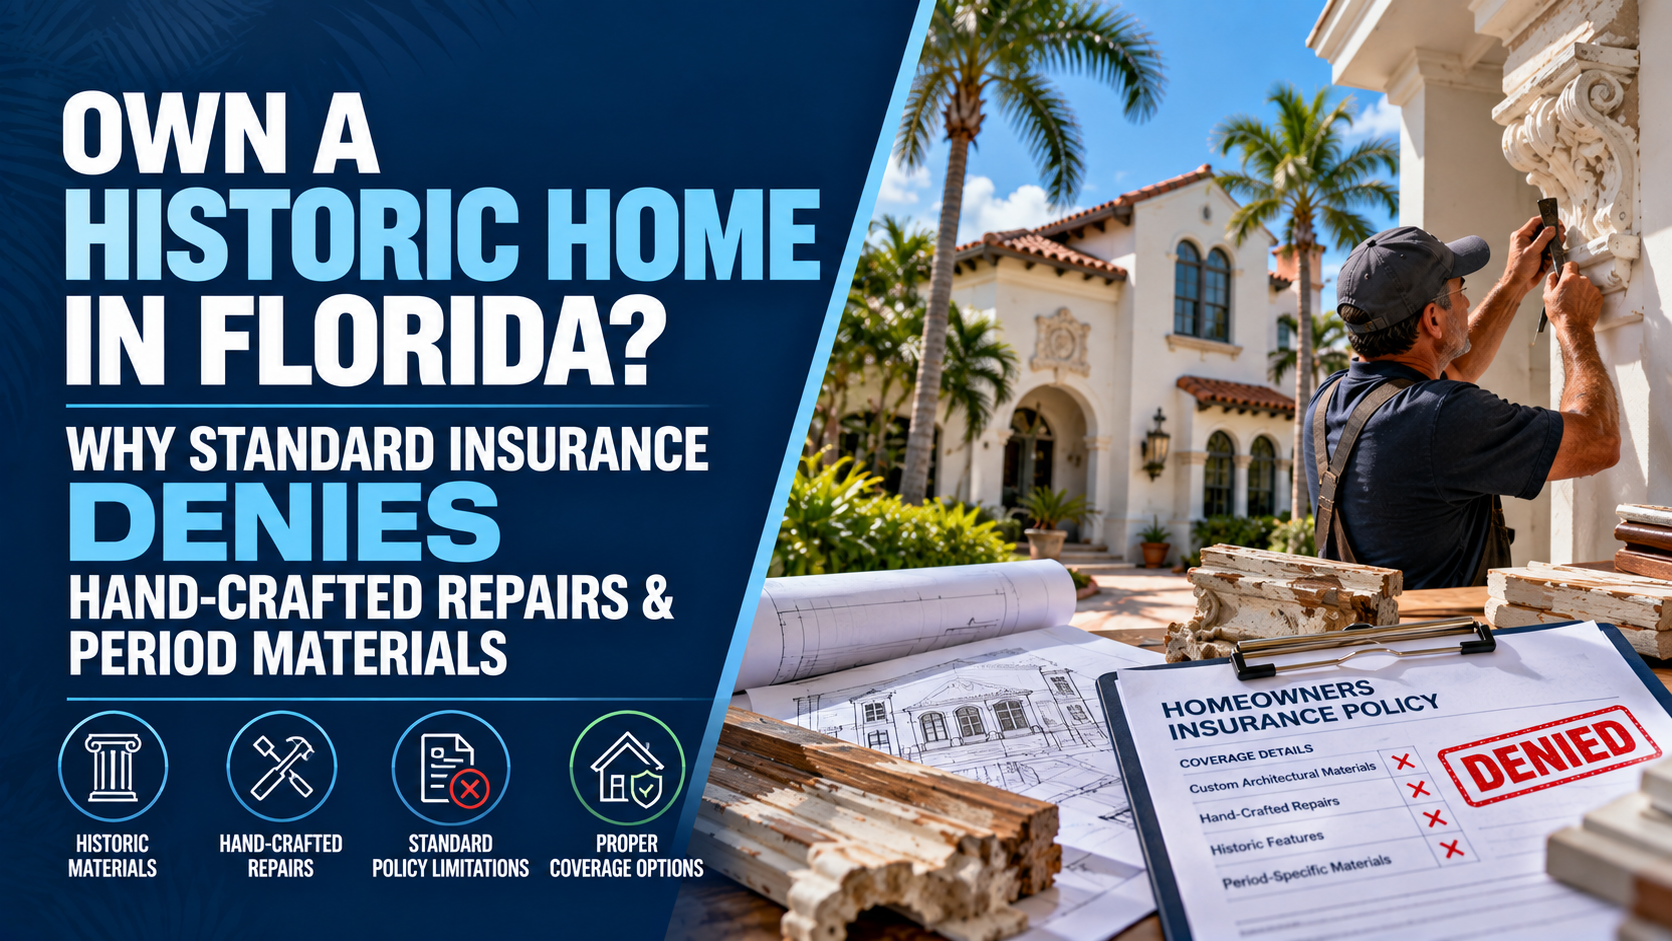
Own a Historic Home in Florida? Why Standard Insurance Denies Hand-Crafted Repairs & Period Materials
The Direct Answer
Here is a major financial risk facing Florida historic home owners: if your historic home suffers damage from a storm, fire, or pipe burst, a standard homeowners insurance policy (HO-3) will pay only for standard modern construction materials like drywall, hollow-core doors, and asphalt shingles—denying coverage for hand-crafted repairs, custom plasterwork, heart-pine flooring, and period-accurate architecture.
Florida is rich in architectural heritage, from Key West Conch houses and St. Augustine Spanish Colonial homes to Coral Gables Mediterranean Revivals and Tampa’s historic Ybor City casitas. However, restoring these historic structures requires specialized artisans, hard-to-source materials, and compliance with local Historic Preservation Boards or National Register standards.
When a claim occurs, standard home insurance carriers apply Functional Replacement Cost or standard Replacement Cost Estimators. Under these default policy terms, the insurer is only contractually obligated to restore your property to a functional state using modern, off-the-shelf materials.
Without specialized policy endorsements, you will be forced to pay tens or hundreds of thousands of dollars out of pocket to preserve your home’s authentic character, or risk losing its historic designation altogether.
Preserving a piece of Florida history is a passion project, but watching an insurance adjuster write an estimate substituting hand-carved millwork with synthetic trim can be devastating. Understanding the gaps in standard home policies ensures your home's unique craft and historical integrity remain fully protected.
1. Why Standard Home Insurance Fails Historic Properties
Standard insurance contracts are built for tract housing and modern suburban construction. When applied to historic architecture, four critical coverage gaps emerge:
- Functional Replacement Cost Limitations: Most standard carriers default to repairing damage with modern functional equivalents—replacing lath-and-plaster walls with drywall, custom stained-glass with single-pane vinyl, or heart-pine floors with laminate.
- Ordinance or Law Coverage Gaps: Historic homes often fail modern building codes for electrical, plumbing, and wind resistance. Standard policies provide minimal Ordinance or Law coverage (often capped at 10% or 25% of Dwelling limit), leaving homeowners responsible for massive code-compliance upgrades required by local historic preservation commissions during repairs.
- Specialized Artisan Labor Exclusions: Restoring historic masonry, original slate or tile roofs, or custom gingerbread trim requires specialized preservation contractors. Standard insurance valuation software calculates labor costs based on standard framing and drywall crews, underfunding the actual cost of skilled historical labor.
- Depreciation & ACV Rules on Aged Features: Older roofs and historic building components are often forced onto Actual Cash Value (ACV) claim settlements, drastically reducing payout amounts due to age depreciation.
2. Standard Home Insurance vs. Historic & Architectural Specialty Coverage
Understanding how different policy types respond during a loss reveals why specialty historic coverage is essential:
- Standard Homeowners Policy (HO-3): Covers rebuilding with modern, mass-produced materials. Does not cover the cost of specialized historic artisans, original period materials, or strict historic board reconstruction mandates.
- Guaranteed / Extended Replacement Cost Endorsement: Increases your total dwelling limit by 25% to 50%+ above your base policy. It does cover unexpected cost overruns caused by material shortages and higher labor prices during widespread disaster repairs.
- Specialty Historic & High-Value Home Policy: Designed specifically for historic and architecturally significant properties. It does cover exact architectural reproduction using period-appropriate materials, specialized historical labor, and expanded Ordinance or Law limits to satisfy historic preservation board mandates.
3. Essential Steps to Protect Your Historic Florida Home
To ensure your home is adequately covered against catastrophic losses and modern repair exclusions, take these key steps:
- Obtain a Historic Appraisal / Reconstruction Cost Audit: Work with an appraiser experienced in historic architecture to establish a true reproduction cost estimate based on specialized labor and custom materials.
- Increase Ordinance or Law Limits to 50%: Ensure your policy carries the maximum available Ordinance or Law endorsement to cover mandatory historic commission build-back rules and current Florida Building Codes.
- Switch to Guaranteed Replacement Cost Coverage: Place your coverage with specialized insurance carriers that offer true guaranteed replacement cost or agreed-value terms for historical properties.
Why Working with an Independent Agency Matters
Protecting historic architecture in Florida requires deep knowledge of local preservation codes, high-value carrier guidelines, and coastal underwriting. At Walker Insurance Agency, we specialize in customizing home insurance for Florida’s unique historic and high-value properties.
- Historic Reconstruction Cost Analysis: We calculate true replacement costs that account for authentic craftsmanship, custom millwork, and specialized regional materials.
- Access to Specialty & High-Value Carriers: We partner with premier insurance carriers that offer guaranteed replacement cost, broad Ordinance or Law coverage, and period-accurate repair provisions.
- Preservation Board Alignment: We structure your policy so claim payouts align with the strict repair requirements enforced by local Florida historic commissions.
Frequently Asked Questions
1. Will my insurance company pay to restore my home according to Historic Preservation Commission rules?
Only if your policy includes sufficient Ordinance or Law coverage and specifies period-accurate replacement. Standard policies only pay for basic modern code compliance unless endorsed for historic preservation mandates.
2. Can I get a historic home policy if my electrical or plumbing systems are original?
Most Florida insurers require modern updates to core systems (updated copper/PVC plumbing, minimum 100-amp circuit breakers, and modern roof condition) to grant historic home coverage. Completing key system updates helps unlock specialized historic home policies.
3. What is the difference between Reproduction Cost and Functional Replacement Cost?
Reproduction Cost pays to recreate your home using exact duplicate period materials and hand-crafted techniques. Functional Replacement Cost pays to repair the home using modern, functional alternative materials like drywall and synthetic trim.
Protect Your Historic Investment Today
Don't wait for a storm or fire to discover that your standard insurance policy pays for cheap modern substitutes instead of your home's historic craftsmanship. Auditing your policy today ensures your property's legacy and financial value remain fully intact.
Keep your historic property, your investment, and your peace of mind completely secure. Contact Walker Insurance Agency today for a fast, zero-pressure Florida historic home insurance review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro Airbnb y Vrbo en Florida (2026): Cobertura de Huéspedes
¿Alquilas tu casa en Florida por Airbnb o Vrbo? Descubre por qué el seguro tradicional deniega reclamos por lesiones y daños en 2026 y cómo protegerte.
Read More →
Florida Airbnb & Vrbo Insurance (2026): Guest Injury & Claims
Renting your Florida home on Airbnb or Vrbo? Discover why standard homeowners policies deny guest injury and property claims, and how to stay protected in 2026.
Read More →
Seguro de Casa Histórica en Florida (2026): Cobertura Artesanal
¿Tienes una casa histórica en Florida? Descubre por qué el seguro estándar no paga materiales de época ni mano de obra artesanal en 2026 y cómo protegerla.
Read More →