Florida Storm Damage Claim Time Limits: The 1-Year Filing Rule
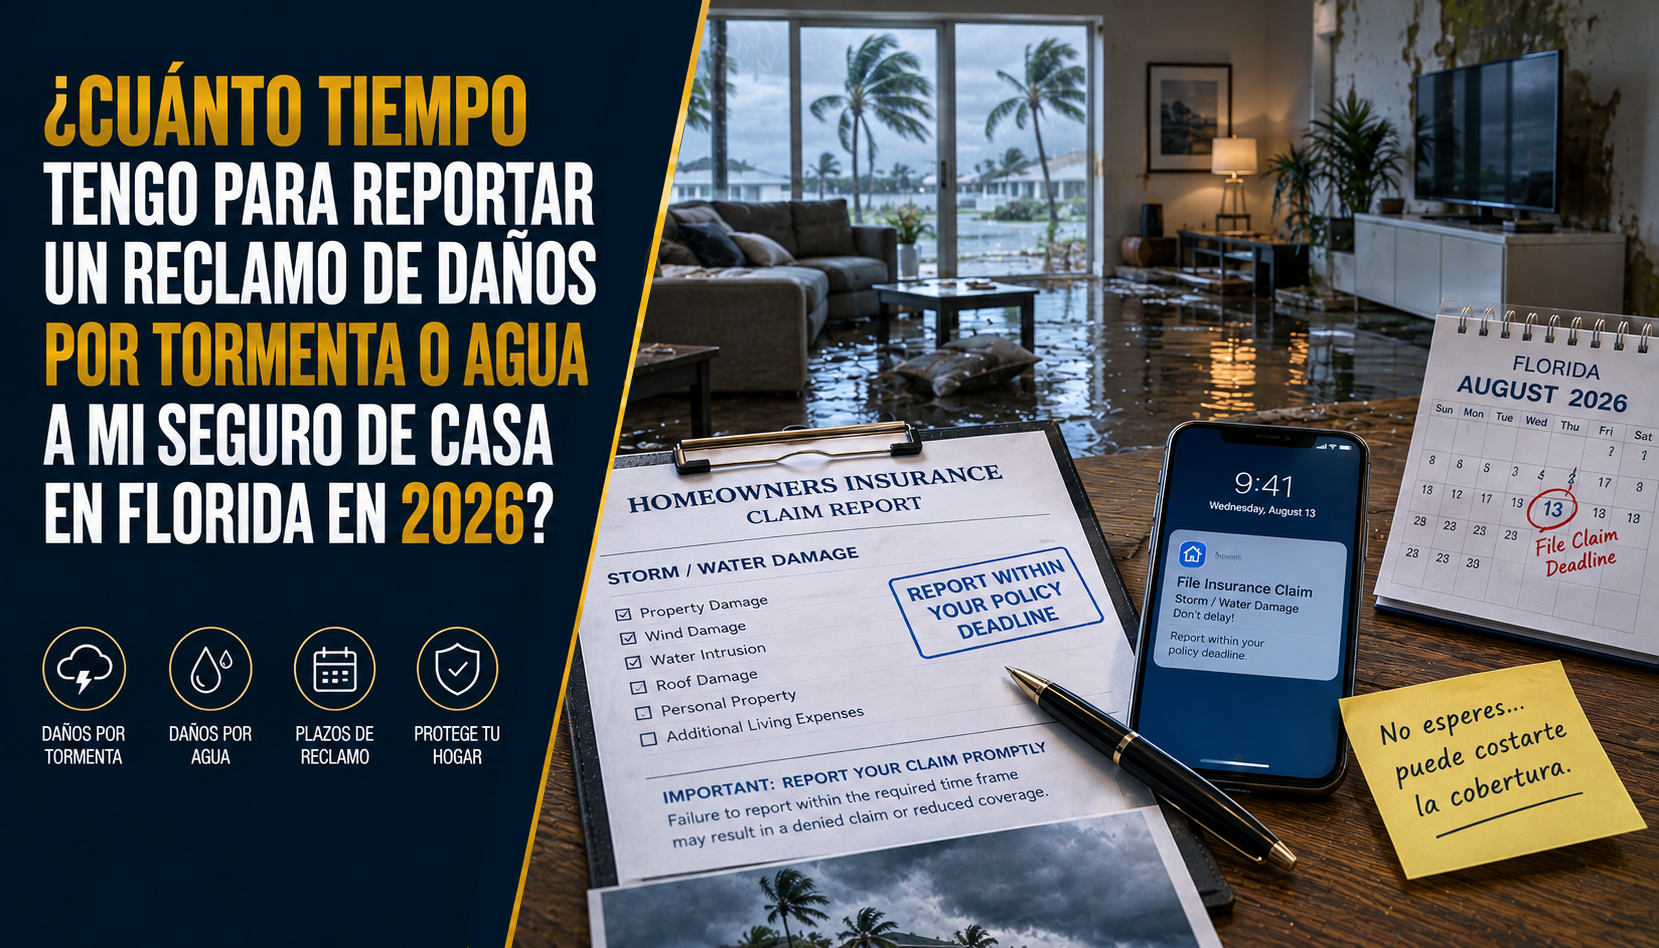
Had Storm Damage in Florida? Why Waiting Over 1 Year to File Denies Your Claim Automatically
The Direct Answer
Here is a strict legal reality for Florida homeowners dealing with hurricane or severe weather losses: under Florida law, you have exactly one year from the date of the storm to file an initial insurance claim, or your claim will be automatically denied by law.
Following major legislative reforms in Florida (including Senate Bill 2-A), the state drastically shortened the statutory timeframes for property damage claims.
Prior to these reforms, homeowners had up to three years to discover damage and report a loss to their carrier.
Today, if you discover roof leaks, structural damage, or hidden water intrusion caused by a storm and fail to report it within the 365-day deadline, your insurance company is legally required to reject the claim—regardless of how severe the damage is or how long you've paid your premiums.
Recovering from a severe weather event in Florida is overwhelming. However, putting off repairs or delaying a roof inspection because the damage seems minor can turn into a permanent financial disaster if you miss the state's strict 1-year filing window.
1. Florida’s 1-Year Rule for Storm Claims Explained
Florida Statute § 627.70132 governs the exact timelines for reporting property insurance claims resulting from a windstorm or hurricane:
- Initial Claims: You must give notice of an initial claim to your insurance carrier within 1 year (365 days) of the date the storm or hurricane made impact or caused damage.
- Reopened or Supplemental Claims: If you discover additional covered damage after your initial claim is settled, you have 18 months from the date of the loss to file a supplemental claim.
- No Exceptions for "Hidden" Damage: The 1-year clock starts ticking on the date of the loss, not on the day you notice the leak or hire a contractor.
2. Why Waiting Too Long Destroys Your Insurance Claim
Filing close to or after the 1-year deadline creates massive legal and technical hurdles that work against the homeowner:
A. Statutory Automatic Denial
If your claim timestamp is day 366, the insurance carrier's claims system will automatically issue a denial letter based on non-compliance with Florida Statute § 627.70132. Courts strictly enforce this rule, leaving zero room for negotiation.
B. The Burden of "Causation" Drops on You
The longer you wait to report damage, the harder it becomes to prove that the loss was caused directly by a specific storm rather than normal wear and tear, lack of maintenance, or subsequent weather events. Insurers will argue that ambient humidity, age, or neglect caused the deterioration.
C. Duty to Mitigate Damage
All Florida property insurance contracts require the homeowner to take reasonable steps to prevent further damage immediately following a loss. Waiting months to report a leaky roof allows mold and rot to spread—giving the insurer grounds to deny coverage due to failure to mitigate.
3. Action Plan: What to Do Immediately After a Storm in Florida
To protect your right to a full insurance payout under Florida’s tight 1-year deadline, follow these steps as soon as a major storm passes:
- Schedule a Post-Storm Roof & Property Inspection: Even if you don't see water dripping from your ceiling, hire a licensed professional to inspect your roof tiles, shingles, and flashing for lifted materials or wind creasing.
- Document Everything with Dates and Photos: Take high-resolution photos and videos of your property’s interior, exterior, yard, and roof immediately following the event.
- File Your Claim Immediately: Do not wait for contractor repair estimates before notifying your insurer. Report the initial claim right away to lock in your official timestamp well within the 1-year window.
Why Working with an Independent Agency Matters
Navigating tight statutory deadlines, claim reporting rules, and carrier requirements requires proactive support. At Walker Insurance Agency, we help Florida homeowners manage their coverage and navigate the claims process efficiently before deadlines expire.
- Proactive Claims Guidance: We help you understand exact policy deadlines, reporting procedures, and documentation requirements as soon as a storm impacts your area.
- Policy Audits & Review: We review your deductibles, windstorm limits, and property endorsements so you know your exact coverage before disaster strikes.
- Dedicated Local Advocacy: Located in Stuart, Florida, our independent team works directly for you—not the insurance company—to help ensure your claims are handled fairly and on time.
Frequently Asked Questions
1. Does the 1-year deadline apply to non-hurricane storm damage in Florida?
Yes. Florida Statute § 627.70132 applies to all property insurance claims resulting from a hurricane, tornado, severe windstorm, hail, or other weather events.
2. What if my contractor tells me I have plenty of time to file a claim?
Never rely on a contractor's timeline over Florida statutory law. Contractors are not licensed insurance professionals or legal experts. Always consult your independent insurance agent or attorney regarding claim filing deadlines.
3. What is the difference between a supplemental claim and a new claim?
A new claim reports a brand new loss event. A supplemental claim requests additional funds for an existing, previously reported claim because unexpected repairs or higher material costs were discovered during the restoration process.
Protect Your Home and Your Claim Rights Today
Don't let a tight legal deadline cost you thousands of dollars in out-of-pocket repairs. Scheduling a property inspection and filing your claim promptly ensures your home and savings remain fully protected.
Keep your property, your rights, and your peace of mind safe. Contact Walker Insurance Agency today for a fast, zero-pressure Florida home insurance review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro de Casa en Florida: Cobertura de Jaula de Alberca (2026)
¿Se destruyó tu jaula de alberca (pool cage) o mosquitero tras un huracán en Florida? Descubre por qué el seguro básico no lo cubre y cómo solucionarlo en 2026.
Read More →
Florida Hurricane Pool Cage Damage: Screen Enclosure Claims
Collapsed pool cage or damaged patio screen after a Florida hurricane? Learn why standard home insurance denies screen enclosure claims and how to buy coverage.
Read More →
Ley de Coincidencia de Techos en Florida (2026): Tejas No Coincidentes
¿Daños en el techo tras un huracán en Florida? Descubre cómo la Ley de Coincidencia obliga a la aseguradora a cambiar todo el techo si las tejas no coinciden.
Read More →