Own a Condo in Florida? Loss Assessment Coverage Explained (2026)
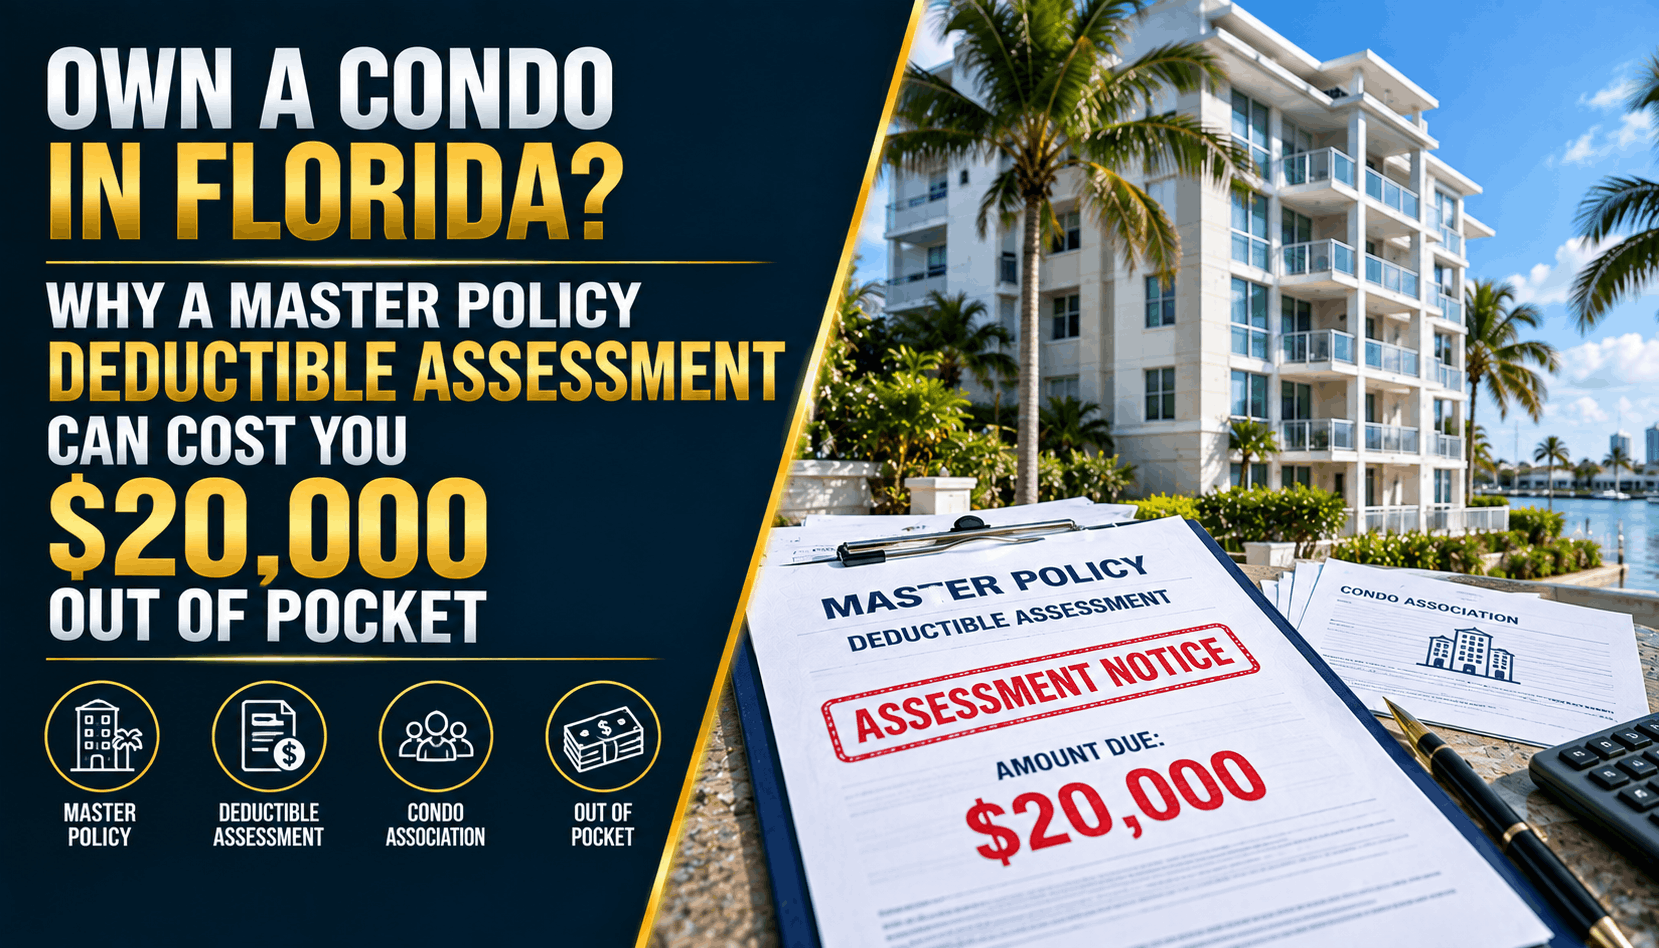
Own a Condo in Florida? Why a Master Policy Deductible Assessment Can Cost You $20,000 Out of Pocket
The Direct Answer
Here is a major financial risk facing Florida condominium owners in 2026: if a hurricane or severe storm damages your condo building’s common elements, your Homeowners Association (HOA) can legally divide the Master Policy’s massive hurricane deductible among all unit owners—leaving you with an unexpected assessment bill of $10,000 to $20,000+ out of pocket.
Many condo owners assume their HOA's master insurance policy covers all structural storm damage to the complex.
While the master policy does cover building structures and shared amenities, master policy deductibles in Florida are calculated as percentages (often 3%, 5%, or 10%) of the total building replacement cost.
When a major hurricane hits, that deductible can easily total hundreds of thousands of dollars. The HOA board passes this gap down to individual unit owners as a Loss Assessment. Without adequate Loss Assessment Coverage built into your individual HO-6 condo policy, you are personally responsible for paying that balance.
Living in a Florida condo offers low-maintenance living and ocean breezes. However, opening your mail after a hurricane to discover that your HOA board has assessed every unit owner $20,000 to cover the master policy’s windstorm deductible can quickly turn your coastal lifestyle into a severe financial crisis.
1. How Master Policy Deductible Assessments Work in Florida
To understand how an individual condo owner ends up with a massive loss assessment bill, it helps to break down how commercial condo insurance policies operate:
- The HOA Master Policy: The condo association carries a commercial insurance policy that protects shared structural elements: the roof, exterior walls, hallways, elevators, clubhouses, and pool areas.
- The Percentage-Based Hurricane Deductible: Commercial master policies in Florida rarely have fixed dollar deductibles (like $2,500) for windstorm damage. Instead, they carry a 3% to 10% hurricane deductible based on the total replacement value of the entire property.
- The Math Behind the Assessment:
- Imagine a 50-unit condo building with a total structural replacement value of $10,000,000.
- The HOA’s master policy has a 5% hurricane deductible, which equals $500,000.
- A Category 4 hurricane causes $2,000,000 in roof and structural damage across the building.
- Before the insurance company pays a single dollar toward repairs, the HOA must pay the $500,000 deductible.
- The HOA divides that $500,000 equally among all 50 unit owners. Your personal Loss Assessment bill: $10,000.
2. Florida Law & Your Individual HO-6 Policy Coverage
Florida Statute § 627.714 regulates how individual unit owner insurance policies (HO-6 policies) interact with condo association loss assessments:
- Statutory Minimum Coverage: Under Florida law, every individual HO-6 condo policy that includes unit property coverage must include at least $2,000 in Loss Assessment Coverage.
- The $2,000 Fallacy: While $2,000 is the legal baseline, it is nowhere near enough to cover modern commercial master policy deductibles in Florida. If your HOA assesses you $15,000 and you only carry the basic $2,000 limit, you must pay the remaining $13,000 out of pocket.
- Master Policy Deductible Assessments: Florida law allows HO-6 loss assessment coverage to apply directly to master policy deductibles, provided the assessment is caused by a covered peril (such as hurricane windstorm damage). However, policies often limit how much loss assessment payout can go toward a master policy deductible unless endorsed correctly.
3. Key Endorsements: How to Protect Your Wallet
Protecting yourself against special HOA storm assessments requires properly structuring your personal HO-6 policy before hurricane season begins:
- Increase Your Loss Assessment Limits: Upgrade your standard $2,000 Loss Assessment coverage to $10,000, $25,000, or $50,000. Increasing this limit usually costs a very modest amount in annual premium compared to the financial protection it offers.
- Check Master Policy Deductible Sub-Limits: Read the fine print of your HO-6 policy. Some insurance companies cap loss assessment payouts for master policy deductibles at $1,000 or $2,500 unless you add a specific Master Policy Deductible Endorsement.
- Review Your HOA’s Master Policy Annually: Ask your condo board for a copy of the association’s insurance declaration page each year. Take note of the commercial property replacement value and the exact hurricane deductible percentage so you know your potential maximum exposure.
Why Working with an Independent Agency Matters
Navigating condo association bylaws, commercial master policies, and personal HO-6 endorsements requires detailed, specialized insurance knowledge. At Walker Insurance Agency, we help Florida condo owners audit their coverage to eliminate out-of-pocket surprise assessments.
- HOA Master Policy Reviews: We analyze your condo association’s master policy limits and deductibles to determine the exact amount of Loss Assessment coverage you need on your personal policy.
- Custom HO-6 Policy Structuring: We ensure your personal policy properly coordinates loss assessment coverage, unit interior coverage (walls-in), personal liability, and personal property protection.
- Dedicated Local Guidance: Located in Stuart, Florida, our independent agency works for you—not a single insurance company—providing clear, honest advice to keep your home and savings secure.
Frequently Asked Questions
1. Does my personal HO-6 condo insurance cover regular HOA maintenance assessments?
No. Loss Assessment coverage only applies to special assessments triggered by direct physical loss or structural damage to common property caused by a covered peril (such as a hurricane, fire, or windstorm). It does not cover routine maintenance fees, budget shortfalls, or delayed building repairs.
2. What happens if I can't pay a loss assessment charged by my condo association?
If an owner fails to pay a mandatory special assessment, the condo association can place a legal lien on the individual condo unit, charge interest and legal fees, and potentially initiate foreclosure proceedings under Florida condo association laws.
3. Does Loss Assessment coverage apply to flood damage to the condo building?
Loss assessment coverage only applies if the underlying damage was caused by a peril covered by your policy. Standard HO-6 policies cover windstorms and fire, but exclude flood damage. If rising surge water damages common areas, your loss assessment coverage will only respond if your HO-6 policy includes specialized flood loss assessment protection.
Protect Your Condo and Your Financial Peace of Mind Today
Don't wait for a major hurricane to reveal that your condo association's insurance deductible will cost you tens of thousands of dollars. Increasing your Loss Assessment coverage today ensures you can handle surprise HOA assessments with total confidence.
Keep your condo, your lifestyle, and your savings protected. Contact Walker Insurance Agency today for a fast, zero-pressure Florida condo insurance review.
[GET A FREE FLORIDA CONDO INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida condo insurance rules and protect your property.
Related Articles
¿Cubre el Seguro los Daños por Huracán en mi Jaula de Piscina o Terraza en Florida? (2026)
¿Un huracán destruyó la jaula de tu piscina, terraza o cobertizo en Florida? Descubre los límites de cobertura y cómo proteger tus estructuras exteriores en 2026.
Read More →
Hurricane Damage to Pool Enclosure in Florida? Coverage Limits 2026
Did a hurricane destroy your screened pool cage in Florida? Learn why standard home insurance caps enclosure payouts and how to protect your pool cage in 2026.
Read More →
¿Cubre el Seguro HO-6 los Loss Assessments en Florida? (2026)
¿Tu condominio en Florida aprobó una tasación especial tras un huracán o fuga? Descubre cómo te protege la cobertura Loss Assessment de tu póliza HO-6 en 2026.
Read More →