Sewer Backup vs. Flood Insurance in Florida (2026): Coverage Gaps
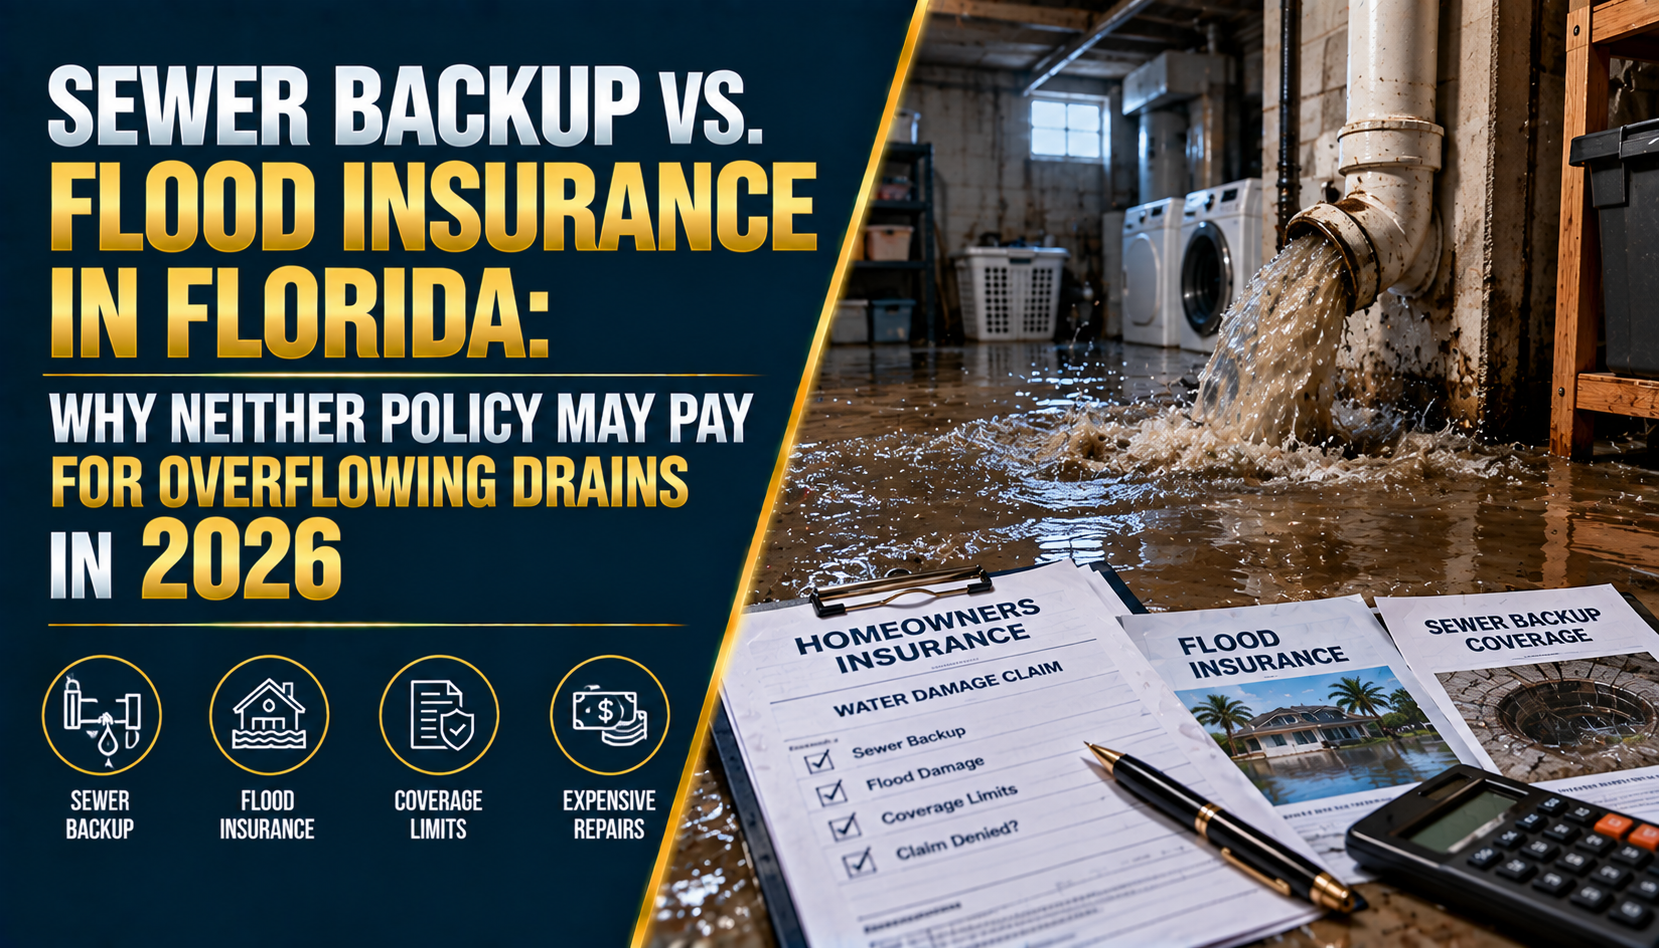
Sewer Backup vs. Flood Insurance in Florida: Why Neither Policy May Pay for Overflowing Drains in 2026
The Direct Answer
Here is the raw truth about Florida storm damage claims: toxic wastewater backing up into your sinks, showers, and toilets falls into a massive policy loophole. Standard home insurance explicitly excludes sewer backups, while traditional flood insurance (NFIP) only covers surface water entering from outside the house. To avoid eating tens of thousands of dollars in cleanup costs in 2026, you need a specific add-on known as a Water Backup Endorsement.
During peak hurricane season and severe rainfall events in Florida, municipal storm drains and sewer lines get overwhelmed fast.
When the city’s infrastructure hits maximum capacity, that backed-up water has nowhere to go but backward—surging straight up through your home’s lowest drains, showers, and toilet bowls.
The brutal awakening for thousands of Florida homeowners is finding out that despite paying top dollar for both home and flood insurance, neither policy will pay a dime for this biohazardous nightmare unless you actively added the right rider.
Walking into a home flooded with raw sewage after a storm is gut-wrenching. Finding out both of your insurance companies are washing their hands of the claim due to fine-print exclusions turns a dirty mess into a complete financial disaster.
1. The Home Insurance Trap: The Dreaded Water Exclusion
A standard Florida homeowners policy (HO-3) covers sudden, internal plumbing bursts—like a snapped pipe under your bathroom vanity.
However, insurers write heavy-handed Water Exclusion Clauses into their base contracts that flat-out deny coverage for:
- Water or sewage that backs up through sewers, drains, or septic systems.
- Water discharging or overflowing from a sump pump due to power failure or mechanical failure.
- Subsurface groundwater seeping upward through foundation slabs or basement walls.
If the dirty water travels bottom-up through your plumbing fixtures, your primary homeowners insurer will slap you with an instant denial letter.
2. The Flood Insurance Myth: The 2-Acre Surface Water Rule
A lot of Floridians assume that buying National Flood Insurance Program (NFIP) coverage or a private flood policy shields them against anything involving heavy rain. That is a dangerous assumption.
Federal guidelines and NFIP rules enforce a strict legal definition for what actually constitutes a Flood:
Legal Definition of a Flood: A general and temporary condition of partial or complete inundation of 2 or more acres of normally dry land area, OR of 2 or more properties (at least one of which is the insured's property) from overflow of inland or tidal waters or rapid accumulation of surface waters.
- Outside-In Only: Flood insurance strictly covers rising water that invades your home from the outside-in (flowing over threshold doors, garage slabs, or breaking through windows).
- The Sewer Backup Catch: If the street outside isn't submerged under the 2-acre rule and water solely backs up through your indoor drains, flood insurance will reject the claim because it stems from a drain failure, not a qualifying surface flood.
3. Side-by-Side Coverage Breakdown in Florida
| Coverage Type | Source of Water | Covers Sewer / Drain Backups? | How to Get It |
|---|---|---|---|
| Standard Homeowners Insurance | Internal pipe bursts, sudden plumbing breaks. | NO (Standard policy exclusion). | Base property policy. |
| Flood Insurance (NFIP/Private) | Rising surface water entering from the outside. | NO (Unless directly tied to a general surface flood). | Standalone flood policy. |
| Water Backup Endorsement | Sewage/drain backups, sump pump overflows. | YES (Pays for biohazard cleanup & repairs). | Optional rider attached to home insurance. |
4. The Fix: Water Backup and Sump Discharge Endorsement
Closing this coverage gap is straightforward. You must request a Water Backup and Sump Discharge or Overflow Endorsement attached directly to your homeowners insurance policy.
This affordable rider locks in essential protection when lines colapse:
- Flexible Limits: You can select standalone coverage amounts ranging from $5,000 to $25,000+.
- Biohazard Cleanup & Remediation: Covers specialized hazardous waste extraction, professional sanitization, and air scrubbing crews.
- Structural & Property Repairs: Pays to tear out and replace contaminated drywall, ruined subflooring, baseboards, and destroyed vanity cabinets.
Why an Independent Agency Makes All the Difference
Unpicking the subtle differences between surface water, sewer backups, and internal pipe breaks requires local expertise. At Walker Insurance Agency, we audit Florida policies to make sure zero hidden gaps threaten your hard-earned savings.
- Water Exclusion Audits: We dissect your home and flood policies to verify whether you have active water backup protection before the next storm rolls in.
- Multi-Policy Structuring: We tailor a complete safety net combining your primary dwelling coverage, flood insurance, and critical endorsements into one seamless defense strategy.
- Local Florida Advocacy: Based in Stuart, Florida, our independent team works exclusively for you—delivering honest advice to keep your family and property fully protected.
Frequently Asked Questions
1. How much does a Water Backup Endorsement cost in Florida?
Adding a Water Backup rider is remarkably inexpensive. Depending on your carrier and the limit you choose (e.g., $5,000 or $10,000), it typically costs just $25 to $100 per year.
2. Will my insurance pay to fix the city’s sewer pipe if it caused the backup?
No. The Water Backup Endorsement covers the damage, extraction, and structural restoration inside your insured property. It does not pay to repair public infrastructure or utility mainlines off your premises.
3. What should I do immediately if sewage starts overflowing from my drains?
Shut off your main water line immediately to stop adding volume to the system, avoid flushing toilets or running faucets, take clear photos and videos of the backup points, and call a professional water mitigation crew alongside your independent insurance agent.
Don't Get Caught Off-Guard This Storm Season
Don't wait for a municipal sewer collapse to fill your bathrooms with toxic wastewater before realizing you lacked coverage. Securing a Water Backup Endorsement today guarantees total peace of mind when extreme weather hits.
Keep your property, your health, and your savings completely bulletproof. Contact Walker Insurance Agency today for a fast, zero-pressure Florida home insurance review.
[GET A FREE FLORIDA HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Remodelaciones en Florida (2026): ¿Cubre el Seguro Robos o Daños?
¿Vas a remodelar tu casa en Florida? Descubre por qué el seguro de hogar estándar niega reclamos por robo de materiales o daños en obras y cómo protegerte.
Read More →
Florida Home Remodeling: Theft & Damage Insurance Denials (2026)
Planning a home remodel in Florida? Discover why standard homeowners insurance denies theft and structural claims during construction and how to protect your project.
Read More →
¿Cubre el Seguro el Agua del Drenaje por el Inodoro en Florida? (2026)
¿El agua del drenaje se regresó por tu inodoro en Florida? Descubre por qué ni el seguro de casa ni el NFIP lo cubren y cómo protegerte en 2026.
Read More →