Florida Commercial Solar Insurance: Roof Load & Panel Claims
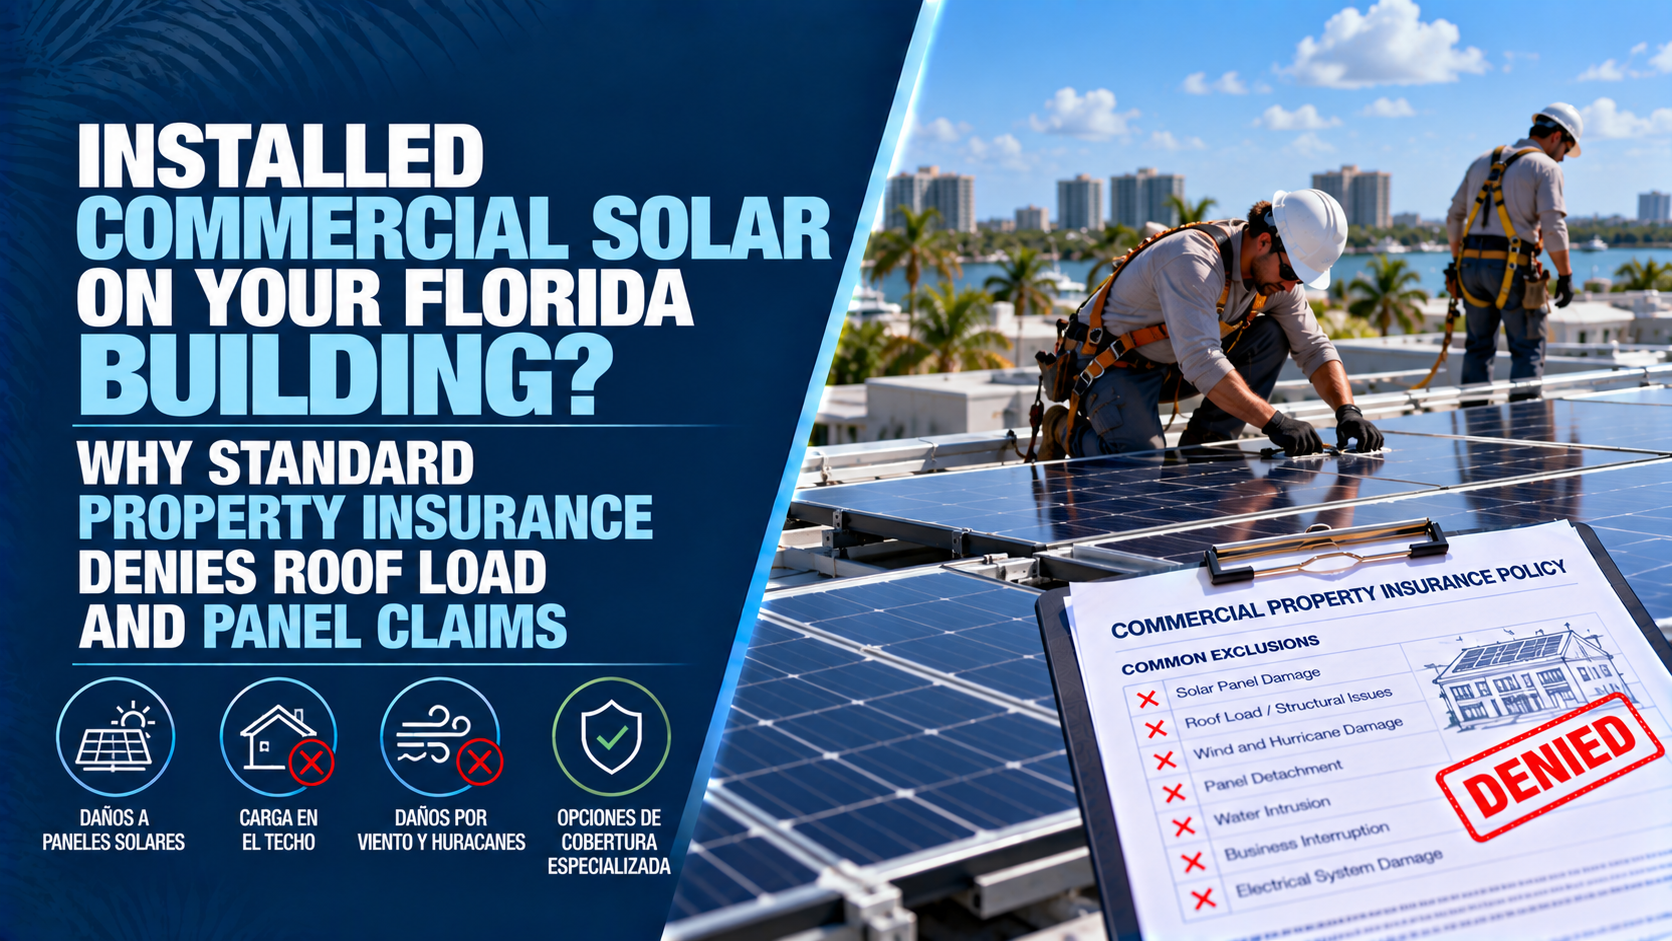
Installed Commercial Solar on Your Florida Building? Why Standard Property Insurance Denies Roof Load and Panel Claims
The Direct Answer
Here is a major insurance trap facing Florida commercial property owners in 2026: if you install a rooftop solar array on your commercial building and experience structural damage, roof leaks, panel detachment, or severe windstorm losses, your standard Commercial Property Insurance policy (CP 00 10) will likely deny the claim entirely.
Florida ranks among the top states for commercial solar installations, driven by high sun exposure, rising utility costs, and federal clean energy tax credits. However, adding hundreds of photovoltaic (PV) panels, mounting racks, and heavy ballasts fundamentally alters the structural profile and risk dynamics of a commercial building.
Standard commercial property insurance forms treat unannounced solar installations as an unapproved Increase in Hazard or classify the panels as separate equipment excluded under land-based building definitions.
When a hurricane triggers severe wind uplift, or when heavy racking causes structural roof load failure, repairing damaged PV equipment, restoring collapsed roof trusses, and replacing commercial roofing easily runs from $100,000 to over $500,000. Without specialized Commercial Solar & Equipment Endorsements, your primary insurer will leave you holding the entire repair bill.
Investing in commercial solar is a smart operational strategy to reduce overhead and hit sustainability goals. However, discovering after a severe storm or roof sag that your commercial property policy excludes the solar equipment—and voids coverage for the underlying building—can severely damage your company’s balance sheet.
1. Why Standard Commercial Policies Deny Solar Claims
Standard commercial property policies are underwritten based on original building blueprints and standard commercial roof construction. Adding rooftop solar triggers four primary policy exclusions and coverage gaps:
- Failure to Report / Increase in Hazard Exclusions: Failing to notify your commercial insurer prior to installing a rooftop solar array gives the carrier grounds to deny claims or void building coverage under the "Increase in Hazard" clause due to added weight and electrical risks.
- Roof Load & Structural Deflection Exclusions: Standard policies strictly exclude structural collapse or roof sagging caused by dead load stress (the weight of panels, ballasts, and racking) or live load stress (accumulated rainwater around racking blockages).
- Wind Uplift & Hurricane Detachment: Florida's High-Velocity Hurricane Zones (HVHZ) feature extreme wind speeds. Standard commercial windstorm coverage often excludes external rooftop machinery, solar racking, or detachment-and-reset costs unless explicitly scheduled.
- Roof Water Intrusion Limits: If panel mounting hardware penetrates the roof membrane and leads to water leaks, standard policies classify the damage as faulty installation or maintenance wear—denying coverage for both the roof leaks and internal business property damage.
2. Standard Commercial Property vs. Specialty Solar Endorsements
Understanding how different policy structures handle commercial solar arrays highlights why tailored endorsements are essential:
- Standard Commercial Property Policy (CP 00 10): Covers primary building structures, interior buildouts, and inventory. Excludes unscheduled rooftop PV panels, structural collapse due to dead load weight, panel detach/reset fees during roof repairs, and solar business interruption.
- Commercial Building Policy with Scheduled Solar Rider: Classifies the solar array as part of the primary real property structure. Does cover physical panel damage from wind, hail, or fire, up to the newly adjusted total building replacement value.
- Specialty Commercial Solar & Renewable Energy Policy: Dedicated coverage written specifically for commercial solar arrays. Does cover physical panel damage, wind uplift, structural roof load impacts, mechanical breakdown, solar-related liability, and Lost Utility Production / Solar Income Replacement.
3. Essential Coverages Needed for Florida Commercial Solar Installations
To safeguard your commercial property, clean energy investment, and operational cash flow, your commercial insurance plan should include four core protections:
- Scheduled PV Equipment & Mounting Structure Coverage: Ensures the full replacement value of panels, microinverters, wiring, and mounting racks is included under your building's total insured value (TIV).
- Solar Detach and Reset Endorsement: Covers the substantial labor and crane costs required to temporarily remove and reinstall rooftop solar panels whenever the underlying commercial roof needs hurricane repairs or maintenance.
- Loss of Solar Utility Production / Business Interruption: Reimburses your business for lost energy savings, utility grid sell-back revenue, or SREC credits while your solar array is offline following a covered physical loss.
- Commercial Solar Liability Rider: Protects against third-party property damage or bodily injury claims resulting from solar-related electrical fires, panel detachment debris, or thermal runaway events.
4. How to Properly Protect Your Florida Commercial Solar Investment
Protecting your commercial facility and solar array against catastrophic claim denials involves three strategic steps:
- Obtain a Structural Engineering Analysis: Ensure a licensed Florida structural engineer verifies that your roof's load-bearing capacity and truss framing safely support the added dead weight and wind uplift vectors of the solar array.
- Notify Your Commercial Insurance Carrier Early: Provide your insurer with installation specs, single-line electrical diagrams, and engineering stamps before installation to update your Total Insured Value (TIV) and avoid "Increase in Hazard" exclusions.
- Audit Policy Endorsements for Detach/Reset and Solar Revenue: Check your commercial policy declarations page to confirm that solar equipment, detach/reset labor, and energy interruption coverage are explicitly listed.
Why Working with an Independent Agency Matters
Navigating commercial property endorsements, structural engineering requirements, and Florida Office of Insurance Regulation (OIR) guidelines demands localized commercial expertise. At Walker Insurance Agency, we specialize in structuring custom insurance solutions for commercial property owners and clean energy investments.
- Commercial Building & TIV Audits: We re-evaluate your building's Total Insured Value to incorporate rooftop solar arrays, eliminating underinsurance penalties during a claim.
- Access to Specialty Commercial Carriers: We partner with top-rated commercial lines and renewable energy underwriters to secure broad panel, roof load, and windstorm coverage tailored to your building.
- Seamless Risk Alignment: We structure your policy so land-based commercial property, solar equipment, and business interruption coverages work together without hidden gaps.
Frequently Asked Questions
1. Does my commercial roof warranty stay valid after installing rooftop solar panels?
Installing solar panels can void or compromise your commercial roof warranty (e.g., TPO, EPDM, or built-up roofs) if the installation involves unapproved membrane penetrations or racking. Always coordinate with your roof manufacturer and commercial insurer prior to installation.
2. Who pays to remove the solar panels if my commercial roof suffers hurricane damage?
If your policy includes a Solar Detach and Reset Endorsement, the insurance carrier covers the crane, electrical, and labor costs to remove and reinstall the array. Under a standard policy without this rider, those costs are paid entirely out of pocket.
3. Will my commercial property premium increase after installing solar panels?
Yes, your premium will adjust upward because your building's Total Insured Value (TIV) increases by the replacement cost of the solar system. However, securing the proper endorsement ensures full financial protection against multi-hundred-thousand-dollar claim denials.
Safeguard Your Commercial Building and Solar Investment Today
Don't wait for a windstorm, roof leak, or structural issue to reveal that your standard commercial policy excludes your rooftop solar system. Securing proper commercial solar endorsements protects your real estate, your clean energy savings, and your business cash flow in 2026.
Keep your commercial facility, your solar array, and your business revenue completely secure. Contact Walker Insurance Agency today for a fast, zero-pressure commercial property and solar insurance review.
[GET A FREE FLORIDA COMMERCIAL INSURANCE QUOTE TODAY]
Call our commercial insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro Comercial en Florida: Paneles Solares y Pérdida de Energía (2026)
¿Instalaste paneles solares en tu edificio en Florida? Descubre por qué el seguro comercial estándar deniega la carga en techo, ráfagas y pérdida de energía en 2026.
Read More →
Horse Boarding Insurance in Florida: Boarder Injury & Horse Loss
Boarding horses or giving riding lessons in Florida? Learn why standard farm insurance may not cover boarder injuries, horse losses, or equine liability.
Read More →
¿Cubre el Seguro de Finca un Caballo Lesionado en Florida? | 2026
¿Un caballo de terceros se lesionó o un jinete cayó en tu propiedad de Florida? Descubre qué puede cubrir tu seguro de finca o casa en 2026.
Read More →