Florida Hurricane Manufactured Home Insurance: Tie-Downs & Carports
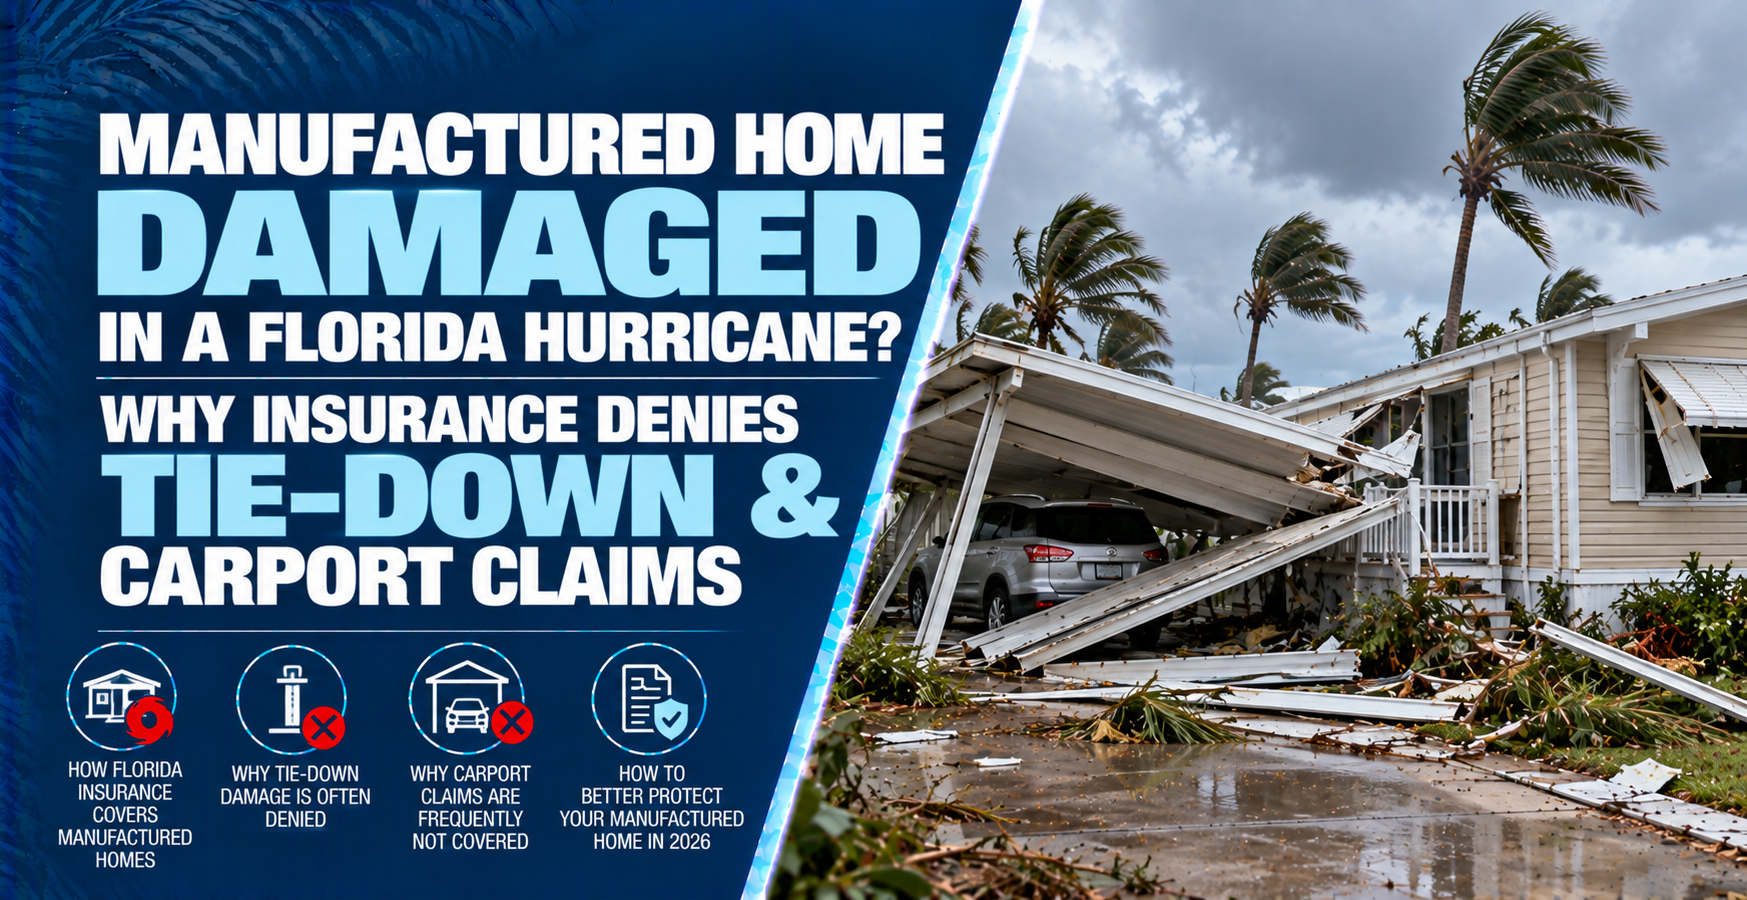
Manufactured Home Damaged in a Florida Hurricane? Why Insurance Denies Tie-Down & Carport Claims
The Direct Answer
Here is a critical coverage hurdle facing owners of manufactured, mobile, and modular homes in Florida: standard mobile home insurance policies (HO-7 or MHO) frequently exclude or heavily restrict coverage for attached aluminum carports, screened lanais, utility sheds, and foundation tie-down systems following a hurricane.
When hurricane-force winds hit a manufactured home community, lightweight exterior structures—such as aluminum carports, awnings, and attached sheds—are often the first components to fail or detach.
When policyholders file damage claims, insurers frequently deny or underpay them citing carport windstorm exclusions, improper anchor/tie-down installation, or lack of building code compliance.
Under Florida administrative rules and building codes (such as Florida Administrative Code Rule 15C-1), manufactured homes must meet strict tie-down, anchoring, and wind-load standards.
If an inspection reveals that corroded ground anchors or uncertified tie-downs contributed to structural shifting during a storm, carriers can legally deny claims for both the attached structures and the primary dwelling itself based on maintenance or installation exclusions.
Recovering from hurricane damage in a manufactured home requires understanding how structural tie-down mandates, aluminum structure endorsements, and mobile home policy terms interact under Florida insurance rules.
1. Why Insurance Companies Deny Mobile Home & Carport Claims
Insurance policies written for mobile and manufactured homes (HO-7 forms) differ significantly from standard site-built residential policies. Understanding these four key exclusion drivers helps prevent claim denials:
- Attached Aluminum Carports & Screen Enclosure Exclusions: Standard mobile home policies explicitly exclude unanchored or aluminum-framed carports, patio awnings, and screened lanais from basic windstorm coverage. To cover these structures, homeowners must add a specific Carport / Screen Enclosure Endorsement.
- Tie-Down & Ground Anchor Failures: Florida law mandates specific tie-down straps and ground anchors based on local Wind Zones (Zone II and Zone III). If an insurance adjuster finds rusted, missing, or improperly spaced tie-downs, the carrier can cite maintenance neglect or non-compliance to deny structural damage claims.
- Actual Cash Value (ACV) vs. Replacement Cost (RCV): Many older manufactured home policies settle claims on an Actual Cash Value (ACV) basis, deducting heavy depreciation for age. This leaves owners with payouts far below the actual cost to replace a damaged carport, roof-over, or siding.
- Detached Utility Sheds & Storage Structures: Standalone sheds or aluminum storage units are often capped under low secondary limits (e.g., 10% of Coverage A or a flat $2,000 cap), which fails to cover custom shed replacements and contents.
2. Standard Mobile Home Policy vs. Enhanced Protection
Comparing a basic manufactured home policy against an enhanced policy highlights the gap in post-hurricane claim payouts:
- Standard Mobile Home Policy (HO-7 / Basic MHO): Denies wind damage to carports, awnings, and lanais ($0 payout). Pays depreciated Actual Cash Value (ACV) on older roofs, and excludes foundation stabilization or tie-down upgrades.
- Enhanced Policy with Carport & Tie-Down Endorsements: Provides dedicated policy limits (e.g., $10,000–$25,000+) for attached aluminum carports and lanais. Settles home and structure repairs on a Replacement Cost Value (RCV) basis, and covers mandatory tie-down code upgrades via Ordinance or Law coverage.
3. Essential Steps to Protect Your Manufactured Home in 2026
To ensure your manufactured home, carport, and anchoring systems remain fully insurable and protected against Florida hurricanes, follow these four risk management steps:
- Schedule an Annual Tie-Down & Anchor Inspection: Retain a licensed Florida mobile home installer to inspect ground anchors, stabilizer plates, and steel straps for rust or slack, securing an official compliance certificate.
- Add a Dedicated Carport and Utility Structure Rider: Contact your independent agent to purchase explicit buy-back coverage for attached aluminum carports, awnings, screen enclosures, and sheds.
- Upgrade to Replacement Cost Value (RCV) Coverage: Ensure your policy covers the full replacement cost of your dwelling, additions, and personal property rather than depreciated cash value.
- Maintain Roof-Over Seals and Fasteners: If your manufactured home has a secondary roof-over system, keep maintenance logs showing regular inspections and sealant applications to disprove carrier claims of pre-existing leaks.
4. How to Manage a Claim After a Hurricane
If high winds damage your manufactured home, carport, or tie-down system during a storm, follow these immediate steps:
- Document Structural Anchors and Post Attachments: Take high-resolution photos of intact or failed ground anchors, carport support posts, roof edges, and attached sheds before moving debris.
- Prevent Secondary Water Damage: Tarp damaged roof-overs or exposed walls immediately to prevent rain intrusion, keeping all receipts for emergency materials.
- Submit Tie-Down Compliance Records: Provide your adjuster with pre-storm tie-down inspection certificates to prove your anchoring system met Florida Administrative Code standards prior to the hurricane.
- Obtain Bids from Licensed Mobile Home Contractors: Secure itemized replacement estimates from contractors licensed specifically for manufactured housing and specialty aluminum construction in Florida.
Why Working with an Independent Agency Matters
Insuring manufactured homes, park models, and coastal mobile home communities in Florida requires specialized policy structuring. At Walker Insurance Agency, we assist manufactured home owners across coastal Florida in securing comprehensive property coverage.
- Tie-Down & Policy Compliance Audits: We review your policy terms to identify hidden carport exclusions, ACV traps, and anchoring requirements before storm season.
- Access to Premier Mobile Home Carriers: We partner with top Florida carriers offering specialized manufactured home policies with flexible carport riders, full RCV options, and high windstorm limits.
- Local Claim Guidance: We assist policyholders during the claim process, ensuring proper documentation is submitted to secure full payouts for attached structures.
Frequently Asked Questions
1. Does Florida law require manufactured homes to have certified tie-downs?
Yes. Florida Administrative Code Rule 15C-1 sets strict anchoring and tie-down standards for mobile and manufactured homes based on county wind zones. Maintaining compliant tie-downs is essential both for physical safety and for keeping your property insurance policy valid.
2. Can I get insurance coverage for a carport if my manufactured home is over 20 years old?
Yes, but coverage availability depends on the carrier and structural condition. Many specialty carriers offer attached carport and screen enclosure endorsements for older manufactured homes, provided the structure is well-maintained and securely anchored.
3. What is the difference between a mobile home and a manufactured home for insurance purposes?
Technically, homes built before June 15, 1976 (when HUD safety standards took effect) are classified as mobile homes, while those built after are manufactured homes. For insurance purposes, both use HO-7 or specialized dwelling forms, but newer manufactured homes often qualify for broader replacement cost options.
Protect Your Manufactured Home, Carport, and Investment Today
Don't wait for a hurricane to destroy your carport or shift your foundation before discovering your policy excludes attached structures. Securing the proper carport endorsement and verifying your tie-down compliance ensures your home remains completely protected in 2026.
Keep your manufactured home, your carport, and your financial peace of mind secure. Contact Walker Insurance Agency today for a fast, zero-pressure policy and mobile home coverage review.
[GET A FREE FLORIDA MANUFACTURED HOME INSURANCE QUOTE TODAY]
Call our home insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Florida Hurricane Solar Panel Insurance Claims: Limits & Caps 2026
Had rooftop solar panels damaged in a Florida hurricane? Learn why standard home insurance caps payouts, sub-limits apply, and how to avoid claim gaps in 2026.
Read More →
Seguro de Casa Móvil en Florida: Denegación de Reclamos (2026)
¿Tu casa móvil o manufactured home sufrió daños por un huracán en Florida? Descubre por qué el seguro deniega reclamos y qué coberturas necesitas en 2026.
Read More →
Seguro de Casa en Florida: Cobertura de Paneles Solares y Huracanes (2026)
¿Se dañaron tus paneles solares por un huracán en Florida? Descubre por qué el seguro estándar limita los pagos y qué coberturas necesitas en 2026.
Read More →