Florida Marina & Coastal Insurance: Seawall and Dock Collapse
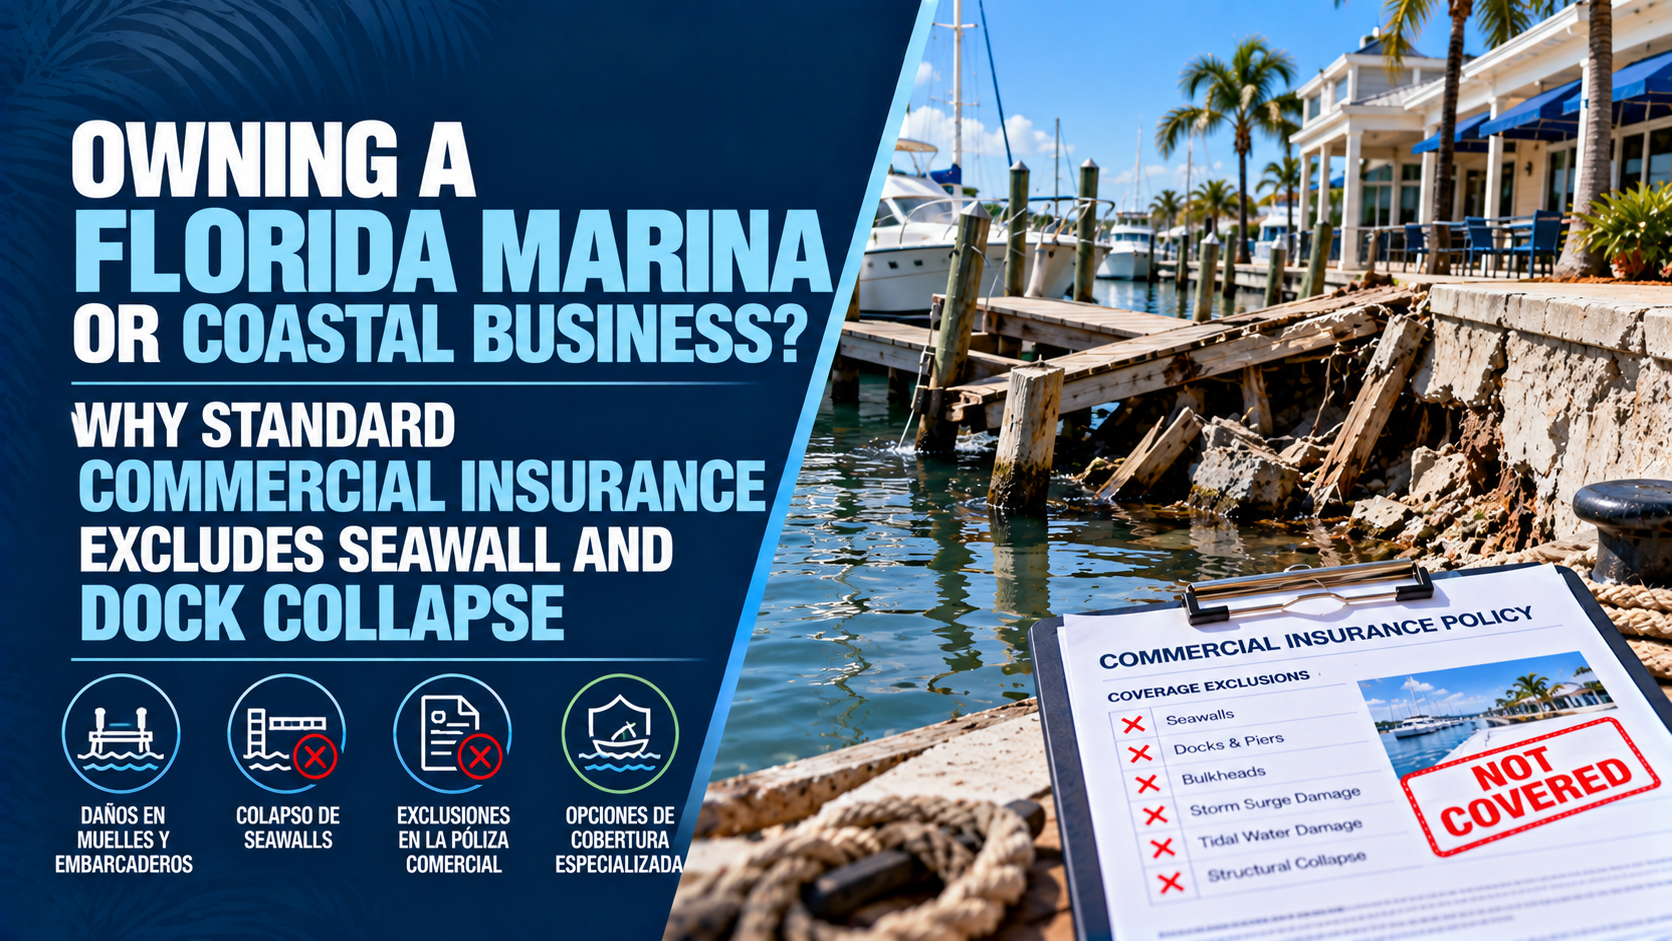
Owning a Florida Marina or Coastal Business? Why Standard Commercial Insurance Excludes Seawall and Dock Collapse
The Direct Answer
Here is a critical financial vulnerability facing Florida waterfront business owners: if your marine bulkhead, retaining wall, piers, or floating docks collapse due to wave action, tidal surge, soil erosion, or storm scour, a standard Commercial Property Insurance policy (CP 00 10) will exclude the damage entirely.
Florida boasts thousands of miles of coastline and navigable waterways, making waterfront businesses, commercial marinas, yacht clubs, and coastal resorts prime drivers of the state’s economy. However, standard commercial lines policies contain explicit Water, Earth Movement, and Marine Asset Exclusions. Under standard terms, structures extending over water or built below the high-water mark are categorized as high-risk, uninsurable property unless specific marine coverage is attached.
When a seawall failure or dock collapse occurs, rebuilding marine bulkheads, re-driving piles, and restoring deep-water docks easily costs $100,000 to over $1,000,000. Without specialized Commercial Marine Insurance and dedicated Dock and Seawall Endorsements, your primary insurance policy will leave you paying for total marine reconstruction out of pocket.
Managing a successful coastal business requires constant vigilance against saltwater environments. Discovering after a severe storm or high-tide surge that your commercial property policy excludes every foot of your waterfront infrastructure can destroy years of business equity.
1. Why Standard Commercial Policies Exclude Docks and Seawalls
Standard commercial general liability and property insurance forms are designed for landlocked, inland commercial buildings. When applied to waterfront exposures, three core exclusion categories trigger automatically:
- Property Outside Covered Buildings Exclusions: Standard commercial property forms specifically limit or exclude coverage for retaining walls, seawalls, bulkheads, pilings, piers, wharves, and docks unless specifically scheduled with specialized marine endorsements.
- Water and Surge Exclusions: Standard policies exclude damage caused by flood, surface water, waves, tidal water, overflow of any body of water, or spray from any of these, even when driven by wind during a storm.
- Gradual Erosion, Scour, and Saltwater Wear: Marine bulkheads fail over time due to wave action scouring the toe of the wall, tidal hydrostatic pressure, and saltwater corrosion of tie-back rods. Standard policies exclude gradual wear, tear, and earth movement.
2. Standard Commercial Property vs. Specialty Marine & Dock Coverage
Understanding how different commercial policies respond to coastal damage shows why dedicated marine coverage is vital:
- Standard Commercial Property Policy (CP 00 10): Protects land-based structures (main offices, retail buildings, inventory). Excludes seawalls, bulkheads, docks, pilings, wave action, and storm surge damage.
- Commercial Marine / Inland Marine Policy: Specialty marine coverage written specifically for marine contractors, marinas, and waterfront commercial sites. Does cover scheduled docks, floating piers, boardwalks, pilings, and specialized marine equipment (Equipment Floater).
- Specialty Seawall & Bulkhead Endorsement: Custom commercial property rider or marine coverage line. Does cover sudden physical collapse of seawalls, retaining walls, and bulkheads resulting from covered water events, collision, or severe weather storms.
3. Key Coverages Needed for Florida Coastal Businesses
To properly safeguard your waterfront operations, your insurance portfolio must integrate specialized marine lines:
- Dock, Pier, and Wharf Coverage: Schedules every floating and fixed dock structure, specifying agreed replacement values for pilings, decking, electrical pedestals, and plumbing runs.
- Bulkhead and Seawall Collapse Endorsement: Provides dedicated limits to repair, rebuild, or reinforce coastal seawalls damaged by covered marine perils.
- Marine General Liability (MGL) & Bumbershoot: Extends liability protection to cover vessel collisions with your docks, guest slips, slipholder injury, and pollution/fuel dock incidents.
- Commercial Loss of Income (Waterfront Operations): Reimburses lost slip rentals, fuel sales, and dockage revenue while ruined docks or seawalls undergo specialized marine construction.
4. How to Safeguard Your Waterfront Business
Closing coverage gaps on your coastal commercial property involves three strategic steps:
- Schedule a Marine Engineering Inspection: Inspect tie-backs, concrete caps, pilings, and underwater footings to establish structural integrity and document baseline maintenance.
- Audit Your Commercial Property Schedule: Review your current declarations page to verify whether seawalls, docks, and piers are listed as covered assets or explicitly excluded under land-based exclusions.
- Secure Dedicated Commercial Marine Coverage: Partner with a specialized agent to place your marine structures with surplus lines or marine carriers that write custom dock and bulkhead coverage in Florida.
Why Working with an Independent Agency Matters
Insuring commercial waterfront property in Florida requires deep expertise in marine underwriting, coastal wind-pool guidelines, and Florida Office of Insurance Regulation (OIR) mandates. At Walker Insurance Agency, we specialize in structuring custom insurance solutions for commercial marinas, coastal resorts, and waterfront businesses.
- Marine Exposure Audits: We examine your commercial coverage to identify hidden marine asset exclusions and eliminate catastrophic liability gaps.
- Access to Specialty Marine Carriers: We partner with leading commercial marine and surplus lines underwriters to secure dock, pier, and seawall coverage tailored to your coastal risk profile.
- Comprehensive Business Protection: We bundle land-based commercial property, marine liability, and loss-of-income coverage into a cohesive, cost-effective risk plan.
Frequently Asked Questions
1. Does Commercial Flood Insurance (NFIP) cover commercial seawalls and docks?
No. National Flood Insurance Program (NFIP) commercial policies cover land-based building structures and contents. NFIP strictly excludes seawalls, bulkheads, retaining walls, docks, piers, and boardwalks over water.
2. Can I insure floating docks that are removed before major hurricanes?
Yes. Many marine insurers offer flexible terms for floating dock systems, especially when a documented hurricane action plan is in place to secure or dismantle temporary floating sections prior to landfall.
3. What causes most seawall failures in Florida?
Most failures occur when heavy rainfall saturates the soil behind the wall while low tides drop water levels in front, creating massive hydrostatic pressure. Wave scour at the base and corroded metal tie-back anchors are also major failure points.
Protect Your Waterfront Business and Assets Today
Don't wait for a storm surge or tidal event to reveal that your standard commercial policy excludes your most valuable coastal infrastructure. Securing proper commercial marine, dock, and seawall coverage protects your business continuity and long-term financial security.
Keep your marine operations, your property, and your business revenue completely secure. Contact Walker Insurance Agency today for a fast, zero-pressure commercial waterfront insurance review.
[GET A FREE FLORIDA COMMERCIAL INSURANCE QUOTE TODAY]
Call our commercial insurance team at +1-407-977-7100 or visit our office at 789 SW Federal Hwy, Ste 201, Stuart, FL 34994. We are always ready to help you navigate Florida insurance options and protect your property.
Related Articles
Seguro Comercial en Florida: Colapso de Muelles y Seawalls (2026)
¿Tienes una marina o negocio costero en Florida? Descubre por qué el seguro comercial estándar excluye muelles, seawalls y barcos de clientes en 2026.
Read More →
¿Cubre el Seguro la Tubería Rota bajo el Jardín en Florida? (2026)
¿Se rompió la tubería principal de agua o drenaje bajo tu jardín en Florida? Descubre quién paga en 2026, los vacíos del seguro estándar y cómo cubrirlo.
Read More →
Florida Sewer Line Collapse: Who Pays for Repairs in 2026?
Who pays when a sewer pipe collapses under your lawn in Florida? Learn why standard home insurance leaves a \$12,000 gap and how service line coverage protects you.
Read More →